
Updated July 16, 2026

Recommended Coverage for Wholesalers & Distributors in St. Petersburg, FL
Wholesalers & Distributors businesses face unique risks that require specific coverage types. Here are the policies most wholesalers & distributors operations need:
General Liability
Essential coverage for every business, protect against third-party bodily injury, property damage, and advertising claims.
Commercial Property
Safeguard your business property, equipment, and inventory against damage and loss.
Commercial Auto
Protect your business vehicles and drivers with comprehensive commercial auto coverage.
Commercial Truck
Comprehensive coverage for trucking operations, from long-haul rigs to local delivery vehicles.
Inland Marine
Protect tools, equipment, and goods in transit or stored at locations away from your primary premises.
Workers Compensation
Help cover your employees' medical expenses and lost wages for work-related injuries and illnesses.
Wholesalers & Distributors Insurance Overview in St. Petersburg, FL
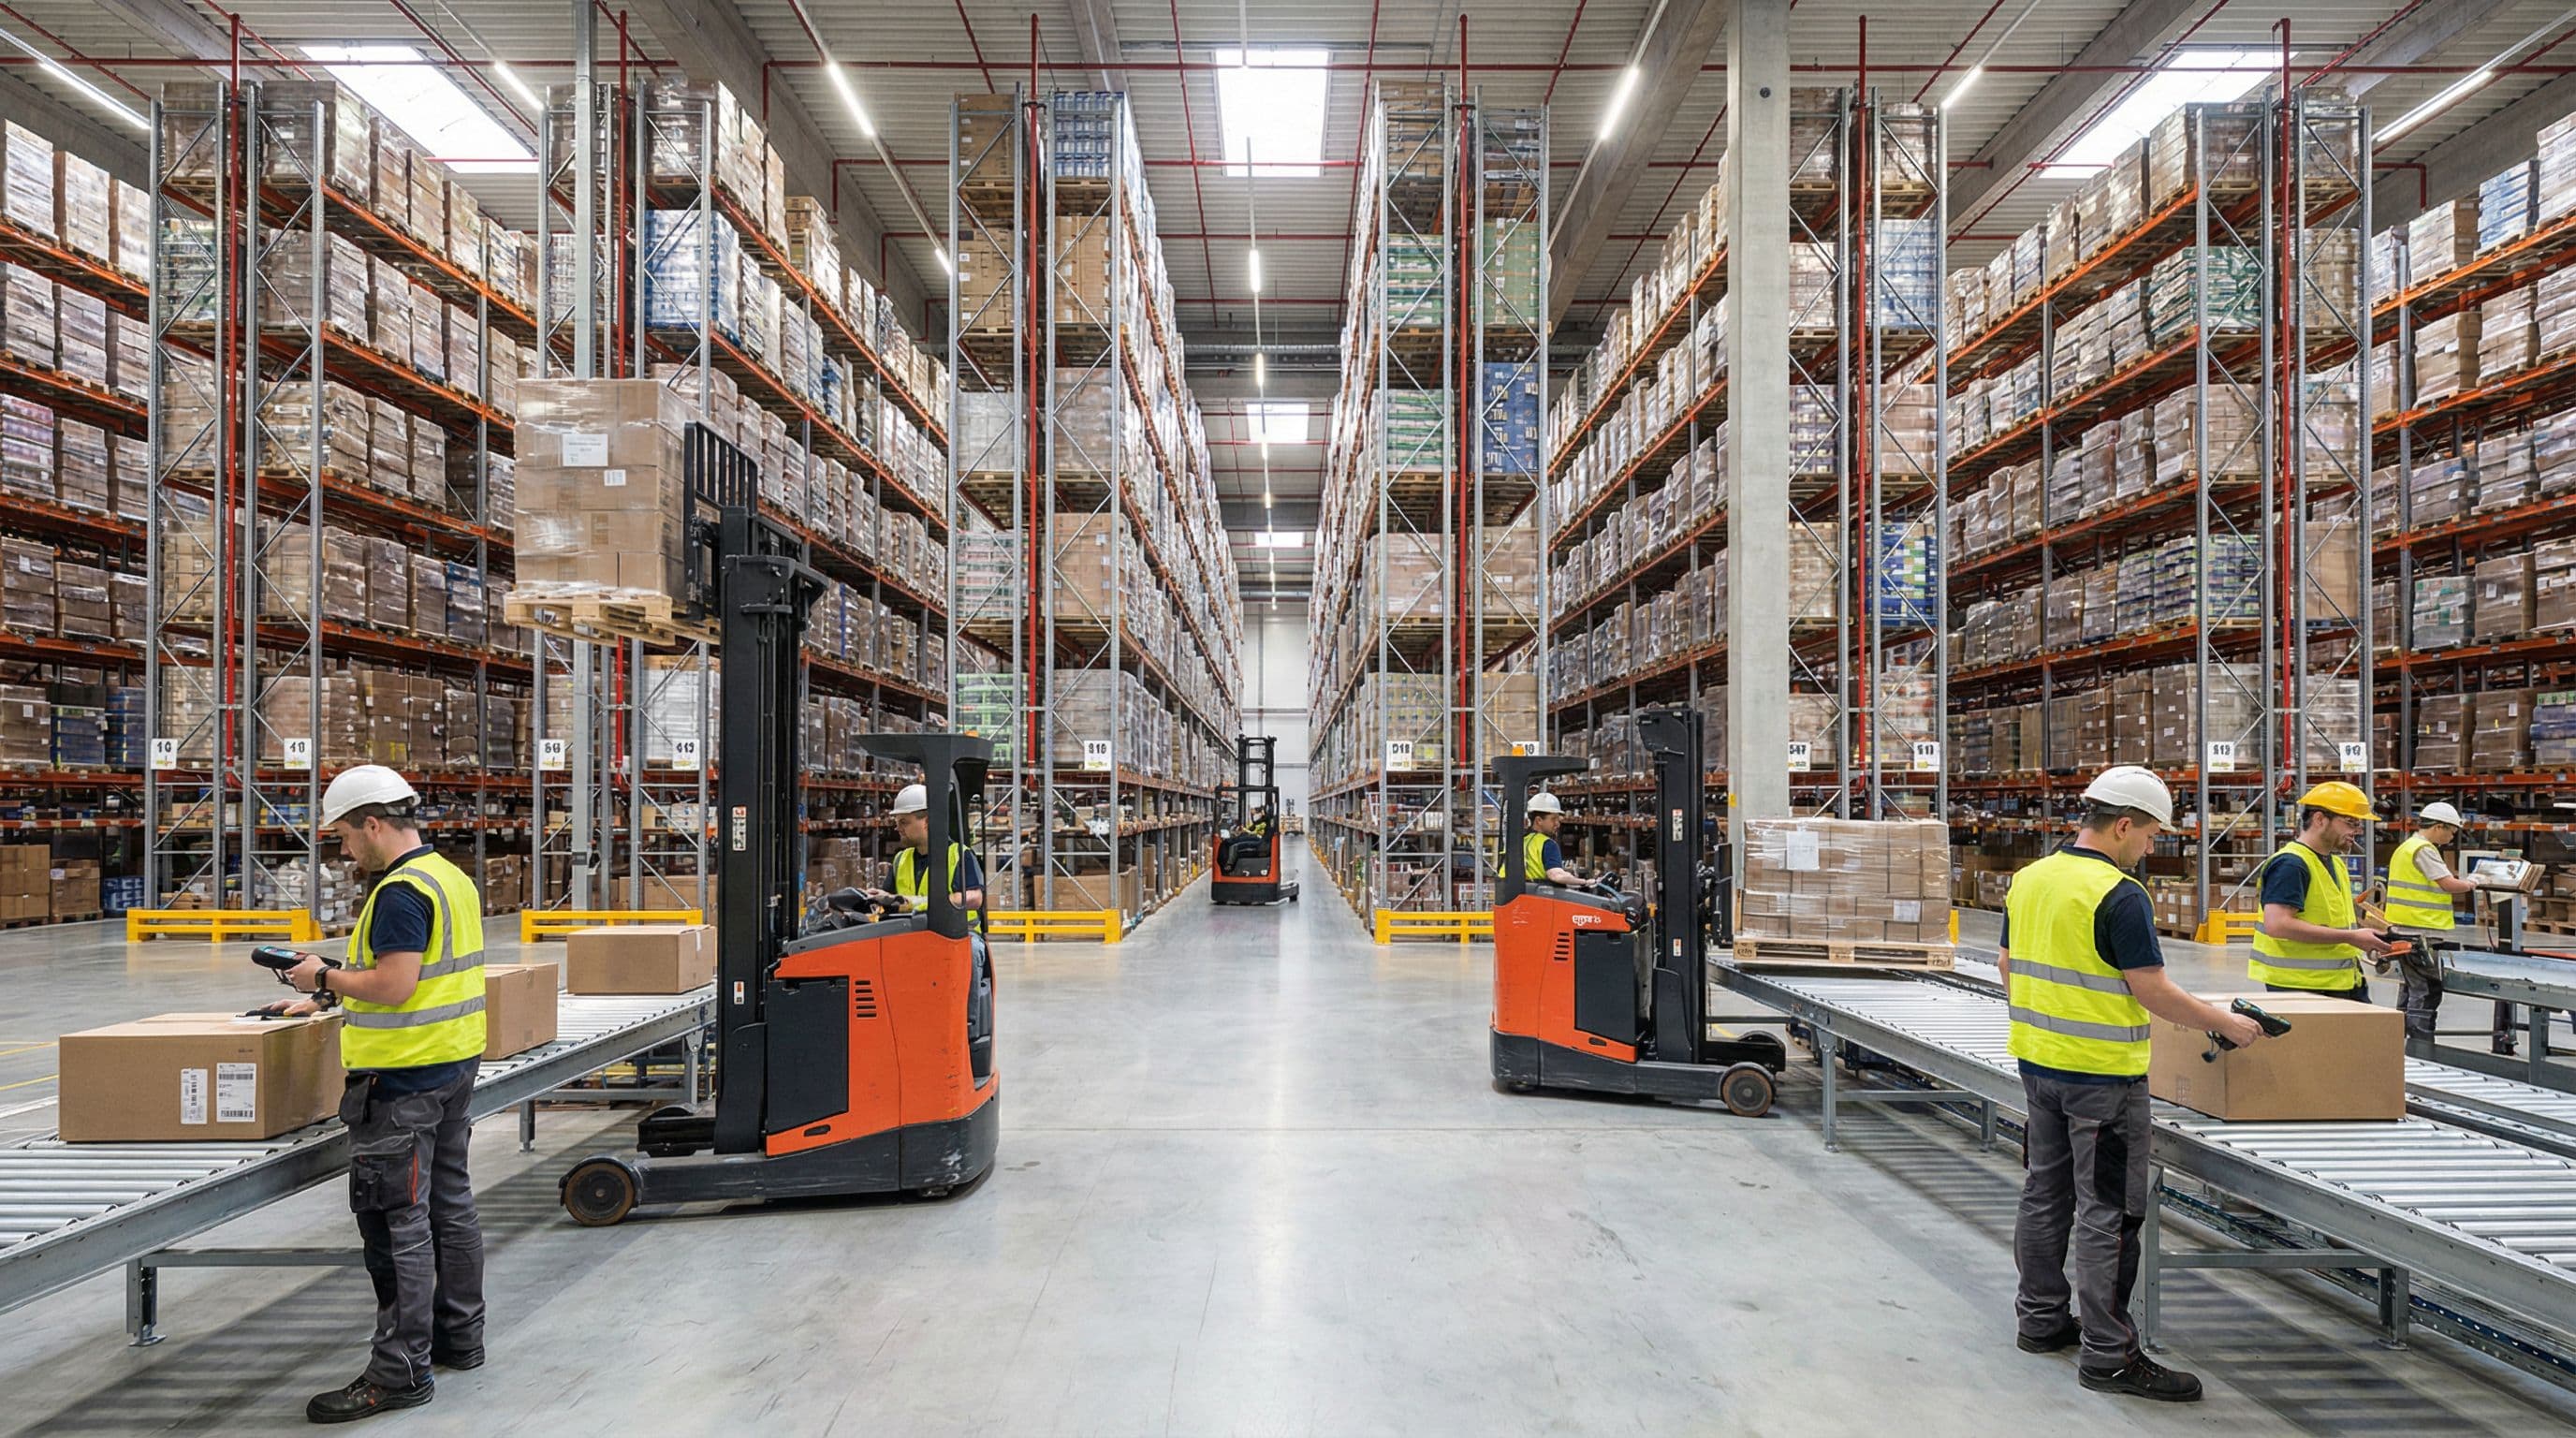
St. Petersburg wholesalers and distributors work in a city where logistics can shift fast. A 23% flood-zone exposure means more than a number on a map. It means your warehouse, your loading dock, and your delivery routes can all face water-related disruptions that stall shipments and damage stock before you can react. The city also deals with high natural-disaster frequency and a crime index of 110, which means your facility is more likely to deal with break-ins or weather shutdowns than a typical business. Businesses serving a local economy that spans healthcare, food service, retail, and construction need protection that fits their actual workflow. A tailored package can align coverage with the way your supply chain really runs, whether you rely on delivery trucks, temporary storage, or goods in transit.
Why Wholesalers & Distributors Businesses Need Insurance in St. Petersburg, FL
St. Petersburg wholesalers and distributors face a mix of warehouse, transit, and premises exposures that can change by neighborhood and by season. Flooding and storm surge are major local concerns, and those risks can affect stock, loading areas, and building operations even when your business is not directly on the waterfront. The elevated crime rate also makes theft prevention and inventory controls especially important for businesses that store high-value goods or keep product moving between facilities, delivery trucks, and customer sites. With 5,683 total business establishments in the city, you are competing for the same secure warehouse space and reliable labor as thousands of other operations, so a gap in coverage can cost you contracts when customers need proof you are protected. Businesses tied to healthcare, retail, construction, and food service may need flexible liability, property, and transit options that match changing shipment patterns. If your operation uses fleet vehicles, handles cargo, or stores tools and mobile property, your policy can help you plan for third-party claims, legal defense, building damage, and business interruption in a way that reflects your specific exposures.
Florida requires workers' comp for businesses with 4+ employees (exemptions may apply: Sole proprietors; Partners). Non-compliance can result in fines and personal liability for owners. Commercial auto minimums are $0/$0/$10,000.
Key Risks for Wholesalers & Distributors Businesses
Each of these risks can lead to claims that cost thousands, or more. Make sure your policy addresses every one:
- Inventory damage or spoilage
- Cargo theft during transit
- Warehouse fire or natural disaster
- Fleet vehicle accidents
- Product liability claims
What Drives Wholesalers & Distributors Insurance Costs in St. Petersburg, FL
In St. Petersburg, your cost is shaped by how much you store, how often goods move, and where your facility sits relative to flood-prone or storm-exposed areas. A 20,000-square-foot warehouse with high-value electronics will carry a very different price tag than a 5,000-square-foot facility storing dry goods inland. If your facility sits in a higher-risk coastal zone or an area with above-average theft, expect pricing to reflect that added exposure rather than treating every location the same.
Wholesalers & Distributors businesses typically carry several separately priced policies. The ranges below are typical figures for St. Petersburg for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $120 - $550 per month | Industry and risk classification, annual revenue, number of employees |
| Commercial Property Insurance | $330 - $1,675 per month | Building value and construction type, roof age and condition, fire protection class |
| Commercial Auto Insurance | $270 - $900 per month | Fleet size and vehicle types, driver records and experience, coverage limits and deductibles |
| Commercial Truck Insurance | $380 - $1,250 per month | Radius of operation, commodities hauled and cargo value, number and value of power units |
| Inland Marine Insurance | $75 - $420 per month | Total insured value of the scheduled property, type and age of the equipment, where it is stored and how far it travels |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
State Requirements
Insurance Regulations in Florida
Key regulatory requirements for businesses operating in FL.
Regulatory Authority
Workers' Compensation InsuranceRequired
Required for employers with 4+ employees.
Exempt categories
- Sole proprietors
- Partners
- Corporate officers (up to 4)
Commercial Auto Minimum Liability
$0/$0/$10,000 (bodily injury per person / per accident / property damage)
Source: Florida Department of Insurance, U.S. Department of Labor
Climate Risk Profile
Natural Disaster Risk in Florida
Understanding climate-related risks helps determine appropriate insurance coverage levels.
Hurricane
Very High
Flooding
Very High
Severe Storm
High
Sinkhole
Moderate
Expected Annual Loss from Natural Hazards
$8.2B
estimated economic loss per year across Florida
Source: FEMA National Risk Index
Insurance Tips for Wholesalers & Distributors Business Owners in St. Petersburg, FL
Match commercial property insurance to the value of stored inventory, shelving, and warehouse fixtures, especially if your location faces storm surge or wind exposure.
Ask whether general liability includes third-party claims tied to customer injury, slip and fall, or property damage at your warehouse or loading area.
Use inland marine coverage when products move between the warehouse, temporary storage, and customer sites across St. Petersburg and nearby routes.
If your business uses delivery trucks or a mixed vehicle pool, review commercial auto and commercial truck coverage based on actual vehicle use.
Check whether your package addresses business interruption if a storm, building damage, or equipment breakdown slows shipments or closes your distribution center.
For warehouse staff, confirm workers compensation is aligned with your employee safety procedures and covers medical costs and lost wages.
Get Wholesalers & Distributors Insurance in St. Petersburg, FL
Enter your ZIP code to compare wholesalers & distributors insurance rates from top carriers.
Business insurance starting at $25/mo
Wholesalers & Distributors Business Types in St. Petersburg, FL
Find insurance tailored to your specific wholesalers & distributors business. Select your business type for coverage recommendations, pricing, and quotes:

Freight Broker Insurance
Get a freight broker insurance quote built for brokerage and logistics operations that need protection when carrier policies do not fully pay a claim. Coverage can be tailored around contingent cargo, E&O, cyber, and crime needs.

Trucking Company Insurance
Get a trucking company insurance quote built around your routes, vehicles, and cargo. Compare coverage for fleets and owner-operators, including commercial auto, cargo, and liability.

Courier & Delivery Service Insurance
Get coverage built for courier operations that face vehicle accidents, package loss, and commercial auto requirements. Compare options for single vehicles, fleets, and local delivery routes.

Warehouse Insurance
Get a warehouse insurance quote built around inventory value, equipment exposure, and premises risks. Coverage can be tailored for warehouses and fulfillment centers.

Import & Export Business Insurance
Import and export business insurance can help wholesalers and distributors with cargo loss, goods in transit, and liability gaps across the supply chain. Get a quote tailored to your routes, shipment types, and trade operations.
FAQ
Wholesalers & Distributors Insurance FAQ in St. Petersburg, FL
Most businesses in this space need a combination of liability protection, property coverage, transit insurance, vehicle policies, and workers compensation. The right mix depends on whether you store inventory, run delivery trucks, or move goods through multiple locations.
Your facility location, inventory value, and vehicle use all influence pricing and coverage design. If you operate in a flood-prone area or a neighborhood with higher theft rates, expect those factors to show up in your quote.
Often, yes. A quote can be built to include property, liability, inland marine for inventory in transit, and vehicle-related coverage, but the final structure varies by operation.
Requirements vary by contract, landlord, lender, and worksite. Many businesses review liability, property, vehicle, and workers compensation needs before signing agreements or moving inventory into a new facility.
Use inland marine coverage for inventory in transit, plus clear handling procedures for loading, unloading, temporary storage, and delivery handoffs. If you use trucks, add vehicle coverage that fits your routes and fleet size.
Gather your warehouse address, a current inventory valuation, your vehicle list, shipment schedules, staff headcount, and any security or storage details. Having those specifics ready lets us match you with participating providers who can build coverage around your actual operations.
Six policies cover the standard footprint: general liability, commercial property, commercial auto, commercial truck, inland marine, and workers compensation. Whether you mainly store stock, run deliveries, use heavier vehicles, or move goods through several locations decides which of them carries the load.
Generally not once it leaves the insured location, which is the point of the question. Property forms center on scheduled premises, so goods in transit or temporary storage belong in the inland marine review, especially if drivers move product daily or shipments stage before customer acceptance.