Updated July 5, 2026

On-Hook Towing Insurance in Savannah
Port and visitor traffic is the sharpest difference here, because your tow routes can swing from hotel and restaurant corridors to retail lots and port-adjacent commercial streets in the same shift. That changes how you should present your operation to an underwriter: not with generic towing language, but with a clear picture of where your calls originate, what kinds of vehicles you move, and whether you handle short local relocations, private-property removals, or more complex recoveries. If you are shopping for on-hook towing insurance in Savannah, that operating mix matters more than a broad city label. Chatham County has 8,829 business establishments, so a local tow operator often works around dense commercial property relationships where lot owners, managers, and vendors expect clean certificates and clear loss reporting if a vehicle is damaged while in tow. The county business mix also leans toward retail trade, accommodation and food services, and health care, so your book of work may involve customer vehicles from shopping centers, hotels, restaurants, and medical campuses rather than one predictable source. Before you request quotes, map your last few months of calls by property type and tow purpose, then ask for terms that match that pattern.
On-Hook Towing Insurance Risk Factors in Savannah
Local risk here is less about a unique Georgia peril and more about where vehicles are picked up and dropped off. In a market with heavy retail, lodging, dining, and health care activity, a tow can start in a tight parking deck, a busy hotel drive, a shopping center lane, or a medical office lot where space is limited and bystanders are close. That matters for on-hook coverage because underwriters want to understand not just the vehicle being towed, but the conditions around hookup, loading angle, turning room, and delivery point. Chatham County's leading sectors are retail trade at 15.8%, accommodation and food services at 13%, and health care and social assistance at 10.7%, so you should describe the property environments your drivers work in, not just say you do "light-duty towing." A better submission lists common pickup settings, whether you use dollies or flatbeds for certain jobs, and how drivers document pre-existing damage before transport.
Georgia has a high climate risk rating. Top hazards: Hurricane (High), Tornado (High), Severe Storm (High), Flooding (Moderate). The state's expected annual loss from natural hazards is $2.4B, which influences on-hook towing insurance premiums and may affect coverage availability in high-risk areas.
What On-Hook Towing Insurance Covers
The real exposure is not the basic definition of on-hook coverage, but the handoff moments where claims widen. A policy review should focus on who inspected the vehicle before hookup, what pre-existing damage was noted, whether photos were taken at pickup, and how the destination condition was confirmed.
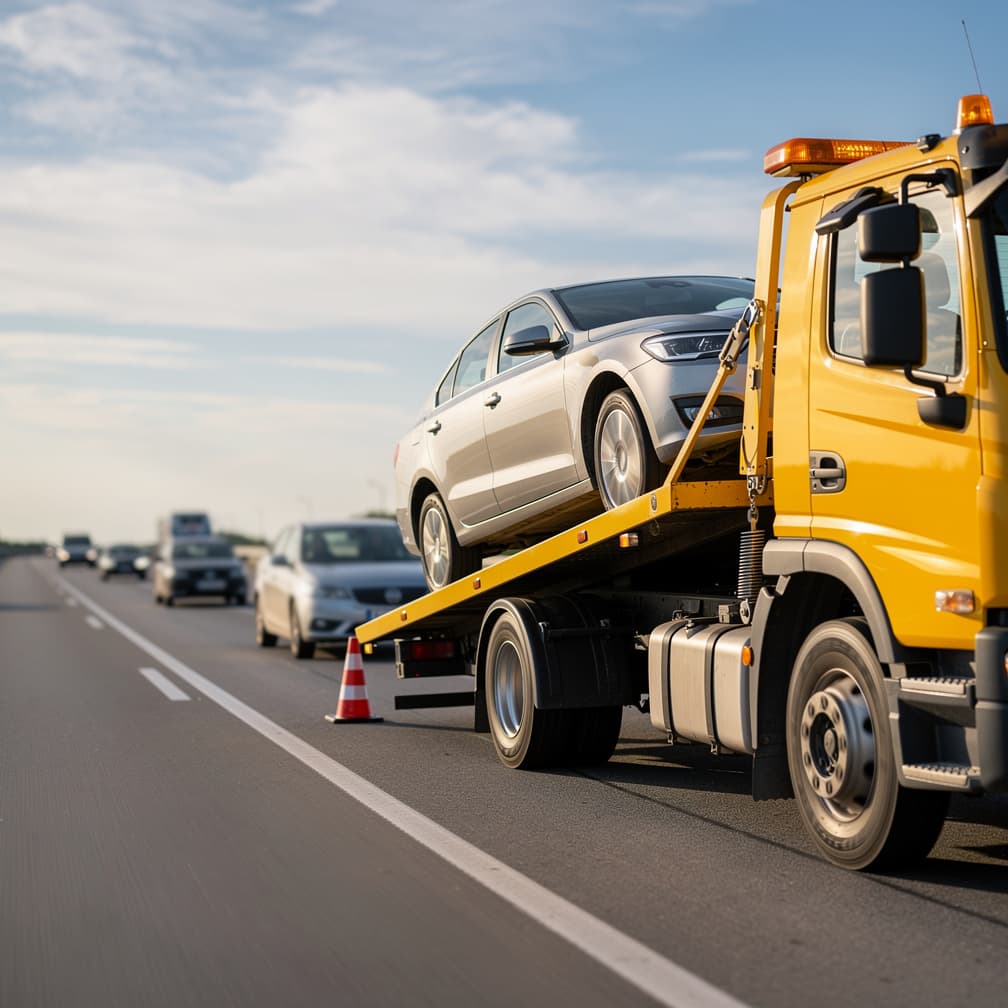
You should also look closely at how your policy treats different operating patterns. A truck doing scheduled transport for repair shops or auctions presents a different claims profile than a unit dispatched to roadside breakdowns or weather-related recoveries. If your operation does more than one of those, ask for wording and limits that are reviewed against each service line rather than assuming one setup fits the whole fleet.
The practical coverage question is whether the policy structure matches your equipment and loading methods. Flatbeds, wheel-lifts, dollies, and winching setups create different damage scenarios, and those scenarios affect how a claim is investigated. You should ask how the policy responds to loading and unloading allegations, whether attached vehicles are treated consistently across your equipment types, and what documentation the carrier expects after an incident.
It also helps to review where your exposure shifts during severe weather and roadside recovery conditions. Wet shoulders, fallen limbs, and low-visibility scenes can complicate both the tow and the later claim narrative. Before renewing, compare your current form against your actual dispatch mix and ask for any endorsements in writing, not verbal assumptions.
Coverage Included
Collision on Hook
Covers damage to towed vehicles from collisions during transport.
Comprehensive on Hook
Covers theft, fire, and weather damage to vehicles being towed.
Loading & Unloading
Covers damage during the process of loading and unloading vehicles.
Winching Coverage
Covers damage to vehicles during winching and recovery operations.
Multiple Vehicle
Covers all vehicles on multi-car carriers and rollback flatbeds.
Industries & Insurance Needs in Savannah
Commercial density is what changes demand here. Chatham County reports 8,829 business establishments, and its largest establishment shares are retail trade, accommodation and food services, and health care and social assistance. For a towing business, that usually means more work tied to private lots, customer parking areas, service entrances, and time-sensitive vehicle moves around active businesses. The insurance consequence is practical: carriers may want a sharper picture of your client mix, dispatch pattern, and documentation habits because claims can arise from where a vehicle was taken, how it was loaded, and what condition it was in before tow. This is also why a vague application can slow down quoting. If a large share of your calls comes from hotels, shopping centers, restaurants, or medical properties, say that plainly and separate those jobs from dealer transfers, roadside calls, or recovery work so the policy review matches your real exposure.
What Makes Savannah Different
Port and service-corridor towing is the one thing that changes the calculus here. In many Georgia markets, a tow company can describe its work in broad categories and still be understood. Around Savannah, that is often not enough, because your operation may touch visitor-heavy districts, retail properties, medical campuses, and commercial corridors tied to freight movement, all within a compact service area. That mix creates more variation in where a loss can happen and who is involved after it happens, from a property manager to a business tenant to the vehicle owner. The result is that your on-hook review should focus on job-source clarity. Break out private-property towing, roadside assistance, dealer or fleet moves, and any recovery work. Note where vehicles are usually stored, how condition photos are captured, and who signs off at release. The more precisely you describe those handoffs, the easier it is to compare terms that fit your actual operation.
Our Recommendation for Savannah
Start with your dispatch records, not your current declarations page. Pull a recent sample of jobs and sort them by source, hotel or restaurant property, retail lot, medical office or campus, roadside call, dealer transfer, or recovery. That gives you a cleaner way to discuss exposure than broad labels like light-duty or mixed towing. Next, review how your drivers document vehicle condition before hookup and at drop-off. In a service market with many customer-facing properties, timestamped photos, signed releases, and consistent storage logs can matter as much as the limit you buy. If your work includes private-property towing, ask specifically how the policy responds to damage allegations discovered after release, and whether any operational conditions affect claim handling. Savannah's median household income is $56,782, so even a modest damage dispute can be financially significant for the vehicle owner and reputationally significant for your business. Bring your contracts, sample invoices, and dispatch categories to the quote request so coverage terms can be reviewed against real jobs.
Get On-Hook Towing Insurance in Savannah
Enter your ZIP code to compare on-hook towing insurance rates from carriers in Savannah, GA.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
Savannah operators should lead with dispatch detail: where calls come from, what types of properties generate work, what vehicles are towed, and how condition photos are handled. That helps an underwriter separate private-lot, roadside, dealer, and recovery exposure instead of pricing from a vague description.
Savannah area commercial density can change the review because Chatham County has 8,829 business establishments. That means more towing tied to retail lots, hotels, restaurants, and medical properties, so insurers often want clearer documentation of pickup conditions and release procedures.
Savannah applications should identify those properties because the county's largest sectors include retail trade at 15.8% and accommodation and food services at 13%. Those locations can involve tighter access, more bystanders, and more questions about pre-tow condition and authorization.
Savannah medical-property towing can be a different conversation because health care and social assistance accounts for 10.7% of county establishments. If your drivers work around clinics or campuses, explain loading space, traffic flow, and documentation steps before comparing terms.
Savannah buyers with regulator questions can look to the Georgia Office of Insurance and Safety Fire Commissioner. For shopping purposes, use that as a backstop, then focus first on whether the quote matches your actual tow mix, documentation process, and handoff points.
Yes. Impound claims often come down to condition, custody, and documentation during the tow, so this coverage can help protect your business when a vehicle owner disputes damage.
Insurers usually underwrite those services differently because roadside calls, recovery scenes, and after-hours dispatches can create a different damage profile than scheduled dealer moves. Ask for quotes built around each service category, not one blended description.
Insurance regulation is overseen by the Georgia Office of Insurance and Safety Fire Commissioner, so policy review and complaint pathways run through that office. Use Georgia-issued policy documents and endorsements when you compare terms, not generic marketing summaries.
Sources
- 1.U.S. Census Bureau, County Business Patterns, Chatham County(Chatham County has 8,829 business establishments, so a local tow operator often works around dense commercial property relationships where lot owners, managers, and vendors expect clean certificates and clear loss reporting if a vehicle is damaged while in tow.; Chatham County's leading sectors are retail trade at 15.8%, accommodation and food services at 13%, and health care and social assistance at 10.7%, so you should describe the property environments your drivers work in, not just say you do "light-duty towing.")
- 2.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Savannah's median household income is $56,782, so even a modest damage dispute can be financially significant for the vehicle owner and reputationally significant for your business.)
- 3.Georgia Office of Insurance and Safety Fire Commissioner(Savannah buyers with regulator questions can look to the Georgia Office of Insurance and Safety Fire Commissioner.)
Updated July 5, 2026