Updated July 16, 2026

Dealer Open Lot Insurance in Chicago
Chicago dealer open lot insurance is not handled the same way it would be elsewhere in Illinois. Local underwriting usually gets tighter once your inventory sits inside a denser, faster-moving market with more off-site relationships, more vehicle movement, and less room for loose documentation. What matters is not just how many units you carry but the clarity of your custody trail: where each vehicle is stored, who holds it, how keys are controlled, and whether overflow arrangements, service pickups, and transport between locations follow the same routine every time. Cook County has 134,846 business establishments, which means your dealership likely operates in closer physical proximity to other businesses than a rural dealer would. When a dealer can produce organized records on short notice, underwriters tend to see a lower risk of disputes over custody, property access, and lost units.
Dealer Open Lot Insurance Risk Factors in Chicago
Chicago's top risk factors include Tornado damage, Hail damage, Severe storm damage, and Wind damage.
Illinois has a high climate risk rating. Top hazards: Tornado (Very High), Severe Storm (High), Flooding (High), Winter Storm (High). The state's expected annual loss from natural hazards is $3.2B, which influences dealer open lot insurance premiums and may affect coverage availability in high-risk areas.
What Dealer Open Lot Insurance Covers
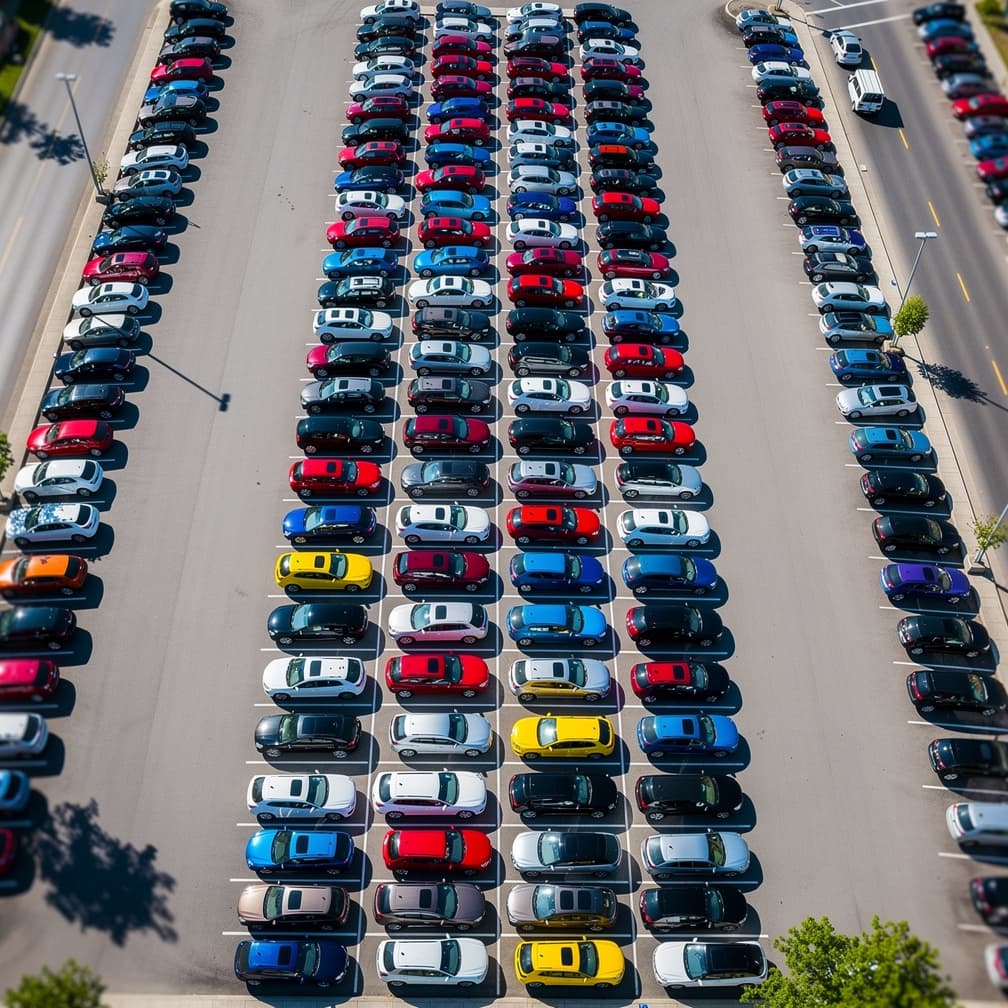
A dealer open lot policy may help cover vehicles you hold for sale against physical damage from theft, weather, fire, and vandalism. What matters is how your inventory is actually arranged and moved. A dealership with one fenced lot presents a different exposure than an operation using a back lot, a service-area holding row, and temporary overflow storage during buying spikes. That is why your coverage review should map each place where sale units sit, who has access, and when vehicles leave the main premises.
You should also look closely at how the policy treats ordinary dealership handling. That includes employee movement around the lot, transfers between scheduled locations, and any short-term storage arrangement that is easy to overlook during the application. If your operation mixes front-line inventory with units waiting on reconditioning, ask for clear treatment of those vehicles so there is less ambiguity if a claim happens before the car is retail-ready.
Weather patterns also make claim documentation important. If multiple units are damaged in one event, you want a process for proving which vehicles were on hand, where they were parked, and what their values were at the time of loss. Good photos, timestamped inventory reports, and consistent key control can matter as much as the policy form itself when a claim is adjusted.
If you are comparing forms or claim handling language, keep your questions specific and tied to the wording you are being offered. Ask for a line-by-line review of location schedules, valuation method, deductibles, and any exclusions tied to unattended vehicles, offsite storage, or employee use before you bind coverage.
Coverage Included
Weather Damage
Covers hail, wind, flood, and storm damage to lot inventory.
Theft Protection
Covers vehicles stolen from your lot.
Fire Damage
Covers fire and explosion damage to inventory vehicles.
Vandalism
Covers intentional damage to vehicles on your lot.
Test Drive Coverage
Covers vehicles during customer and employee test drives.
Transit Coverage
Covers vehicles being moved between lot locations.
What Makes Chicago Different
That focus on inventory movement matters if you keep sale units on the main lot, stage vehicles at a secondary address, send units out for detail or mechanical work, or rotate inventory to make room for incoming stock. Professional, scientific, and technical services account for 14.2% of establishments, health care and social assistance 11.9%, and retail trade 10.1% in Cook County, so your neighboring businesses are more likely to be professional offices or clinics than heavy industrial operations. Those neighbors tend to formalize vendor, parking, and property-access expectations, which means a dealer sharing a lot or alley with them faces more scrutiny if a vehicle goes missing or a dispute arises over access. Treat every storage address, handoff point, and key-control step as something an underwriter may want to see in writing before terms are finalized.
Our Recommendation for Chicago
Start with a location-by-location inventory process, not a single total unit count. If vehicles move between the sales lot, overflow storage, service areas, or third-party vendors, keep a dated trail that shows where each unit sits and who last handled it. Review whether your schedule of locations matches how the operation actually runs this month, not how it ran last renewal. If you use shared lots, alley access, stacked parking, or nearby commercial storage, ask whether those arrangements should be specifically described before binding. Chicago median household income is $75,134, which translates to a customer base that can support a wider spread of vehicle prices on a single lot. When a single lot may hold a $12,000 work truck next to a $60,000 luxury SUV, accurate reporting of higher-value units and fast-changing inventory becomes more important during quoting and after a loss. Before you request terms, gather your current inventory file, storage addresses, vendor custody arrangements, and key and camera procedures so the quote reflects the operation you really have.
Get Dealer Open Lot Insurance in Chicago
Enter your ZIP code to compare dealer open lot insurance rates from carriers in Chicago, IL.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
Yes. Disclosing each lot, overflow space, and recurring off-site location up front gives underwriters a clearer picture of where vehicles sit and how exposure is distributed across sites.
Chicago underwriters usually want a clear schedule of locations, a current inventory file, and a consistent record of vehicle movement between addresses. If units rotate often, dated transfer logs and key-control procedures can help show that inventory is being tracked deliberately.
Yes. More neighbors and vendor relationships usually mean more certificates, contracts, and access agreements that underwriters may ask to review before finalizing terms.
Chicago inventory documentation matters because denser operations often involve tighter space, more frequent vehicle movement, and more off-site handling. If a loss happens, clean records of unit values, locations, and transfers can make the claim review more straightforward.
Have an updated inventory list, current values, all storage addresses, and any vendor custody details ready for review. A customer base that spans a wide income range often means a broader mix of vehicle values on your lot, and underwriters want to see that mix accurately reflected.
Buyers get better quote results when they prepare a current inventory schedule, confirm every storage address, and document key control and after-hours access. Keep your review focused on policy wording, disclosures, and how each location is scheduled before you bind.
Dealerships should list each location where sale inventory is stored, including overflow or secondary space. If a quote assumes one address but vehicles regularly sit elsewhere, you can create avoidable claim questions later.
Dealers should not assume an older setup still fits after adding overflow storage. A new address, different security controls, or regular vehicle transfers can change how the risk is underwritten and how a claim is reviewed.
Sources
- 1.U.S. Census Bureau, County Business Patterns, Cook County(Cook County has 134,846 business establishments, so dealers often work around nearby vendors, lenders, repair partners, and commercial neighbors who expect organized certificates, site schedules, and clean operating records before a transaction moves forward.; Professional, scientific, and technical services account for 14.2% of establishments, health care and social assistance 11.9%, and retail trade 10.1% in Cook County, so many surrounding businesses operate with formal vendor, parking, and property-access expectations.)
- 2.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Chicago median household income is $75,134, so buyers here may shop across a wide range of vehicle values and financing expectations, which makes accurate reporting of higher-value units and fast-changing inventory more important during quoting and after a loss.)
Updated July 16, 2026