
How Uber driving changes your car insurance risk
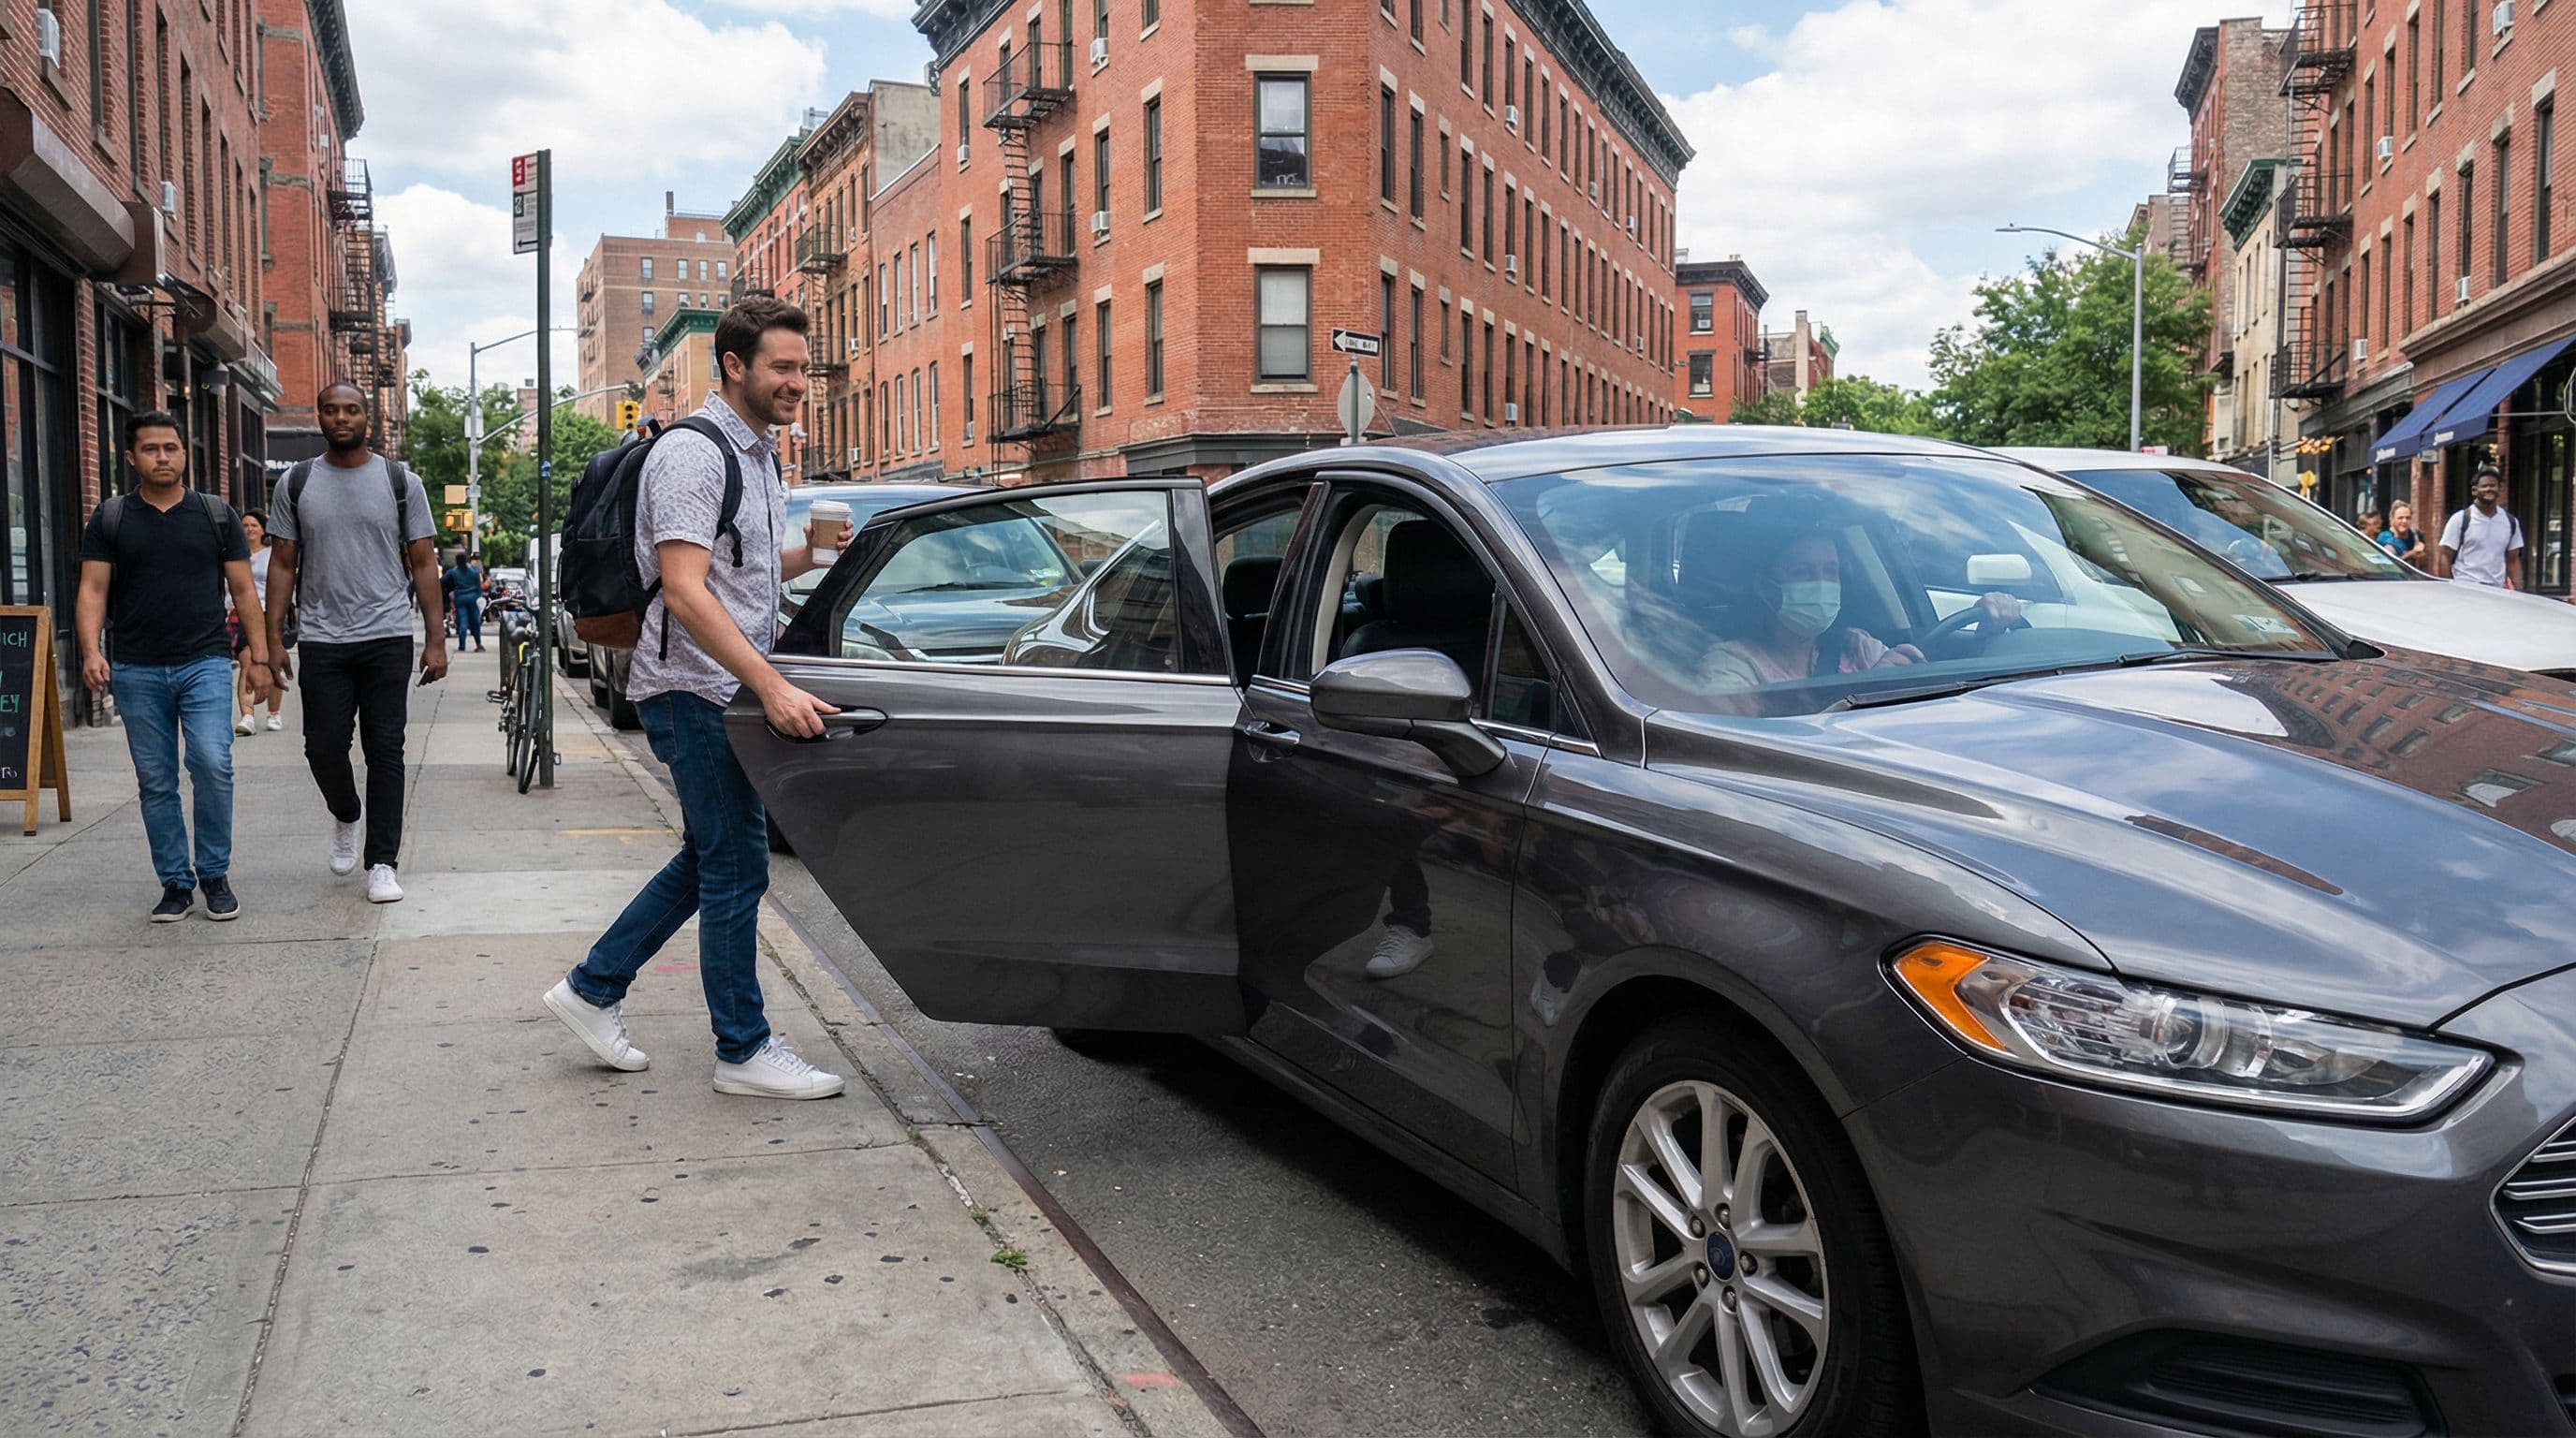
Car insurance for Uber drivers starts with one practical question: what happens to your coverage while you are waiting for a ride request, driving to a pickup, or carrying a passenger? That timing issue is where many buying mistakes begin. A personal auto policy may be written for commuting, errands, and household use, while rideshare work adds business use, more time on the road, unfamiliar pickup points, late-night driving, and frequent stop-and-go exposure.
Your risk also changes hour by hour. One shift may include airport queues, downtown pickups, apartment complexes with tight parking lots, and highway miles between trips. Another may be mostly short urban rides with constant door openings, curbside stops, and distracted traffic around entertainment districts. If you drive full time, the annual mileage, wear on the vehicle, and chance of a claim look different from a household car used only for personal errands.
That is why the right buying approach is not to ask for price alone. It is to map your actual driving pattern to the policy language. Tell the agent or broker that you drive for Uber, whether the car is used only for rideshare or also for family use, who else drives it, whether you rent or own the vehicle, and whether you work peak hours, weekends, or airport runs. Then ask them to explain, in plain language, how the policy responds during each phase of app-on driving before you request a quote.
What coverage Uber drivers need to review
For most drivers, the core coverage stack starts with car insurance, but the important part is how the policy handles rideshare activity rather than the label on the declarations page. You want the quote built around app-based driving, not around ordinary personal use with assumptions that do not match your work. If you are comparing options, start with car insurance coverage options and then narrow the discussion to rideshare use, vehicle damage, and liability limits.
Begin with liability. If you injure someone or damage another vehicle, you need to know which policy responds in each driving period and whether your own policy excludes commercial or livery-type activity. Then review physical damage coverage for your own car, especially if the vehicle is financed or if losing it for even a few days would stop your income. Ask how collision and comprehensive apply, what deductible you would face, and whether there are conditions tied to rideshare endorsements or business-use classifications.
Uninsured or underinsured motorist coverage is also worth a close look because rideshare drivers spend more time exposed to other motorists, including drivers with low limits or no coverage at all. Medical payments or personal injury protection may matter too, depending on how you want injuries handled after a crash. If you lease or finance the car, ask whether gap-related protection is available and appropriate. The goal is simple: line up the policy with how you actually earn money, then confirm there is no silent gap between personal driving and Uber work.
What drives the cost of car insurance for Uber drivers
The price of car insurance for Uber drivers turns on exposure, vehicle details, and how the insurer classifies your use, not on a generic online estimate. The more useful question is what information will move the quote up or down, because that tells you what to prepare before you shop.
Mileage is one of the first drivers. A vehicle used for rideshare often spends far more time on the road than a household car, and that can change how an underwriter views accident frequency. Territory matters too. Dense urban driving, airport traffic, nightlife corridors, and heavy commuter routes can all affect the risk profile because they increase the number of interactions with other vehicles, pedestrians, and curbside hazards. Your driving record, prior claims, years licensed, and any lapse in coverage also shape the quote.
Vehicle choice matters more than many drivers expect. Repair costs, parts availability, theft exposure, safety features, and the car's value all influence physical damage pricing. A newer financed vehicle may need broader protection than an older car you could afford to replace yourself. Deductible selection also changes the monthly cost, but raising it only makes sense if you could comfortably pay that amount after a loss.
To get a quote that is actually usable, prepare your annual mileage estimate, VIN, garaging address, financing status, rideshare schedule, and current declarations page. Then ask each quoting source to show the same liability limits, the same deductibles, and the same rideshare treatment so you are comparing structure instead of guessing from price alone.
Average Car Insurance Cost
$110 - $230
per month
Nationally, car insurance coverage typically runs $110 - $230 per month.
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, personal details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
How to compare Uber driver quotes without missing a coverage gap
A good quote comparison for Uber driving is less about collecting many prices and more about forcing each option onto the same worksheet. If one quote assumes personal use, another includes rideshare use, and a third changes deductibles or liability limits, the numbers are not really comparable.
Start by standardizing the basics. Use the same vehicle, drivers, garaging address, annual mileage, and requested effective date on every quote. Then keep the liability limits consistent. If you want physical damage coverage, keep collision and comprehensive deductibles the same as well. After that, ask the most important question: how is rideshare activity handled, and where does the policy stop or start responding? You are looking for a clear explanation of coverage during waiting for a request, en route to pickup, and during the trip itself.
Next, review exclusions and endorsements. Ask whether food delivery, package delivery, or any other app work is excluded if you do more than Uber driving. Confirm whether the policy may cover a temporary substitute vehicle, a newly acquired vehicle, or another household driver who may use the car off shift. If you rely on one vehicle for both income and family transportation, those details matter quickly after a claim.
Finally, compare claims handling practicalities. Ask what documentation would be needed after a rideshare loss, whether app records may be requested, and how quickly you would need to report the accident. A quote is only useful if you understand how it performs on a real Tuesday night after a fender bender, not just how it looks on a screen.
Mistakes Uber drivers make when buying car insurance
The most common mistake is assuming a personal auto policy automatically follows the car into rideshare work. Many drivers buy coverage for the vehicle they own, but not for the way they use it. That can leave you arguing about business-use exclusions after a crash instead of focusing on repairs, injuries, and getting back on the road.
Another mistake is shopping on monthly price alone. A lower premium can come from lower liability limits, higher deductibles, or a policy structure that does not fit app-based driving. If your car is your income source, a weak policy can cost far more than it saves. Review the declarations page and endorsements line by line before you bind coverage.
Drivers also forget to update the policy when their work changes. Maybe you start driving more nights, add airport runs, switch vehicles, move addresses, finance a newer car, or let another household member use the vehicle regularly. Each change can affect eligibility, rating, or how a claim is handled. Report those changes before renewal if possible, not after an accident.
A final mistake is failing to ask direct questions. Ask whether the policy is intended for Uber driving, whether any app-based activity is excluded, what deductibles apply to your own vehicle, and what documents you should keep in the car and in the app. If the answers are vague, keep shopping until the coverage structure is clear enough that you could explain it back in your own words.
What to do before you buy a policy for rideshare work
Before you buy, write down exactly how you use the car. Include whether you drive part time or full time, the times of day you usually work, the areas you serve, whether you also use other apps, and whether the vehicle has a loan or lease. That short operating summary helps the quote match your real exposure instead of a generic personal-use profile.
Next, gather the documents that make quote comparisons cleaner: your current declarations page, driver license information for every household driver, vehicle registration, VIN, lienholder details if any, and a realistic mileage estimate. If you have had tickets, accidents, or prior claims, disclose them accurately. A fast quote built on incomplete information is not helpful if it changes later.
Then decide what tradeoffs you can actually absorb. If a higher deductible lowers the premium, could you pay it without interrupting your work? If you skip physical damage on an older car, could you replace the vehicle after a total loss? If another household member depends on the same car, would a claim create a transportation problem beyond your rideshare income? Those are buying decisions, not just insurance terms.
Once you have that list, request quotes built on the same assumptions and ask for the rideshare treatment in writing. Review the policy forms before payment, confirm the effective date, and keep proof of coverage accessible in the vehicle and on your phone. That gives you a cleaner starting point before your next shift begins.
Frequently Asked Questions
Uber drivers usually need car insurance that is written or endorsed for rideshare activity, not just ordinary personal use. Ask how the policy responds while the app is on, while you are heading to a pickup, and while a passenger is in the car.
Personal car insurance may not fully cover Uber driving because many policies are built for household use rather than app-based work. Review exclusions, business-use language, and any rideshare endorsement before you assume a claim would be covered.
Standardize the inputs: use the same liability limits, deductibles, vehicle details, mileage, and driver information on every quote. Then focus on the policy language for rideshare use, because a lower price is not helpful if the coverage structure leaves a gap.
If you drive for Uber, collision and comprehensive are worth reviewing if the car is financed, newer, or difficult to replace quickly. If losing the vehicle would stop your income, physical damage coverage may be more important than the monthly savings from dropping it.
Ask whether rideshare activity is covered, which driving periods are included, what deductibles apply to your vehicle, and whether any other app work is excluded. Get those answers clearly enough that you can match them to your actual driving routine.
Request a Quote Comparison
Enter your ZIP code to compare insurance rates from top carriers.
Updated July 17, 2026