Updated July 16, 2026

Dealer Open Lot Insurance in Baton Rouge
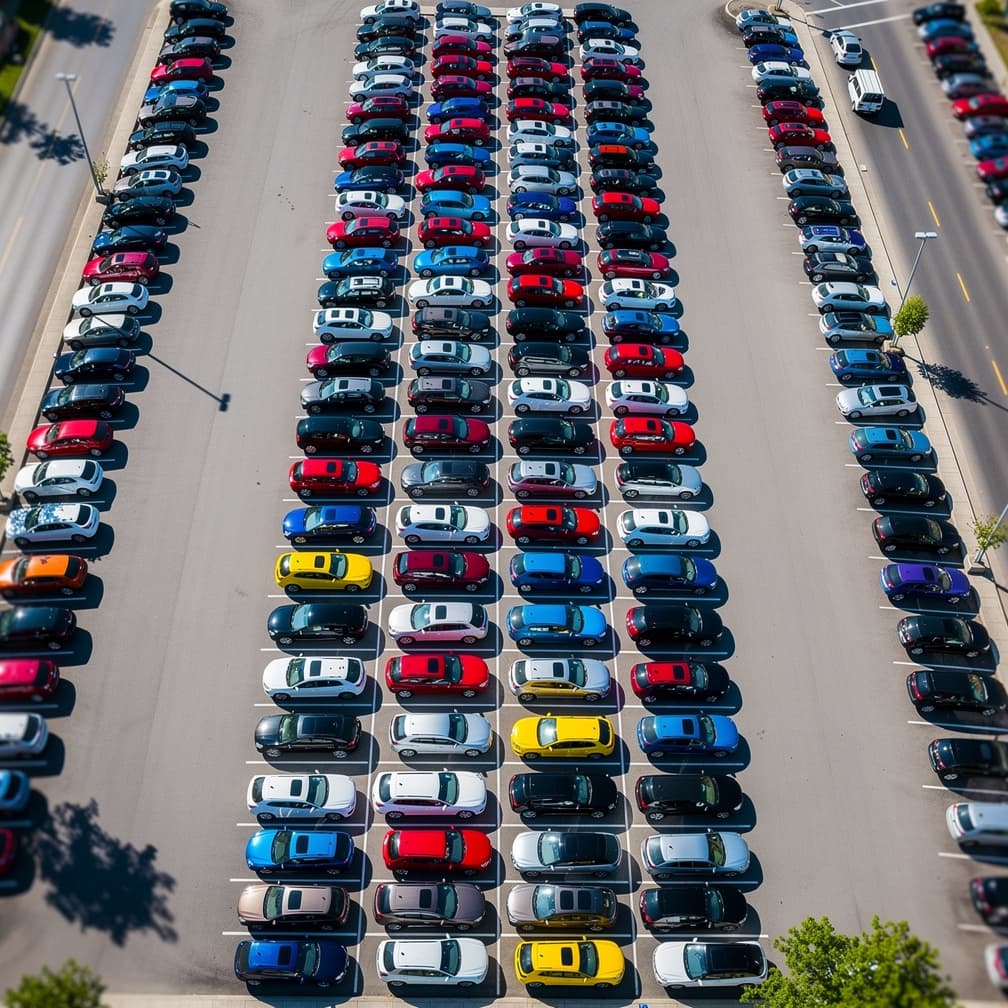
The decision point usually arrives fast. You sign a lease for a small frontage lot, line up your first transport, or add overflow parking before a seasonal sales push, and suddenly the lender, landlord, or floorplan partner wants proof that your inventory is scheduled correctly. Your real exposure is rarely just the cars on the main display line, so the coverage conversation has to get specific quickly. You may be holding units behind a service building, staging fresh arrivals at a secondary address, or rotating vehicles between a visible retail strip and a lower-cost storage area.
East Baton Rouge Parish has 12,520 business establishments, so your neighboring tenants are more likely a busy auto shop or a medical clinic than a quiet residential property. For you, that raises practical questions about fencing, lighting, neighboring tenants, and how clearly each storage area is identified on your submission. If your operation touches more than one address, ask for the schedule of locations, maximum values by site, and transit assumptions to be reviewed before binding.
Dealer Open Lot Insurance Risk Factors in Baton Rouge
The local risk issue is site spread. Here, dealers often piece together inventory space from the retail lot they show customers, a back parcel, and temporary overflow arrangements that make operational sense but can create avoidable coverage gaps if values are not assigned carefully. Louisiana's broader weather exposure is already part of the state conversation, but at the city level the buying decision is more practical: where each unit sleeps at night, who can move it, and whether the carrier sees one controlled location or several different risk profiles. That means your application should match the way inventory actually moves this month, not the way the business looked when the policy first started. If you use a second address for reconditioning overflow, auction holds, or recently acquired units waiting for front-line space, have that address and its peak values reviewed. A lot schedule that is even slightly outdated can create the wrong limit structure at the wrong location.
Louisiana has a very high climate risk rating. Top hazards: Hurricane (Very High), Flooding (Very High), Severe Storm (High), Tornado (Moderate). The state's expected annual loss from natural hazards is $4.8B, which influences dealer open lot insurance premiums and may affect coverage availability in high-risk areas.
What Dealer Open Lot Insurance Covers
A dealership with a front sales line, an overflow lot, and a reconditioning area creates different handling points, and each one should be reflected in the schedule you submit. If a unit spends part of the week at a body shop, detail area, auction pickup point, or temporary storage yard, ask how that location is treated before you assume the same protection follows automatically.
You should also review how the policy values vehicles after a loss. That matters most when your inventory turns quickly, when recently acquired units have not yet been fully updated in your system, or when higher value trucks, specialty vehicles, or rebuilt units sit beside lower value inventory. Your policy should reflect how you actually buy, hold, repair, and display vehicles across every site you use.
Louisiana weather exposure adds another layer. Instead of stopping at a broad request for weather protection, ask whether your limits, reporting method, and location schedule still make sense during peak inventory periods or after you shift units around the property to make room for deliveries and repairs. If your operation uses more than one address, confirm whether each site is specifically listed and whether temporary concentration of vehicles at one location creates a gap. That is often where a claim dispute starts.
A practical review also includes key control, perimeter security, camera placement, and who can move vehicles after hours. Those details shape how defensible your file looks if a theft, vandalism, or weather loss happens. Ask for wording and limits that fit your actual lot operations, then compare terms line by line before you buy.
Coverage Included
Weather Damage
Covers hail, wind, flood, and storm damage to lot inventory.
Theft Protection
Covers vehicles stolen from your lot.
Fire Damage
Covers fire and explosion damage to inventory vehicles.
Vandalism
Covers intentional damage to vehicles on your lot.
Test Drive Coverage
Covers vehicles during customer and employee test drives.
Transit Coverage
Covers vehicles being moved between lot locations.
What Makes Baton Rouge Different
What sets Baton Rouge apart is how often inventory lives at more than one address. In some markets, a dealer can keep nearly every unit on one obvious lot and let the policy follow a simple schedule. Here, space constraints and ordinary commercial leasing patterns often push inventory into a main sales location plus one or more supporting addresses, and that shifts the underwriting conversation toward where your highest concentration sits on a normal day and during a busy week.
In East Baton Rouge Parish, leading sectors by establishment share are professional, scientific, and technical services at 14.6%, retail trade at 13.8%, and health care and social assistance at 11.7%. Your neighbors are likely high-traffic commercial tenants, so access control, lot layout, and clear boundaries matter before you accept terms. Make sure each storage pattern is reflected in the quote, not just the customer-facing address.
Our Recommendation for Baton Rouge
Start with a current location schedule and treat it like an underwriting document, not an internal note. List every address where units are parked, even if one site is used only for overflow or only during a busy buying cycle, then match each site with its realistic peak inventory value, key control process, lighting, fencing, and who is authorized to move vehicles.
If your buyer profile depends on affordability, keep your inventory mix in view as well. Baton Rouge median household income is $49,944, so local shoppers tend to be payment-sensitive and dealers often carry a wider spread of lower-value units. That can make average inventory assumptions less reliable if a few higher-value vehicles arrive at the same time. Review maximum single-unit values and peak total lot values before renewal and before adding a new storage address. When something changes in the last quarter, bring the quote request current rather than relying on last term's schedule.
Get Dealer Open Lot Insurance in Baton Rouge
Enter your ZIP code to compare dealer open lot insurance rates from carriers in Baton Rouge, LA.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
You should plan to review any active storage address where vehicles are parked regularly. A back lot, overflow parcel, or service-area holding space can change how limits are applied, especially when inventory values are not evenly spread across locations.
Quotes typically stall when the address list, peak values, and actual parking pattern tell different stories. If units move between a sales lot and a secondary site, underwriters usually need that schedule clarified before they finalize terms.
East Baton Rouge Parish has 12,520 business establishments, so dealer lots here tend to sit in tighter commercial settings with shared access and neighboring tenants. That makes site details, lot boundaries, lighting, and controlled vehicle access more important in the quote review.
Dealers with changing inventory should be careful with averages alone. If a few higher-value units arrive together or one location carries a heavier concentration, your peak exposure can sit well above the monthly average and deserves a separate review.
With median household income at $49,944, local buyers tend to be payment-conscious, which can push dealers toward vehicles aimed at that budget. That can shift inventory mix and turnover patterns, so reviewing peak lot values and any temporary overflow storage before renewal is a smart move.
Quotes go faster when you submit a current inventory list, peak lot values, and every storage address at the start. If offsite storage or overflow parking is missing, the underwriter usually comes back with follow-up questions before terms are finalized. Having your key control procedures and security documentation ready at the same time can help prevent delays.
Assume each storage location needs to be reviewed if vehicles are kept there with any regularity. That includes overflow areas, service-area parking, and temporary holding sites, because location details often affect both terms and claim handling. An unlisted address where inventory sits overnight can become a coverage dispute after a loss.
The Louisiana Department of Insurance oversees insurer licensing, market conduct, and complaint resolution. You can reach them at ldil.la.gov or 1-800-259-5300 to verify carrier standing while you review policy terms and dealership documentation.
Sources
- 1.U.S. Census Bureau, County Business Patterns, East Baton Rouge Parish(East Baton Rouge Parish has 12,520 business establishments, so commercial property use is dense and shared, and that raises practical questions about fencing, lighting, neighboring tenants, and how clearly each storage area is identified on your submission.; In East Baton Rouge Parish, leading sectors by establishment share are professional, scientific, and technical services at 14.6%, retail trade at 13.8%, and health care and social assistance at 11.7%, so vehicle dealers often operate alongside other intensive commercial uses rather than on isolated standalone property.)
- 2.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Baton Rouge median household income is $49,944, so many local shoppers are payment-sensitive, and dealers sometimes carry a wider spread of lower-value units to meet that demand.)
Updated July 16, 2026