Updated July 16, 2026

Dealer Open Lot Insurance in Southaven
Property values and household buying power shape how you set lot limits here. With a Southaven median household income of $76,159, many dealers merchandise inventory for shoppers who expect late model vehicles, cleaner trim packages, and financeable price points. Underestimating your highest lot values can leave a bigger gap after a weather loss or theft event. Review your policy around your highest total inventory days, not your slowest week.
Dealer Open Lot Insurance Risk Factors in Southaven
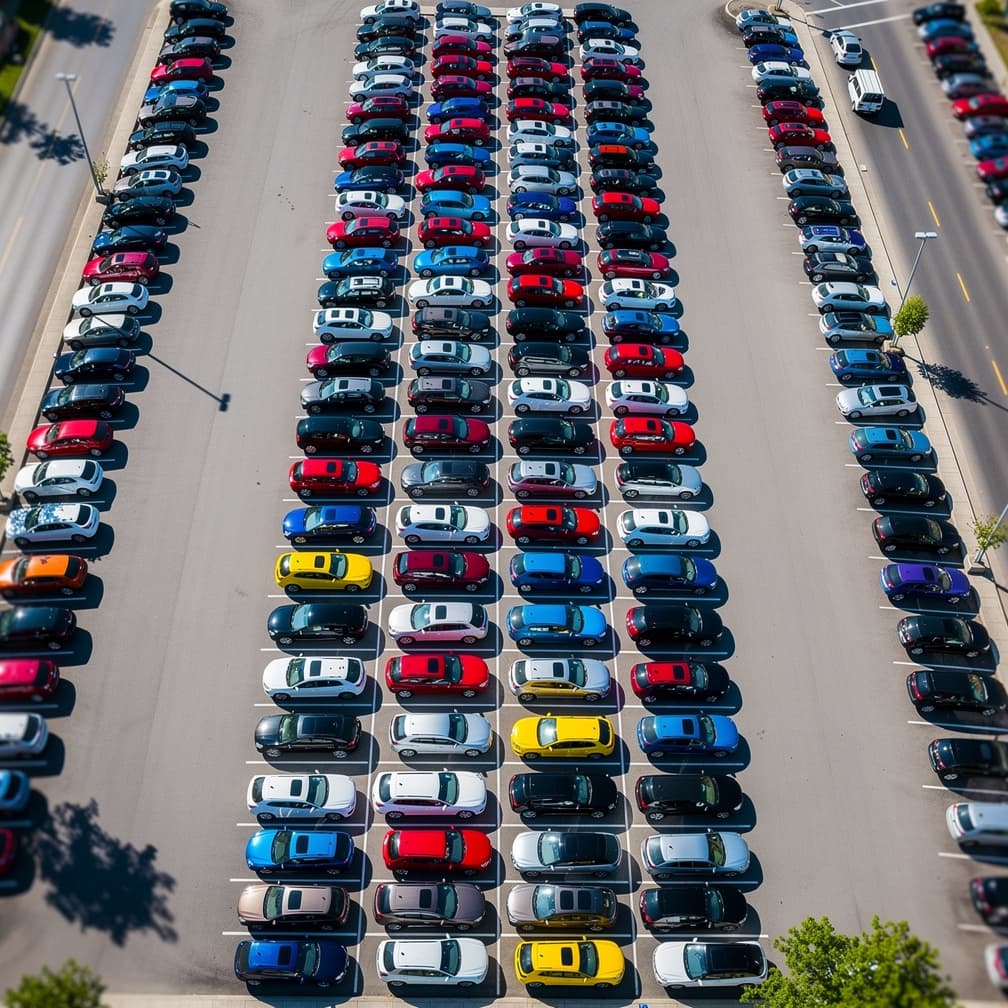
Southaven dealers are still buying protection for concentrated outdoor inventory, which means local weather planning matters most at the lot level. The city does not need a unique hazard statistic to change the buying decision here. What changes the calculus is how quickly a single event can affect many vehicles parked close together, especially if your inventory is stacked by value, body style, or reconditioning status. That makes layout and valuation discipline part of the insurance conversation. Review whether your highest value units sit in the most exposed rows, whether vehicles awaiting detail or repair are counted correctly, and whether temporary overflow spaces are included when inventory builds. If your operation moves units between the sales line, service area, and auxiliary parking during the week, ask how those locations are treated and what documentation helps support a claim.
Mississippi has a very high climate risk rating. Top hazards: Hurricane (Very High), Tornado (Very High), Flooding (High), Severe Storm (High). The state's expected annual loss from natural hazards is $1.8B, which influences dealer open lot insurance premiums and may affect coverage availability in high-risk areas.
What Dealer Open Lot Insurance Covers
The narrower question is where a loss can start, how quickly it can spread across multiple units, and whether your policy language follows the way your dealership actually stores and moves vehicles.
Start by reviewing how the policy treats vehicles at each location you use. A main lot may be scheduled clearly, while a back lot, repair yard, or borrowed overflow space creates a different documentation issue if it is not disclosed up front. If you attend local sales events, move units to detail shops, or store vehicles temporarily after purchase and before front-line placement, ask whether those situations fit within your covered handling activities or need separate attention.
Mississippi weather also changes the practical side of coverage review. Wind, hail, heavy rain, and storm-related debris can damage many units in one event, so deductible structure, valuation method, and any location-specific conditions deserve a line-by-line check. Theft and vandalism review should be just as concrete. Underwriters often want to know about fencing, lighting, camera placement, key control, and after-hours access because those details affect both pricing and claim defensibility.
A strong review also separates dealer open lot from garage liability, property, and inland movement exposures. If a vehicle is being test-driven, transported between addresses, or held offsite, confirm which policy responds first and what documentation you would need after a loss. That is where many dealers find the real coverage gap, not in the headline peril list, but in the handoff between one exposure and another.
Coverage Included
Weather Damage
Covers hail, wind, flood, and storm damage to lot inventory.
Theft Protection
Covers vehicles stolen from your lot.
Fire Damage
Covers fire and explosion damage to inventory vehicles.
Vandalism
Covers intentional damage to vehicles on your lot.
Test Drive Coverage
Covers vehicles during customer and employee test drives.
Transit Coverage
Covers vehicles being moved between lot locations.
Industries & Insurance Needs in Southaven
County commercial density is the local business fact that matters most. DeSoto County has 3,251 business establishments, so dealers here often operate in a fast-moving vendor environment where lenders, repair partners, sign installers, transport firms, and nearby commercial neighbors all increase day-to-day movement around the property. That does not automatically change the base rate, but it does change how often vehicles are repositioned, delivered, serviced, or stored outside the front line. The county mix also leans toward customer-facing sectors, with retail trade at 20.3%, accommodation and food services at 12.8%, and health care and social assistance at 9.9%, so visibility, access, and parking flow can matter more for a local lot than they would in a more isolated market. Use that reality when you review security practices, keys, fencing, camera placement, and any overflow arrangement that depends on nearby commercial space.
What Makes Southaven Different
Inventory concentration is the main difference here. In a market where household income supports stronger retail expectations, a relatively small change in unit mix can raise your total lot value faster than it appears from a street view. You may add newer trucks, better-equipped SUVs, or cleaner finance-ready sedans without feeling like the operation has changed much. But your coverage responds to the value exposed at one time, not just the number of spaces on the pavement. That is why a Southaven-area buyer should focus less on a generic per-car assumption and more on peak aggregate value, seasonal swings, and where vehicles sit during reconditioning or overflow periods. If your inventory quality has improved over the last year, ask for a fresh limit review before renewal rather than assuming last term's number still fits.
Our Recommendation for Southaven
Pull three numbers before you do anything else: your highest recent total inventory value, your normal weekly value, and the deductible you could absorb without disrupting cash flow. Comparing your worst day against your typical week shows whether your structure is ready for a real loss. Map every place a vehicle can sit during the week, including service lanes, detail areas, overflow parking, and any off-hours storage arrangement, and at the same time confirm how values are tracked when units are purchased, reconditioned, priced, and moved. If your mix has shifted toward higher-value inventory, your limit should rise before your next busy selling period. The Mississippi Insurance Department is your regulator reference point for policy questions, and bringing those questions into a quote review helps ensure the schedule, deductible, and reporting method match your actual operation.
Get Dealer Open Lot Insurance in Southaven
Enter your ZIP code to compare dealer open lot insurance rates from carriers in Southaven, MS.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
Southaven dealers should set limits around peak total inventory value, not a slow month snapshot. With median household income at $76,159, a shift toward newer or better-equipped units can raise your exposed value quickly, so review limits whenever your mix changes.
Southaven overflow parking can change the quote because vehicles may be stored, moved, or left in spaces outside the main display line. List every location you actually use, then ask how each area is treated before you bind coverage.
DeSoto County has 3,251 business establishments, meaning vendor traffic, deliveries, and vehicle movement around your property stay heavy throughout the week. That activity level makes security, key control, and lot layout worth a closer look during quoting.
Southaven sits in a county where retail trade accounts for 20.3% of establishments, accommodation and food services 12.8%, and health care and social assistance 9.9%. A customer-facing business base like this tends to bring more foot and vehicle traffic near your lot, which can affect access, parking flow, and overflow storage needs.
Southaven dealers should revisit deductibles whenever total lot value rises. A deductible that felt manageable with lower-value inventory may strain cash flow after a multi-vehicle loss, so compare out-of-pocket tolerance against your current peak exposure before renewing.
Often, yes. If sale units are stored away from the main lot, disclose that clearly during quoting so the policy addresses where inventory actually sits rather than assuming every vehicle stays at one primary address.
Policies may address storm-related damage, but the real question is how deductibles, valuation, and reporting apply when many units are hit in one event. Review those terms before binding so a lot-wide loss does not create an avoidable surprise.
The Mississippi Department of Insurance regulates policy forms, complaint procedures, and claim handling practices for the state. If a dispute arises over a claim or policy form, that is where you would file a complaint or seek resolution.
Sources
- 1.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Southaven median household income is $76,159.)
- 2.U.S. Census Bureau, County Business Patterns, DeSoto County(DeSoto County has 3,251 business establishments.; In DeSoto County, retail trade accounts for 20.3% of establishments, accommodation and food services 12.8%, and health care and social assistance 9.9%.)
- 3.Mississippi Insurance Department(Mississippi Insurance Department is the state's insurance regulator.)
Updated July 16, 2026