Updated July 16, 2026

On-Hook Towing Insurance in Bismarck
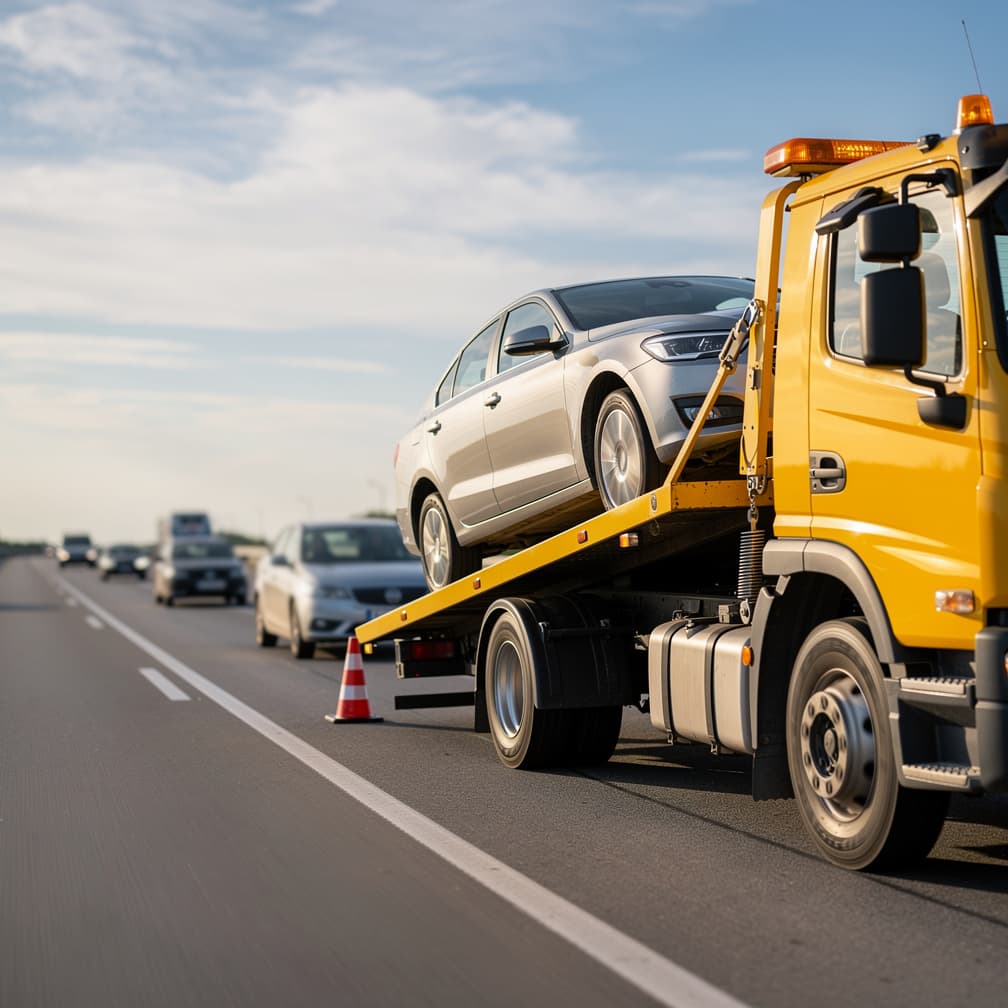
A loaded pickup slides while your operator is easing off a frontage road. The tie-downs hold, but the customer still wants to know whose policy responds to the damage that happened while the vehicle was in your care. That is the moment on-hook towing insurance in Bismarck gets tested. Your day might start with a routine local tow, shift to a retail parking lot call by midmorning, and end with a contractor equipment move across the county. Burleigh County has 3,201 business establishments, which translates to roughly one business for every 27 residents. That density means shop owners and fleet managers have plenty of vendor options and tend to demand proof of coverage before releasing a vehicle. List the vehicles you tow most often, the highest-value unit you might have on the hook, and whether you handle contractor pickups, vans, or customer cars for local businesses.
On-Hook Towing Insurance Risk Factors in Bismarck
Local exposure here comes from the variety of vehicles and job purposes you may take into custody in a single week, not just from distance. Burleigh County's establishment base supports retail, service, and contractor activity, which means a tow can start in a shopping area, at an apartment lot, behind a repair facility, or at a work site with tighter access and more room for loading mistakes. That matters for on-hook coverage because claim severity changes fast when the vehicle on your truck is a newer pickup, a work van with mounted equipment, or a customer unit that already has prior damage you need documented before transport. Review how your policy treats **loading and unloading incidents**, whether limits fit the most expensive vehicle you reasonably accept, and how your operation records pre-tow condition with photos and dispatch notes.
North Dakota has a high climate risk rating. Top hazards: Severe Storm (Very High), Flooding (High), Winter Storm (Very High), Tornado (High). The state's expected annual loss from natural hazards is $480M, which influences on-hook towing insurance premiums and may affect coverage availability in high-risk areas.
What On-Hook Towing Insurance Covers
In North Dakota, the difference is usually not the basic idea of on-hook coverage. It is the situations that make a claim more likely to be disputed or more expensive. If your drivers work winter roadside calls, ditch pull-outs, or long-distance tows between smaller communities, you should review how the policy responds to damage allegations tied to securement, shifting during transport, low-visibility loading, and unloading on snow-packed or uneven surfaces. For example, if your call volume shows a high number of ditch recoveries after storms, your policy should reflect that specific exposure rather than a generic towing label.
A practical review starts with your service mix. A flatbed moving disabled pickups on open highways presents a different exposure from a wheel-lift unit handling tight apartment impounds or post-accident recovery in poor weather. If you do both, ask for each activity to be described clearly in the submission so the quote is built around real operations instead of a simplified label. That can help avoid surprises if a claim happens during a type of tow that was never explained well at binding.
You should also look closely at territory, vehicle types, and handoff points. North Dakota jobs can involve long travel distances, remote pickup locations, and transfers at repair shops, storage lots, or law enforcement-directed destinations. Those operational details matter because a claim often turns on exactly when the vehicle was attached, how it was being moved, and who had care, custody, or control at that moment. The North Dakota Insurance Department reviews and approves policy forms and rate filings, which means the language in your endorsement and the premium you pay have gone through a state regulatory process. That review gives you a formal complaint avenue if a claim dispute arises, so keeping your policy forms, endorsements, and claim reporting process organized lets you act on it quickly before you put a truck back on the road.
Coverage Included
Collision on Hook
Covers damage to towed vehicles from collisions during transport.
Comprehensive on Hook
Covers theft, fire, and weather damage to vehicles being towed.
Loading & Unloading
Covers damage during the process of loading and unloading vehicles.
Winching Coverage
Covers damage to vehicles during winching and recovery operations.
Multiple Vehicle
Covers all vehicles on multi-car carriers and rollback flatbeds.
Industries & Insurance Needs in Bismarck
The county business mix is what changes demand around this product. In Burleigh County, leading sectors by establishment share are construction at 12.7%, retail trade at 12.2%, and other services, except public administration, at 11.7%, so local towing work often involves contractor pickups, customer vehicles at retail locations, and service-related calls where possession changes hands quickly. For an on-hook quote, that mix matters because the exposure is not only passenger cars. You may be asked to move work trucks, vans, or vehicles tied to a business interruption if they are damaged during transport. Ask for the quote to reflect the heaviest and highest-value units you will actually accept, whether you do private property impounds for commercial clients, and whether your paperwork distinguishes routine tows from more specialized commercial moves.
What Makes Bismarck Different
The vehicles on your hook directly shape your premium. A local tow company can end up handling a wider spread of customer-owned vehicles tied to stores, contractors, and service operators, often under vendor expectations that are more formal than a one-off roadside call. A limit that looks fine for a ten-year-old sedan may fall short once you are moving a loaded contractor pickup or a late-model work van, since replacement values and dispute potential both climb. If your dispatch board includes private property removals, shop-to-shop transfers, and commercial account work, ask for the quote to be built around those categories instead of a generic towing description.
Our Recommendation for Bismarck
Figure your real maximum exposure first, then work backward to a limit that makes sense for it. If you occasionally move contractor pickups, cargo vans, or newer business-use vehicles, consider setting your on-hook limit near the highest-value unit you are willing to accept, then confirm whether loading and unloading damage is handled the way you expect. From there, break your account types into separate categories. Retail property calls, dealer transfers, and contractor work each carry different risk profiles, and your application should spell out which ones make up most of your book. Bismarck has a median household income of $77,608, which is about 8 percent above the state median. Higher local incomes tend to mean newer vehicles on the road, which means a dented door on a late-model pickup can cost more to settle than the same damage on an older unit. That makes pre-tow photos and condition notes worth tightening up before renewal. When you compare options, give every insurer the same dispatch mix, vehicle types, and requested limit so you are comparing terms, not just price.
Get On-Hook Towing Insurance in Bismarck
Enter your ZIP code to compare on-hook towing insurance rates from carriers in Bismarck, ND.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
If your dispatch board includes business clients as well as individual drivers, your on-hook limit needs to account for higher-value work vehicles, not just standard passenger cars. A commercial account that hands you a $65,000 loaded service van creates a different exposure than a roadside call for a commuter sedan.
If private property work is a meaningful part of your dispatch mix, it belongs on the application in its own category. The way a vehicle is located, accessed, loaded, and released can differ from a routine roadside tow, and those details help an insurer evaluate on-hook exposure more accurately.
Construction, retail trade, and other services make up leading establishment shares in Burleigh County, at 12.7%, 12.2%, and 11.7% respectively. Those three sectors alone account for roughly one in three county businesses, which means your hook is more likely to carry contractor pickups and service vans than a typical passenger-car market would suggest.
Document pre-existing damage, wheel and tire condition, glass, body panels, and any cargo or mounted equipment visible before loading. Time-stamped photos and dispatch notes can make an on-hook claim easier to sort out if damage is alleged after delivery.
The North Dakota Insurance Department is available to policyholders if a coverage or claims handling issue cannot be resolved directly with the carrier. That does not replace careful policy review up front, especially around limits, exclusions, and how your towing operations are described. **Request a quote through CPK Insurance** to see what options may be available for your operation.
Yes. Icy loading areas, ditch pull-outs, and reduced visibility can change claim severity, so disclose that work up front. A quote is more dependable when the carrier understands whether you handle routine roadside tows, difficult recoveries, or both.
Compare quotes on matching operational details, not premium alone. Use the same truck list, service types, territory, and driver information for each submission, then review deductibles, exclusions, and how the policy describes your actual towing work.
It can. Longer distances, remote pickups, and highway speeds may increase the time and conditions under which a customer vehicle stays in your care. That is worth spelling out before you bind coverage.
Sources
- 1.U.S. Census Bureau, County Business Patterns, Burleigh County(Burleigh County has 3,201 business establishments, so you are often towing for fleets, job sites, stores, and service businesses that expect clear proof of coverage before they release a vehicle or sign a vendor agreement.; In Burleigh County, leading sectors by establishment share are construction at 12.7%, retail trade at 12.2%, and other services, except public administration, at 11.7%, so local towing work often involves contractor pickups, customer vehicles at retail locations, and service-related calls where possession changes hands quickly.)
- 2.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Bismarck also has a median household income of $77,608, so personal vehicles and light trucks on local calls may carry higher repair expectations than an older, low-value unit, which makes pre-tow photos and condition notes worth tightening up before renewal.)
- 3.North Dakota Insurance Department(Bismarck policyholders can use the North Dakota Insurance Department if a coverage or claims handling issue cannot be resolved directly.)
Updated July 16, 2026