Updated July 16, 2026

On-Hook Towing Insurance in West Valley City
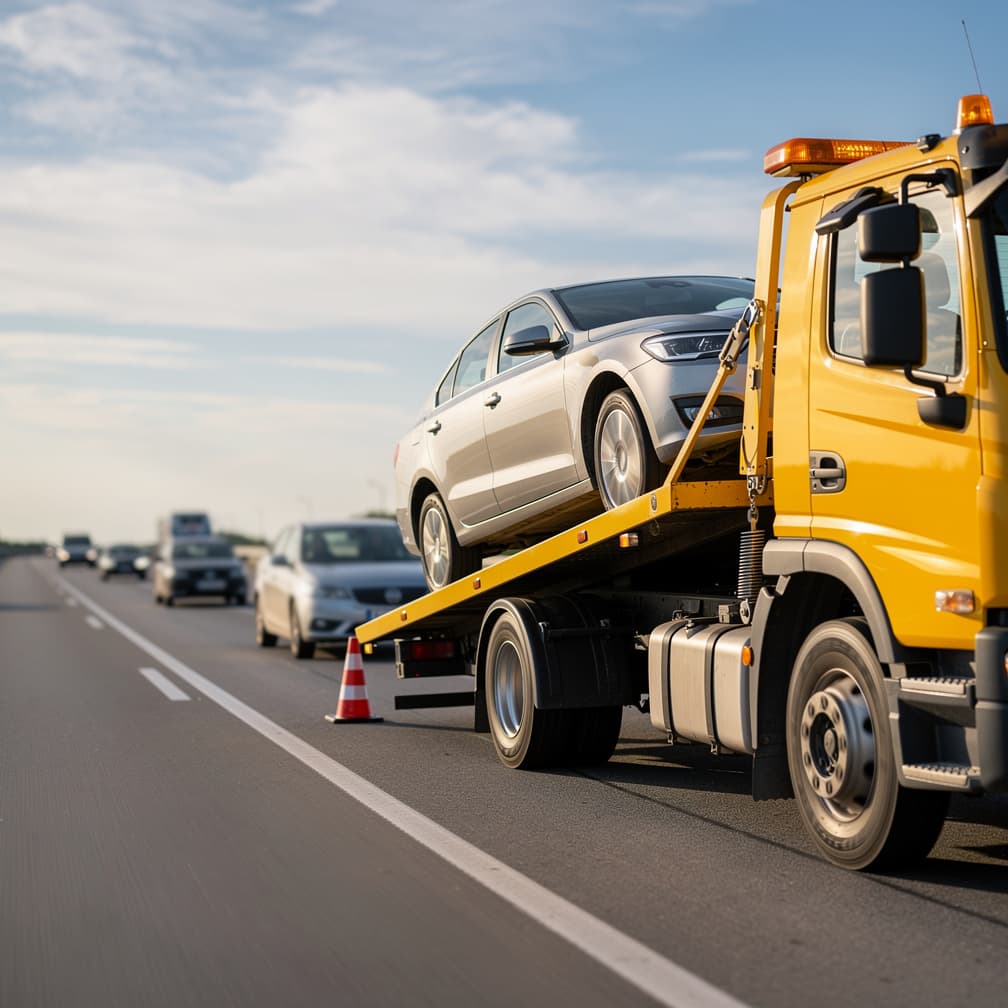
A local tow operator here often works out of a small yard or shared industrial space, runs short urban recoveries, and fields calls from apartment complexes, repair shops, and commercial lots across the valley. That operating pattern changes how you should review on-hook towing insurance in West Valley City. The question is not just whether a customer vehicle is attached to your truck, but what kinds of vehicles you move, how often you handle tight-lot impounds, and whether storage, winching, or multi-stop runs create handoff points where damage disputes start. West Valley City median household income is $88,604, which means many owners here rely on a financed daily driver. A vehicle that arrives with new damage or sits delayed in your yard can trigger a pressed claim fast. That makes documentation, condition photos, and clear on-hook limits worth reviewing before renewal. If your work mixes apartment enforcement, breakdown tows, and shop deliveries in the same week, your policy should separate those job types instead of assuming one flat exposure profile.
On-Hook Towing Insurance Risk Factors in West Valley City
West Valley City's top risk factors include Wildfire risk, Drought conditions, Power shutoffs, and Air quality events.
Utah has a moderate climate risk rating. Top hazards: Wildfire (High), Earthquake (High), Drought (Moderate), Winter Storm (Moderate). The state's expected annual loss from natural hazards is $320M, which influences on-hook towing insurance premiums and may affect coverage availability in high-risk areas.
What On-Hook Towing Insurance Covers
In Utah, the useful question is not the basic definition of on-hook coverage. It is where your operation creates the most claim pressure once a vehicle is in your custody during the tow. If your work includes steep grades, winter roadside calls, or recoveries where a disabled vehicle has to be repositioned before transport, you should ask how the policy responds to the exact handling steps your crews use. A wheel-lift account, a flatbed account, and a mixed fleet can produce very different damage scenarios, even if the same truck handles them on different days.
Your review should get specific about loading methods, tie-down procedures, dollies, winching practices, and whether higher-value vehicles show up in dealer work, specialty transport, or post-accident tows. If you subcontract overflow calls, confirm how responsibility is assigned when another operator touches the vehicle. If you store towed units before release, separate the on-hook discussion from garagekeepers or storage-related exposures so there is less confusion after a loss.
Utah weather and terrain can also change the way a routine tow turns into a disputed claim. A buyer should ask whether the policy language is broad enough for the kinds of roads, grades, and roadside conditions the business actually sees, rather than assuming every tow is underwritten the same way. It also helps to review exclusions tied to unattended vehicles, improper securement, mechanical breakdown, or pre-existing damage, because those are often the points that decide whether a claim is paid, limited, or denied. Before binding, ask for sample claim scenarios based on your real dispatch mix and compare the answers side by side.
Coverage Included
Collision on Hook
Covers damage to towed vehicles from collisions during transport.
Comprehensive on Hook
Covers theft, fire, and weather damage to vehicles being towed.
Loading & Unloading
Covers damage during the process of loading and unloading vehicles.
Winching Coverage
Covers damage to vehicles during winching and recovery operations.
Multiple Vehicle
Covers all vehicles on multi-car carriers and rollback flatbeds.
Industries & Insurance Needs in West Valley City
Salt Lake County business mix changes who calls you and what sits on your hook. The county has 35,284 business establishments, so a local towing account often depends on commercial relationships, not just public roadside calls. That means your on-hook review should account for vendor agreements, certificate requests, and the kinds of customer vehicles tied to business clients. The mix matters too: professional, scientific, and technical services represent 14.8% of county establishments, construction 11.6%, and health care and social assistance 10.5%. So you may be moving employee vehicles from office lots, pickups and vans tied to contractors, or personal autos connected to clinics and care facilities, each with different damage expectations and downtime pressure. If your book leans commercial, ask whether your limits still fit the highest-value vehicle you regularly tow under contract, not just the average private-party call.
What Makes West Valley City Different
When household vehicles, apartment enforcement, repair-shop transfers, and business-client calls all land on the same dispatch board, a policy review that treats every tow like the same exposure can leave gaps between what you actually hook and what underwriters think you move. A low-clearance car pulled from a crowded complex, a contractor pickup headed to a shop, or a vehicle moved for a commercial property account with strict paperwork requirements each carry different risks. Your quote should reflect that reality, built around job mix and handling steps rather than truck count alone. Maximum vehicle values, loading and unloading language, and claims documentation all deserve attention when a customer, property manager, and repair facility are involved in the same file.
Our Recommendation for West Valley City
Start by pulling your dispatch history from the last few months. Break it down by private-party tows, impounds, shop deliveries, dealer or fleet moves, and commercial property work so an underwriter sees your real exposure rather than a broad description like light-duty towing. Next, compare your highest regular vehicle value against your current on-hook limit. This matters especially if you pick up newer SUVs, work trucks, or financed daily drivers. Map out where damage allegations usually begin, whether during hookup, winching, transport, unloading, or storage handoff, and make sure your procedures and policy language line up. If you operate from a leased yard or shared space, confirm who is responsible for vehicles at each stage and what your contracts require before you issue certificates. When you are ready, request a free quote and send your truck schedule, service mix, and sample client agreements up front, because that is where local towing accounts usually get misclassified.
Get On-Hook Towing Insurance in West Valley City
Enter your ZIP code to compare on-hook towing insurance rates from carriers in West Valley City, UT.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
West Valley City operators should lead with job mix, vehicle types, and whether they handle apartment impounds, shop transfers, or commercial accounts. That gives the underwriter a picture of how damage allegations actually arise during hookup, transport, unloading, and handoff.
West Valley City private-lot work can change how you review limits and documentation because tight spaces, quick removals, and disputed vehicle condition create more room for damage arguments. Check your policy terms for how loading, unloading, and post-tow handoff are handled.
Salt Lake County has 35,284 business establishments, which means your steady clients are likely to be vendors, property managers, shops, and fleets rather than one-off public calls. Review certificate requirements and the highest-value vehicles you tow under contract before renewing.
Salt Lake County business mix includes professional services at 14.8%, construction at 11.6%, and health care and social assistance at 10.5%, so expect office-lot vehicles, contractor pickups, and service vans on your hook. Your on-hook limit should fit that real commercial call mix.
West Valley City median household income is $88,604. For many customers, a financed everyday vehicle is the only way to get to work, and any new damage allegation or delay can escalate quickly. Strong intake photos, condition notes, and clear release procedures become more important.
Many operators carry it for private property impounds because the risk starts once a vehicle is attached, loaded, or moved by your truck. Contract terms and claim expectations can differ by account, so compare your impound work against your other towing services.
Mountain routes and winter weather can make a routine tow more complex by changing loading angles, roadside space, and securement demands. That is why you should ask how the policy handles the exact recovery, winching, and transport steps your drivers use in difficult terrain or weather.
Insurance oversight runs through the Utah Insurance Department, so that is the regulator behind policy forms, licensing questions, and complaint handling. For a buyer, the practical step is to get terms in writing and review exclusions.
Sources
- 1.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(West Valley City median household income is $88,604)
- 2.U.S. Census Bureau, County Business Patterns, Salt Lake County(Salt Lake County has 35,284 business establishments; Salt Lake County business mix includes professional, scientific, and technical services at 14.8%, construction at 11.6%, and health care and social assistance at 10.5%)
Updated July 16, 2026