

































Updated July 16, 2026

Recommended Coverage for Wholesalers & Distributors in Burlington, VT
Wholesalers & Distributors businesses face unique risks that require specific coverage types. Here are the policies most wholesalers & distributors operations need:

General Liability
Essential coverage for every business, protect against third-party bodily injury, property damage, and advertising claims.

Commercial Property
Safeguard your business property, equipment, and inventory against damage and loss.

Commercial Auto
Protect your business vehicles and drivers with comprehensive commercial auto coverage.

Commercial Truck
Comprehensive coverage for trucking operations, from long-haul rigs to local delivery vehicles.

Inland Marine
Protect tools, equipment, and goods in transit or stored at locations away from your primary premises.

Workers Compensation
Help cover your employees' medical expenses and lost wages for work-related injuries and illnesses.
Wholesalers & Distributors Insurance Overview in Burlington, VT
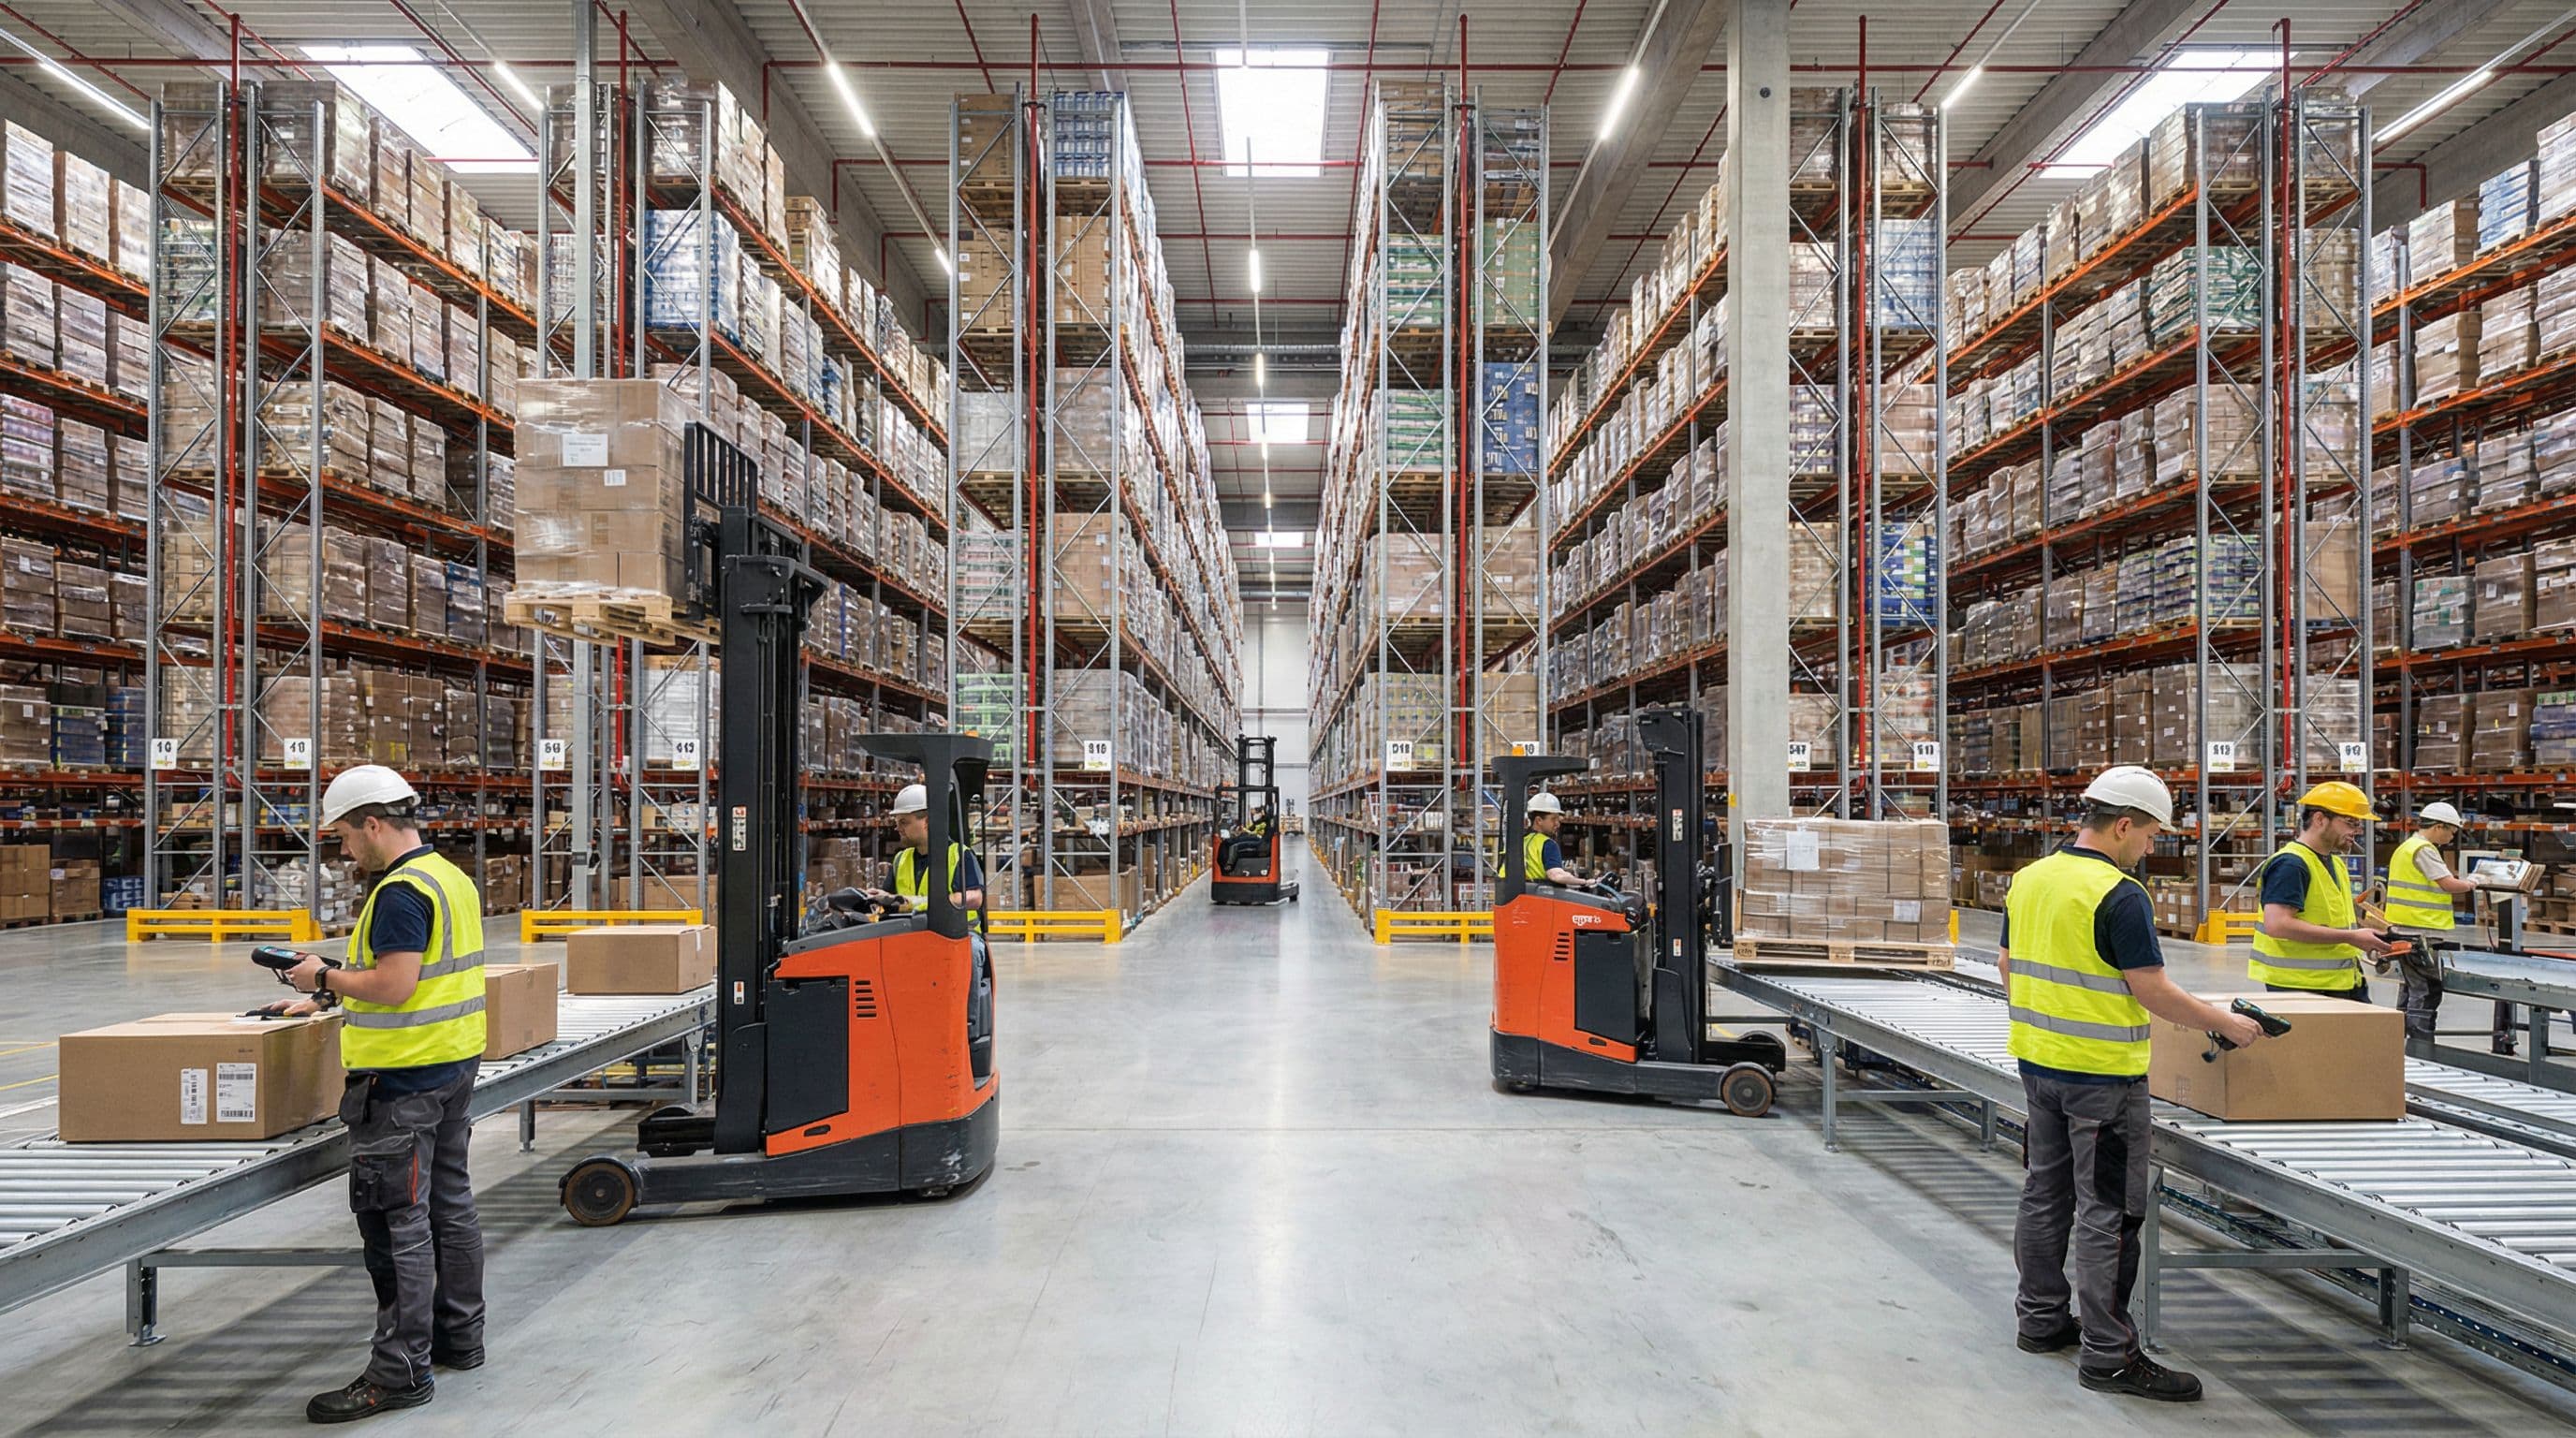
Running a wholesale or distribution operation in Burlington means moving goods through warehouse corridors, loading docks, and delivery routes that serve healthcare, retail, manufacturing, education, and food service customers. Those buyers expect fast, reliable deliveries and consistent stock levels. Your policy should be built around how inventory is stored, handled, and shipped, not just the square footage of your building. Burlington's local conditions add real pressure. A crime index of 69 puts this area in a higher-risk category for theft, which means your security measures and coverage limits matter more than they might in a quieter market. The city also has a 9% flood zone share, so a warehouse in the wrong spot could face water damage you have not planned for. Severe cold-weather damage is among the top risks that make a tailored package necessary. If you rely on fleet vehicles or move high-turnover inventory, a well-structured policy can help you prepare for disruptions that affect stock, transit, and operations.
Why Wholesalers & Distributors Businesses Need Insurance in Burlington, VT
Wholesalers and distributors in Burlington often work in tight timing windows, with goods arriving, repacked, and sent back out to customers across the city and nearby markets. That pace creates exposure to property damage, theft, liability, and business interruption if a winter storm closes warehouse access or a delivery delay interrupts supply flow. With a crime index that high, theft prevention belongs in your operational plan from day one. The flood zone share means a single flooded storage room could ruin thousands in unsold inventory. Many distributors support time-sensitive customers across healthcare, retail, manufacturing, food service, and education, and those buyers cannot wait long for replacements. That makes your property, liability, and inland marine coverage especially relevant when stock is moving between the warehouse, the dock, and the customer.
Vermont requires workers' comp for businesses with employees (exemptions may apply: Sole proprietors; Partners). Non-compliance can result in fines and personal liability for owners. Commercial auto minimums are $25,000/$50,000/$10,000.
Key Risks for Wholesalers & Distributors Businesses
Each of these risks can lead to claims that cost thousands, or more. Make sure your policy addresses every one:
- Inventory damage or spoilage
- Cargo theft during transit
- Warehouse fire or natural disaster
- Fleet vehicle accidents
- Product liability claims
What Drives Wholesalers & Distributors Insurance Costs in Burlington, VT
Your insurance cost in Burlington varies based on the size of the warehouse, the value of stored inventory, the number of delivery trucks, and how often goods move in and out of the building. Pricing can also shift with vehicle use, storage controls, and whether your operation needs vehicle, transit, or stock coverage. Businesses with more customer contact or higher third-party claims exposure may see different pricing than a warehouse-only operation. For a quote, the most useful starting point is a clear summary of your locations, inventory values, fleet vehicles, and delivery patterns.
Wholesalers & Distributors businesses typically carry several separately priced policies. The ranges below are typical figures for Burlington for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $90 - $400 per month | Industry and risk classification, annual revenue, number of employees |
| Commercial Property Insurance | $220 - $1,075 per month | Building value and construction type, roof age and condition, fire protection class |
| Commercial Auto Insurance | $210 - $650 per month | Fleet size and vehicle types, driver records and experience, coverage limits and deductibles |
| Commercial Truck Insurance | $270 - $875 per month | Radius of operation, commodities hauled and cargo value, number and value of power units |
| Inland Marine Insurance | $55 - $290 per month | Total insured value of the scheduled property, type and age of the equipment, where it is stored and how far it travels |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
State Requirements
Insurance Regulations in Vermont
Key regulatory requirements for businesses operating in VT.
Regulatory Authority
Workers' Compensation InsuranceRequired
Required for employers with 1+ employee.
Exempt categories
- Sole proprietors
- Partners
- Corporate officers
Commercial Auto Minimum Liability
$25,000/$50,000/$10,000 (bodily injury per person / per accident / property damage)
Source: Vermont Department of Insurance, U.S. Department of Labor
Climate Risk Profile
Natural Disaster Risk in Vermont
Understanding climate-related risks helps determine appropriate insurance coverage levels.
Winter Storm
High
Flooding
High
Nor'easter
Moderate
Landslide
Low
Expected Annual Loss from Natural Hazards
$120M
estimated economic loss per year across Vermont
Source: FEMA National Risk Index
Insurance Tips for Wholesalers & Distributors Business Owners in Burlington, VT
Your property coverage should reflect the actual warehouse layout, dock area, and any storage rooms that hold high-value stock in Burlington.
Transit coverage may be worth adding if goods move between Burlington, South Burlington, Rutland, or other delivery points before reaching customers.
Liability coverage matters most where customer or vendor foot traffic overlaps with loading areas, pickups, or site visits.
If your business uses delivery trucks or service vehicles, compare vehicle options based on how the fleet is used.
Check whether your policy structure addresses cold-weather damage at the warehouse.
Ask how workers compensation fits the physical demands of warehouse work, including lifting, staging, and loading.
Get Wholesalers & Distributors Insurance in Burlington, VT
Enter your ZIP code to compare wholesalers & distributors insurance rates from top carriers.
Business insurance starting at $25/mo
Wholesalers & Distributors Business Types in Burlington, VT
Find insurance tailored to your specific wholesalers & distributors business. Select your business type for coverage recommendations, pricing, and quotes:

Freight Broker Insurance
Get a freight broker insurance quote built for brokerage and logistics operations that need protection when carrier policies do not fully pay a claim. Coverage can be tailored around contingent cargo, E&O, cyber, and crime needs.

Trucking Company Insurance
Get a trucking company insurance quote built around your routes, vehicles, and cargo. Compare coverage for fleets and owner-operators, including commercial auto, cargo, and liability.

Courier & Delivery Service Insurance
Get coverage built for courier operations that face vehicle accidents, package loss, and commercial auto requirements. Compare options for single vehicles, fleets, and local delivery routes.

Warehouse Insurance
Get a warehouse insurance quote built around inventory value, equipment exposure, and premises risks. Coverage can be tailored for warehouses and fulfillment centers.

Import & Export Business Insurance
Import and export business insurance can help wholesalers and distributors with cargo loss, goods in transit, and liability gaps across the supply chain. Get a quote tailored to your routes, shipment types, and trade operations.
FAQ
Wholesalers & Distributors Insurance FAQ in Burlington, VT
Most Burlington operations start by looking at general liability, commercial property, inland marine, and workers compensation. The right mix depends on the daily realities of how your operation runs.
Have ready your warehouse address, annual inventory values, number of delivery trucks, storage and loading details, and whether goods move through Burlington only or to nearby markets as well. That helps build a quote around your actual operations instead of a generic setup.
Cost is driven by inventory value, building size, vehicle use, claims history, and local exposure to cold-weather damage. The flood zone share and crime index can also influence how a carrier views risk, which means a warehouse in a flood-prone area or a high-theft zone may carry a higher premium than one in a lower-risk location.
If your stock moves between the warehouse, trucks, and customer locations, inland marine coverage is often an important part of your policy. It can help protect goods that are most vulnerable while in transit or staged for delivery.
You may need both auto and truck coverage, depending on the vehicle types and how they are used. A quote can be built around your fleet and the routes it travels.
Six policies cover the standard footprint: general liability, commercial property, commercial auto, commercial truck, inland marine, and workers compensation. Whether you mainly store stock, run deliveries, use heavier vehicles, or move goods through several locations decides which of them carries the load.
Generally not once it leaves the insured location, which is the point of the question. Property forms center on scheduled premises, so goods in transit or temporary storage belong in the inland marine review, especially if drivers move product daily or shipments stage before customer acceptance.
Vehicle size and use decide it. Commercial auto fits lighter delivery units, while commercial truck coverage addresses heavier vehicles, broader hauling exposure, and more demanding route and cargo operations. A mixed fleet can need both, scheduled accurately.