Updated July 5, 2026

Dealer Open Lot Insurance in Seattle
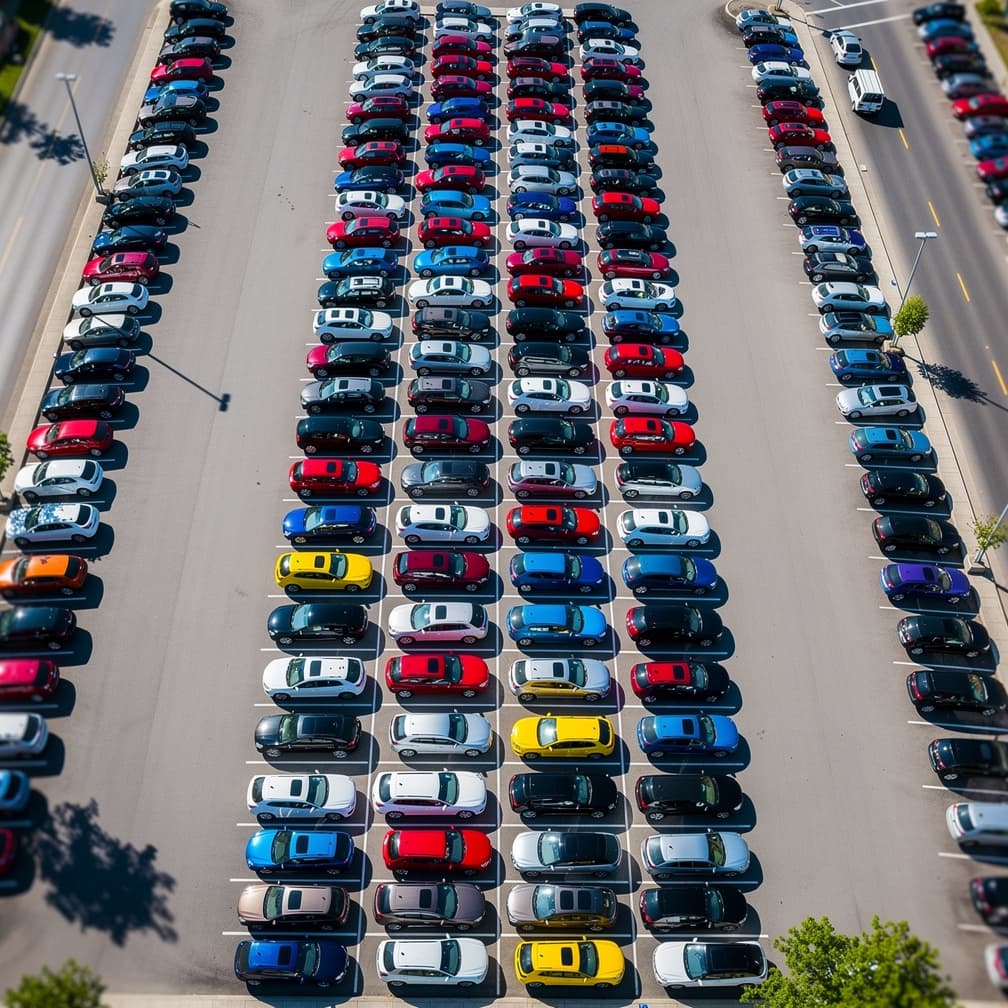
King County supports 70,530 business establishments, so local buyers, lenders, landlords, and vendor partners often expect clean certificates, clear schedules, and fast documentation before inventory moves or a deal closes. For a dealership, that density raises the bar on how you present your operation to underwriters. Dealer open lot insurance in Seattle usually gets a closer look when units rotate between a primary lot, overflow parking, service areas, and short term offsite storage tied to reconditioning or delivery timing. You are not just insuring parked vehicles here. You are showing how inventory is secured, where keys are controlled, how values peak during buying cycles, and whether every location is reported the same way on the application, floorplan records, and internal lot list. In a market with this much commercial activity, small documentation gaps can slow binding or create avoidable questions after a loss. Before you request terms, line up a current inventory schedule, addresses for every place units sit overnight, and a simple description of fencing, lighting, cameras, and key procedures.
Dealer Open Lot Insurance Risk Factors in Seattle
Seattle puts more pressure on **storage discipline** than on any single headline peril. Lots here are often tighter, more visible to passing traffic, and more dependent on overflow arrangements when inventory turns quickly, so a dealer open lot submission works better when it shows exactly where vehicles are kept after hours and who controls movement between locations. If units spend part of the week at a detail shop, service facility, port related staging area, or borrowed overflow space, note that up front instead of assuming the underwriter will treat every address the same. The practical issue is concentration and supervision at each site. You should review lighting, fencing, camera coverage, gate access, key storage, and how often staff physically verify counts. If your operation uses more than one storage pattern during the month, ask for terms that match that real workflow before inventory peaks.
Washington has a moderate climate risk rating. Top hazards: Earthquake (Very High), Wildfire (High), Volcanic Activity (High), Flooding (Moderate). The state's expected annual loss from natural hazards is $1.8B, which influences dealer open lot insurance premiums and may affect coverage availability in high-risk areas.
What Dealer Open Lot Insurance Covers
If you keep vehicles in low-lying paved areas, near drainage channels, under trees, or in overflow spaces with lighter fencing and lighting, you should review how the policy responds to those specific storage conditions rather than assuming every unit on every lot is treated the same way. The practical question is which vehicles are insured at which location, during what type of movement, and subject to what exclusions or sublimits.
For many dealers, the most important coverage review points are tied to operational handling. That includes units moved between your main lot and overflow storage, vehicles staged for detailing or service, and inventory taken off premises for auction, transport, or customer demonstration. If your operation uses multiple addresses, ask whether each location must be scheduled and how newly acquired units are treated before they are added to your reporting. That matters when inventory turns quickly or when you buy several vehicles at once.
Washington weather and catastrophe exposure also make wording review more important. Ask how the form handles wind-driven debris, falling objects, water damage, and losses that happen while units are temporarily stored away from the primary lot. If your dealership carries higher-value or specialty inventory, confirm whether valuation, accessories, charging equipment, or attached components create any special conditions.
Coverage Included
Weather Damage
Covers hail, wind, flood, and storm damage to lot inventory.
Theft Protection
Covers vehicles stolen from your lot.
Fire Damage
Covers fire and explosion damage to inventory vehicles.
Vandalism
Covers intentional damage to vehicles on your lot.
Test Drive Coverage
Covers vehicles during customer and employee test drives.
Transit Coverage
Covers vehicles being moved between lot locations.
What Makes Seattle Different
Density is the difference here. In a large county business market, underwriters expect a dealership to operate with tighter controls because inventory often sits near other commercial uses, shared access points, and multiple service partners. That changes the buying calculus. A basic statement that vehicles are stored on the lot is usually less helpful than a location by location explanation of where units are parked, when they move, and what security standards apply at each address. If your dealership relies on overflow parking or temporary staging, ask the quoting broker to present that operational map clearly. The goal is not more paperwork for its own sake. It is to reduce ambiguity before a theft, vandalism, or multi unit loss turns a vague storage description into a coverage dispute.
Our Recommendation for Seattle
Start with your storage map, not your last policy. For this market, build a quote request that shows every address where vehicles stay overnight, the highest expected inventory values by location, and the controls that apply at each site. If you use third party reconditioning, transport staging, or shared overflow space, say so early and confirm whether those locations need to be scheduled. Keep your floorplan reporting, inventory list, and insurance application aligned, because mismatched counts or addresses can create avoidable underwriting questions. It also helps to separate customer vehicles, owned inventory, and units awaiting sale if they are parked in different areas. If your operation changes seasonally, ask the broker to review peak inventory periods rather than quoting from an average month that understates exposure. Before binding, read the location schedule and any protective safeguard language line by line, then correct anything that does not match how your lot actually runs.
Get Dealer Open Lot Insurance in Seattle
Enter your ZIP code to compare dealer open lot insurance rates from carriers in Seattle, WA.
Business insurance starting at $25/mo
FAQ
Frequently Asked Questions
Seattle dealerships usually should review every place vehicles stay overnight, especially overflow or temporary storage addresses. A local submission is stronger when the location schedule matches how inventory actually moves, because unscheduled sites can create underwriting questions after a loss.
Seattle underwriters often want more detail because dense commercial areas can mean tighter lots, more vehicle movement, and more third party access points. You should be ready to describe fencing, lighting, cameras, gate controls, and key procedures by location.
King County business density often means a Seattle dealership faces higher expectations for organized documentation and fast proof of coverage. Clean schedules, accurate addresses, and consistent inventory records can help move a quote toward bindable terms.
Seattle's median household income is $121,984, so some dealers may carry higher value units or a mix that changes faster. That makes it worth reviewing peak inventory values and reporting methods before you request dealer open lot terms.
If inventory is kept on overflow parcels, satellite lots, or temporary storage sites, ask whether each address must be scheduled so a claim does not turn on where a vehicle spent the night.
If your lot has drainage issues, tree exposure, or concentrated outdoor storage, ask how the policy treats water damage, falling objects, and losses involving multiple units at one location.
Washington dealers often can insure offsite inventory, but the answer depends on how the policy schedules locations and movement between them. Provide every site where vehicles are kept up front and ask how temporary holding, service storage, and overflow parking are treated.
Washington uses the Washington Office of the Insurance Commissioner as the state's insurance regulator. If you need consumer guidance while reviewing policy language, complaints, or insurer conduct, that is the main state reference point to keep handy.
Sources
- 1.U.S. Census Bureau, County Business Patterns, King County(King County has 70,530 business establishments.)
- 2.U.S. Census Bureau, ACS 5-Year Estimates, table B19013(Seattle's median household income is $121,984.)
Updated July 5, 2026