

As a towing company in Salinas, you take custody of other people's property several times a day and hand it back without a scratch, or you do not. That custody is the whole insurance question. The moment a car rolls onto your deck you are responsible for it in a way a body shop or a parking garage would recognize, and towing company insurance in Salinas is built for that responsibility. Your own truck is the easy part to insure and the expensive part to replace. The customer's vehicle is the cheap part to insure and the loud part to argue about. Release forms and intake photos decide which way those arguments go. Compare quotes with a clear count of how many vehicles you touch in a week, because that number is what a carrier is really pricing.
What Makes Salinas Different
Municipal rotation lists are the backbone of a small towing operation, and they run on paperwork. Getting on one usually means showing proof of coverage at limits somebody else picked for you. Staying on one means never letting that proof lapse, which is a calendar problem more than a money problem. Where a rotation list is short, losing your slot costs a real share of the year's revenue. Requirements vary by state and by the office that keeps the list, so read yours closely. The California Department of Insurance publishes consumer guidance on commercial policy basics if the wording gets confusing. Ask for the exact endorsement names before you shop, because generic quotes rarely match a list's terms. A quote that misses one required endorsement is not cheaper; it is just wrong for Salinas work.
Local Risk Factors in Salinas
A closed road during a fire stops your trucks and does nothing to your costs. Crews work long shifts hauling vehicles out of Salinas while the routes back to the yard change hour by hour. Fire damage to your own trucks may fall under physical damage on the auto policy, but revenue lost to a week of closures generally needs a trigger that a closure never provides. That gap is worth knowing before the smoke arrives rather than during it. Cash reserves carry the difference, and in this trade the difference runs bigger than owners plan for, because the trucks cost money whether or not they can reach a highway in Monterey County.
What Coverage Does a Towing Company in Salinas Need?
Commercial Auto
Lenders holding a note on a wrecker generally require this line before the truck turns a wheel, and it is the largest piece of most towing bills. It can respond to injury and property damage your driver causes on the road, and to the truck itself where you add physical damage. The customer's vehicle riding behind it is not included here.
Example: A rollback merges onto a busy highway, clips a sedan, and both end up against the barrier; commercial auto may answer for the other driver's injuries and repairs, subject to your limits.
Garage Keepers
Every car left in your yard overnight belongs to someone who expects it back in the same condition. This line is built for damage to those vehicles while they sit in your custody, from theft and vandalism to fire and storm. Some forms respond only where you are legally liable, and others respond regardless of fault. It does nothing for your own trucks.
Example: A storm drops a limb across two customer cars parked in a Salinas storage lot; garage keepers can help cover the damage, depending on whether the form turns on fault.
On-Hook Towing
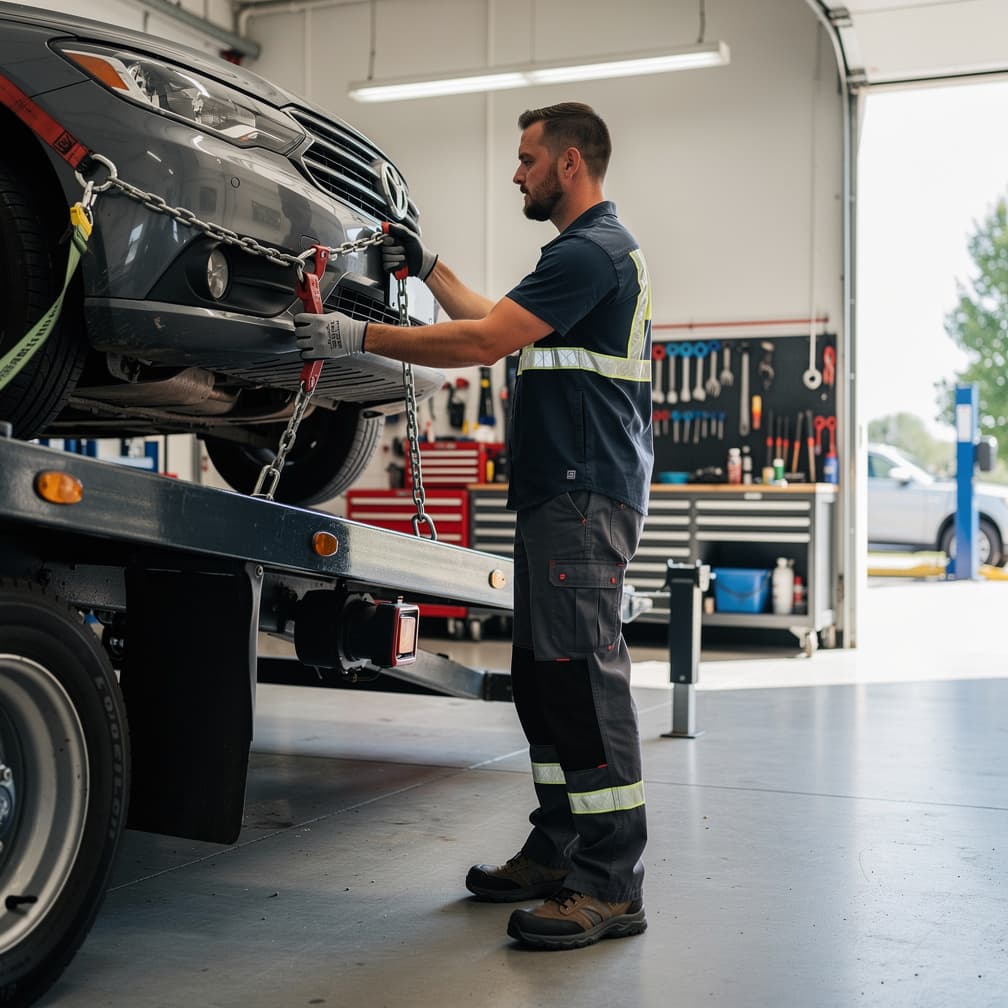
Damage you cause to a vehicle while it rides on your hook is not part of your own auto physical damage, and it is not part of a yard policy either. This line sits in that gap: loading, transport, unloading. Limits are usually set per vehicle, so the number should match the most expensive car you would accept. Workmanship errors are commonly excluded.
Example: A pickup's front bumper tears loose when a chain shifts during transport and the owner sends over a repair estimate; on-hook towing might respond to damage that happened in transit.
General Liability
Where the auto lines follow your trucks and the yard lines follow your customers' cars, this one follows people. Landlords and commercial accounts commonly require it before you get a key or an account. It might help cover a visitor injured at the release window, or property you damage away from a vehicle. Injuries to your own crew belong somewhere else.
Example: Someone slips on spilled fluid while collecting a car at your office and breaks a wrist; general liability is typically where that medical bill and any lawsuit get handled.
Workers Compensation
A driver hurt on a shoulder at night is the claim this line exists for, and health plans generally exclude injuries that happen at work. It is rated per hundred dollars of payroll by classification, so how you report an owner who also drives matters at audit. Requirements and part-time thresholds vary by state.
Example: A winch cable snaps during a recovery and catches an operator's hand in Salinas; workers compensation is generally the line that picks up the treatment and the lost wages.
How Much Does Towing Company Insurance Cost in Salinas?
Towing Company Insurance is a bundle of separate policies, priced separately. The ranges below are typical figures for Salinas for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| Commercial Auto Insurance | $1,350 - $4,600 per month | Fleet size and vehicle types, driver records and experience, coverage limits and deductibles |
| Garage Keepers Insurance | Varies | Quoted individually based on your operations and limits |
| On-Hook Towing Insurance | Varies | Quoted individually based on your operations and limits |
| General Liability Insurance | $160 - $600 per month | Industry and risk classification, annual revenue, number of employees |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
What Are the Insurance Requirements for a Towing Company in Salinas?
Workers' comp is generally required once you have your first employee. California generally requires employers to carry workers' compensation at that point. Common exemptions include sole proprietors and some partners. Confirm current thresholds with your state's workers' compensation agency before you hire.
State auto liability minimums apply to business vehicles. California's minimum auto liability limits are $30,000/$60,000/$15,000 (bodily injury per person / per accident / property damage). Contracts and lenders often require more than the state floor.
Where to verify licensing and coverage rules. The California Department of Insurance publishes consumer guidance and current insurance requirements for California businesses. When a contract or lease demands specific wording, the California Department of Insurance's guidance is the authoritative place to check.
Get Your Towing Company Quote in Salinas
Compare rates from multiple carriers. Free quotes, no obligation.
Operating in Salinas
- A property manager in Salinas can pull your certificate before approving an invoice, so a policy that lapses on the first of the month can freeze payment for work you already finished.
- Motor club contracts often set response times in minutes, and the driver who beats the clock is the driver who eventually rear-ends someone at a light.
- Cars pile up in a storage yard faster than owners retrieve them, and the value parked behind your Salinas fence on a busy weekend is rarely the number written on your application.
- Every vehicle you accept becomes somebody else's property in your hands the moment it touches the deck, which is why intake photos are worth more than any argument you can make later.
How to Buy: Advice for Salinas Owners
Payroll is the number to get right first if you have employees. Workers Compensation is quoted per hundred dollars of payroll and rated by classification, so an owner who dispatches, drives, and turns wrenches sits in more than one bucket. Track hours by task, not by title, and the audit becomes a short conversation instead of a surprise bill. If you use occasional help during storm weeks, ask how temporary drivers get reported before you hire them. General Liability quotes often ask for revenue at the same time, so pull both figures at once. The California Department of Insurance publishes consumer guidance on workers compensation basics for small employers. Then compare quotes from participating carriers across Salinas using the same payroll and revenue on every application.
FAQ
Towing Company Insurance in Salinas: FAQ
Usually one occurrence, and that is the number that matters. Your per-occurrence limit stands behind a single event no matter how many cars and people it involves, while the aggregate is the ceiling across the whole policy term. A recovery gone wrong on a busy Salinas road can put several vehicles and several injured people inside one event. Towing tests the per-occurrence figure hardest; the aggregate starts to matter after your second bad month in a year.
It depends on how the damage happened. Dragging a vehicle in gear or hooking it wrong is workmanship, and policies commonly exclude damage caused by the way work was performed. Accidental damage during transport is a different question, and On-Hook Towing may respond there. Training and a written hookup procedure are the least expensive fix, since this is one of the most argued claims in the trade.
Usually less than the auto line. General Liability is priced mainly on revenue and on the exposure at your office and yard, so a one-truck operation with a small lot tends to land near the bottom of the published range. The cost table on this page shows where that range currently sits. What moves it: revenue, claims history, and the limits your contracts demand.
A list of trucks with values, a driver list with license numbers, three years of loss runs, your annual payroll, your revenue, and the radius you truly run. Add a count of vehicles stored on a peak night if you keep a lot. Quotes built on guesses get corrected later, usually upward. Sending the same package to every carrier is what makes Salinas quotes comparable at all.
Usually not on a standard form. Flood is commonly excluded and priced as its own coverage, whether the water reaches your building or the vehicles parked around it. That gap matters more in towing than in most trades, because your yard sits outside by design and it is full of other people's property. Ask what a quote says about rising water before a storm week answers the question for you.
Yes, and it happens more than owners expect. A dispute over damage or missing property can surface weeks after a car leaves a Salinas yard, and your defense is the intake photos and the signed condition report you took at the time. Liability coverage may respond to the claim and to defense costs, subject to your limits and deductible. Memory is not evidence; the file is.
Sources
- 1.California Department of Insurance(California Department of Insurance publishes consumer guidance for insurance buyers.)


