
Average Roofer Insurance Costs
Roofing is one of the most expensive trades to insure due to the inherent dangers of working at height and the potential for significant property damage. Most small businesses see general liability insurance around $33 to $125 per month; roofers sit far above that baseline because of height risk, commonly about $210 to $670 per month ($2,500 to $8,000 per year) for a policy with $1 million per occurrence limits. Some roofers in high-risk markets or with unfavorable claims histories pay even more.
Workers' compensation insurance is by far the largest insurance expense for roofing companies. Roofing consistently ranks among the most dangerous occupations in America, with fall-from-height injuries being the leading cause of construction fatalities. Most business classes pay about $0.75 to $2.74 per $100 of payroll for workers' comp, but rates for roofing class codes typically run about $15 to $45 per $100 of payroll, making roofing one of the highest-rated classifications in the workers' compensation system. At those rates, a roofing company with $300,000 in annual payroll could pay about $45,000 to $135,000 per year for workers' comp alone.
Commercial auto insurance adds another $1,500 to $4,000 per vehicle. Inland marine coverage for tools and equipment on job sites typically costs $500 to $2,000 per year. A comprehensive insurance package for a small roofing company with a few employees can easily total $50,000 to $100,000 or more annually, making insurance one of the largest operating expenses in the roofing business.
Roofing Insurance is a bundle of separate policies, priced separately. The ranges below are typical figures nationally for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $390 - $1,250 per month | Industry and risk classification, annual revenue, number of employees |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
| Commercial Auto Insurance | $350 - $1,100 per month | Fleet size and vehicle types, driver records and experience, coverage limits and deductibles |
| Inland Marine Insurance | $45 - $210 per month | Total insured value of the scheduled property, type and age of the equipment, where it is stored and how far it travels |
| Commercial Umbrella Insurance | $130 - $500 per month | Umbrella limit requested, limits carried on the underlying policies, loss history on those underlying policies |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
Why Roofer Insurance Is So Expensive
The primary driver of high roofing insurance costs is the severity of potential claims. Falls from roofs can result in catastrophic injuries including spinal cord damage, traumatic brain injuries, and death. These injuries generate workers' compensation claims that can cost hundreds of thousands to millions of dollars in medical treatment, long-term disability benefits, and death benefits. The high severity of roofing claims pushes workers' comp rates far above most other trades.
General liability rates are elevated because roofing work involves significant property damage potential. A roofing crew that accidentally damages a client's home, causes a fire during hot tar application, or allows water intrusion through improper installation can generate property damage claims that are expensive to resolve. Completed operations claims, where a roof fails after the job is done and causes interior water damage, are particularly common and costly in the roofing industry.
The roofing industry also faces challenges with carrier availability. Many insurance carriers will not write roofing policies at all because the loss experience in the industry is consistently poor. Limited carrier availability means less competition, which keeps prices higher. Roofers often must work with surplus lines carriers or specialized programs that charge premium rates for coverage that other trades can obtain at standard market prices.
Weather exposure adds another cost factor. Roofing crews work in heat, cold, wind, and sometimes rain, all of which increase the risk of accidents. Seasonal fluctuations in workload can also affect pricing, as carriers know that the pressure to complete jobs during peak season can lead to safety shortcuts.
Controlling Roofer Insurance Costs
Given the high cost of roofing insurance, cost management is essential for maintaining profitability. The most impactful strategy is investing in safety to improve your experience modification factor. Your experience mod directly multiplies your workers' comp base rate, so a mod of 0.80 means you pay 20 percent less than average, while a mod of 1.40 means you pay 40 percent more. Moving your mod from above 1.0 to below 1.0 can save tens of thousands of dollars per year.
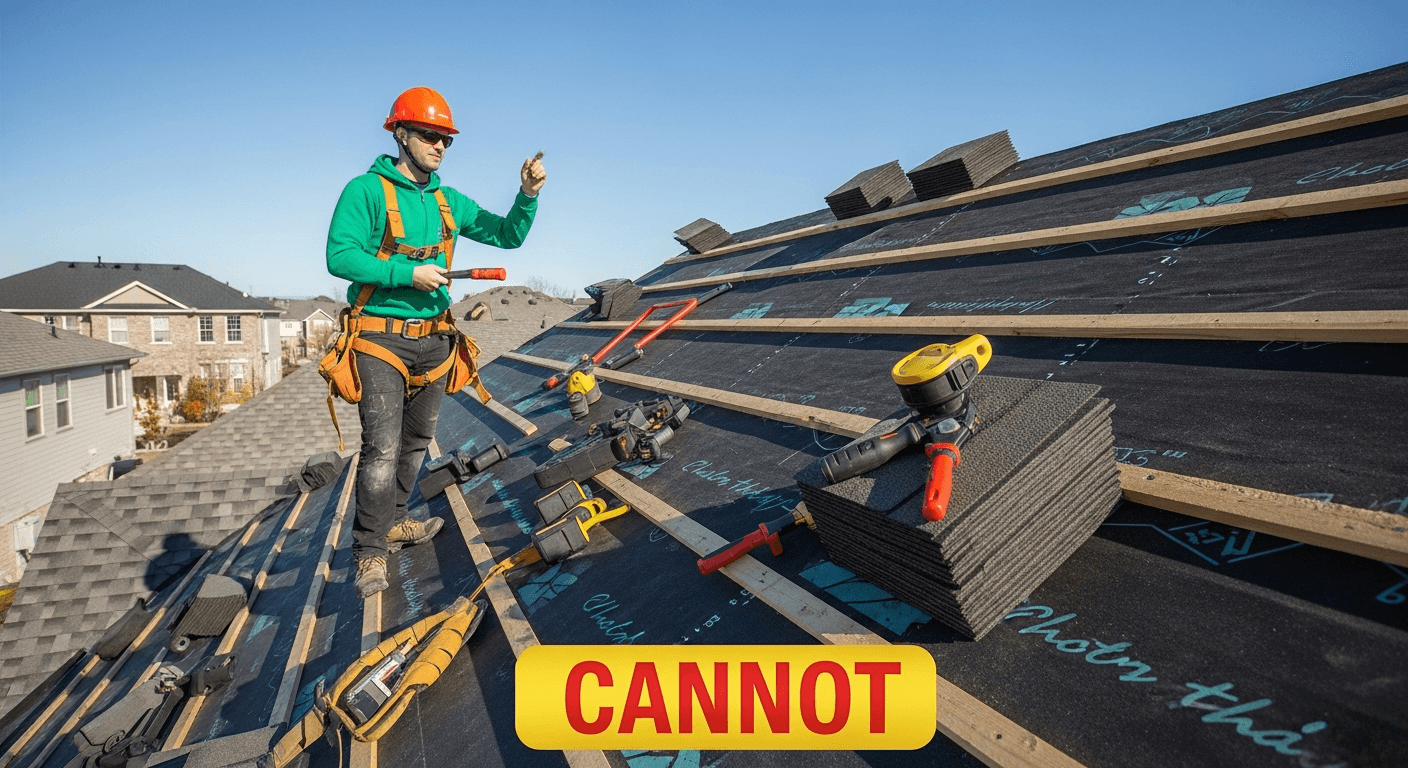
Implement a comprehensive fall protection program that exceeds OSHA minimums. This includes proper guardrail systems, personal fall arrest equipment, roof edge warning systems, and detailed fall protection training for every employee. Document all training, equipment inspections, and safety meeting attendance. Some carriers offer premium credits for demonstrated fall protection programs.
Return-to-work programs that transition injured employees to light duty as quickly as medically appropriate reduce workers' comp costs by lowering the duration and total cost of claims. Keeping injured workers engaged and returning them to productive work reduces indemnity payments and helps manage your experience mod over time.
Consider subcontracting high-risk activities like steep-slope work or commercial flat roofing if these are not your core competencies. Your insurance costs are based on the most dangerous work you perform, so eliminating the highest-risk activities from your operations can meaningfully reduce premiums. Make sure all subcontractors carry their own insurance and name your company as additional insured.
Insurance Requirements for Roofing Contractors
Some states require roofing contractors to carry general liability insurance as a condition of licensure, while many others license roofing at the local level or require only a surety bond. Where general liability minimums apply, they typically range from $500,000 to $1 million per occurrence, and higher limits may apply for larger projects or public contracts. Nearly every state also mandates workers' compensation insurance for roofing companies with employees.
Beyond state requirements, general contractors and property owners typically require roofing subcontractors to carry insurance with specific minimum limits and additional insured endorsements. Commercial and government projects often require $2 million or more in general liability limits, and large projects may specify $5 million or higher umbrella coverage. Meeting these requirements is essential for winning bids and maintaining relationships with general contractors.
Surety bonds are also commonly required for roofing contractors. A contractor's license bond guarantees that you will comply with applicable building codes and regulations. A performance bond guarantees that you will complete a project according to the contract terms. Bond requirements vary by state and project type, and the cost of bonds is influenced by your credit score, financial statements, and track record.
CPK Insurance helps roofing contractors compare coverage options and may connect you with participating licensed insurance providers that specialize in roofing risk.
Getting Roofer Insurance Quotes
Shopping for roofing insurance starts with finding carriers willing to write roofing risks at all. Not every carrier quotes roofing, so comparing several options matters more in this trade than in most. The information you need for quotes includes your annual revenue, payroll broken down by employee classification, types of roofing work performed (residential vs. commercial, steep-slope vs. flat), your experience modification factor, claims history, and safety program documentation.
CPK Insurance helps you compare options from participating licensed insurance providers that write roofing risks, and can connect you with a licensed insurance professional who understands the roofing market. Getting a comparison quote through CPK Insurance is fast and straightforward.
Request a Quote Comparison
Enter your ZIP code to compare insurance rates from top carriers.
Updated July 17, 2026