

































Updated July 16, 2026

Recommended Coverage for Retail in Minneapolis, MN
Retail businesses face unique risks that require specific coverage types. Here are the policies most retail operations need:

General Liability
Essential coverage for every business, protect against third-party bodily injury, property damage, and advertising claims.

Commercial Property
Safeguard your business property, equipment, and inventory against damage and loss.

Business Owners Policy
Bundle property and liability coverage into one convenient, cost-effective policy for small businesses.

Workers Compensation
Help cover your employees' medical expenses and lost wages for work-related injuries and illnesses.

Commercial Crime
Protect your business from financial losses caused by employee theft, fraud, and other criminal acts.

Commercial Umbrella
Extend your liability limits beyond your primary policies for extra protection against catastrophic claims.
Retail Insurance Overview in Minneapolis, MN
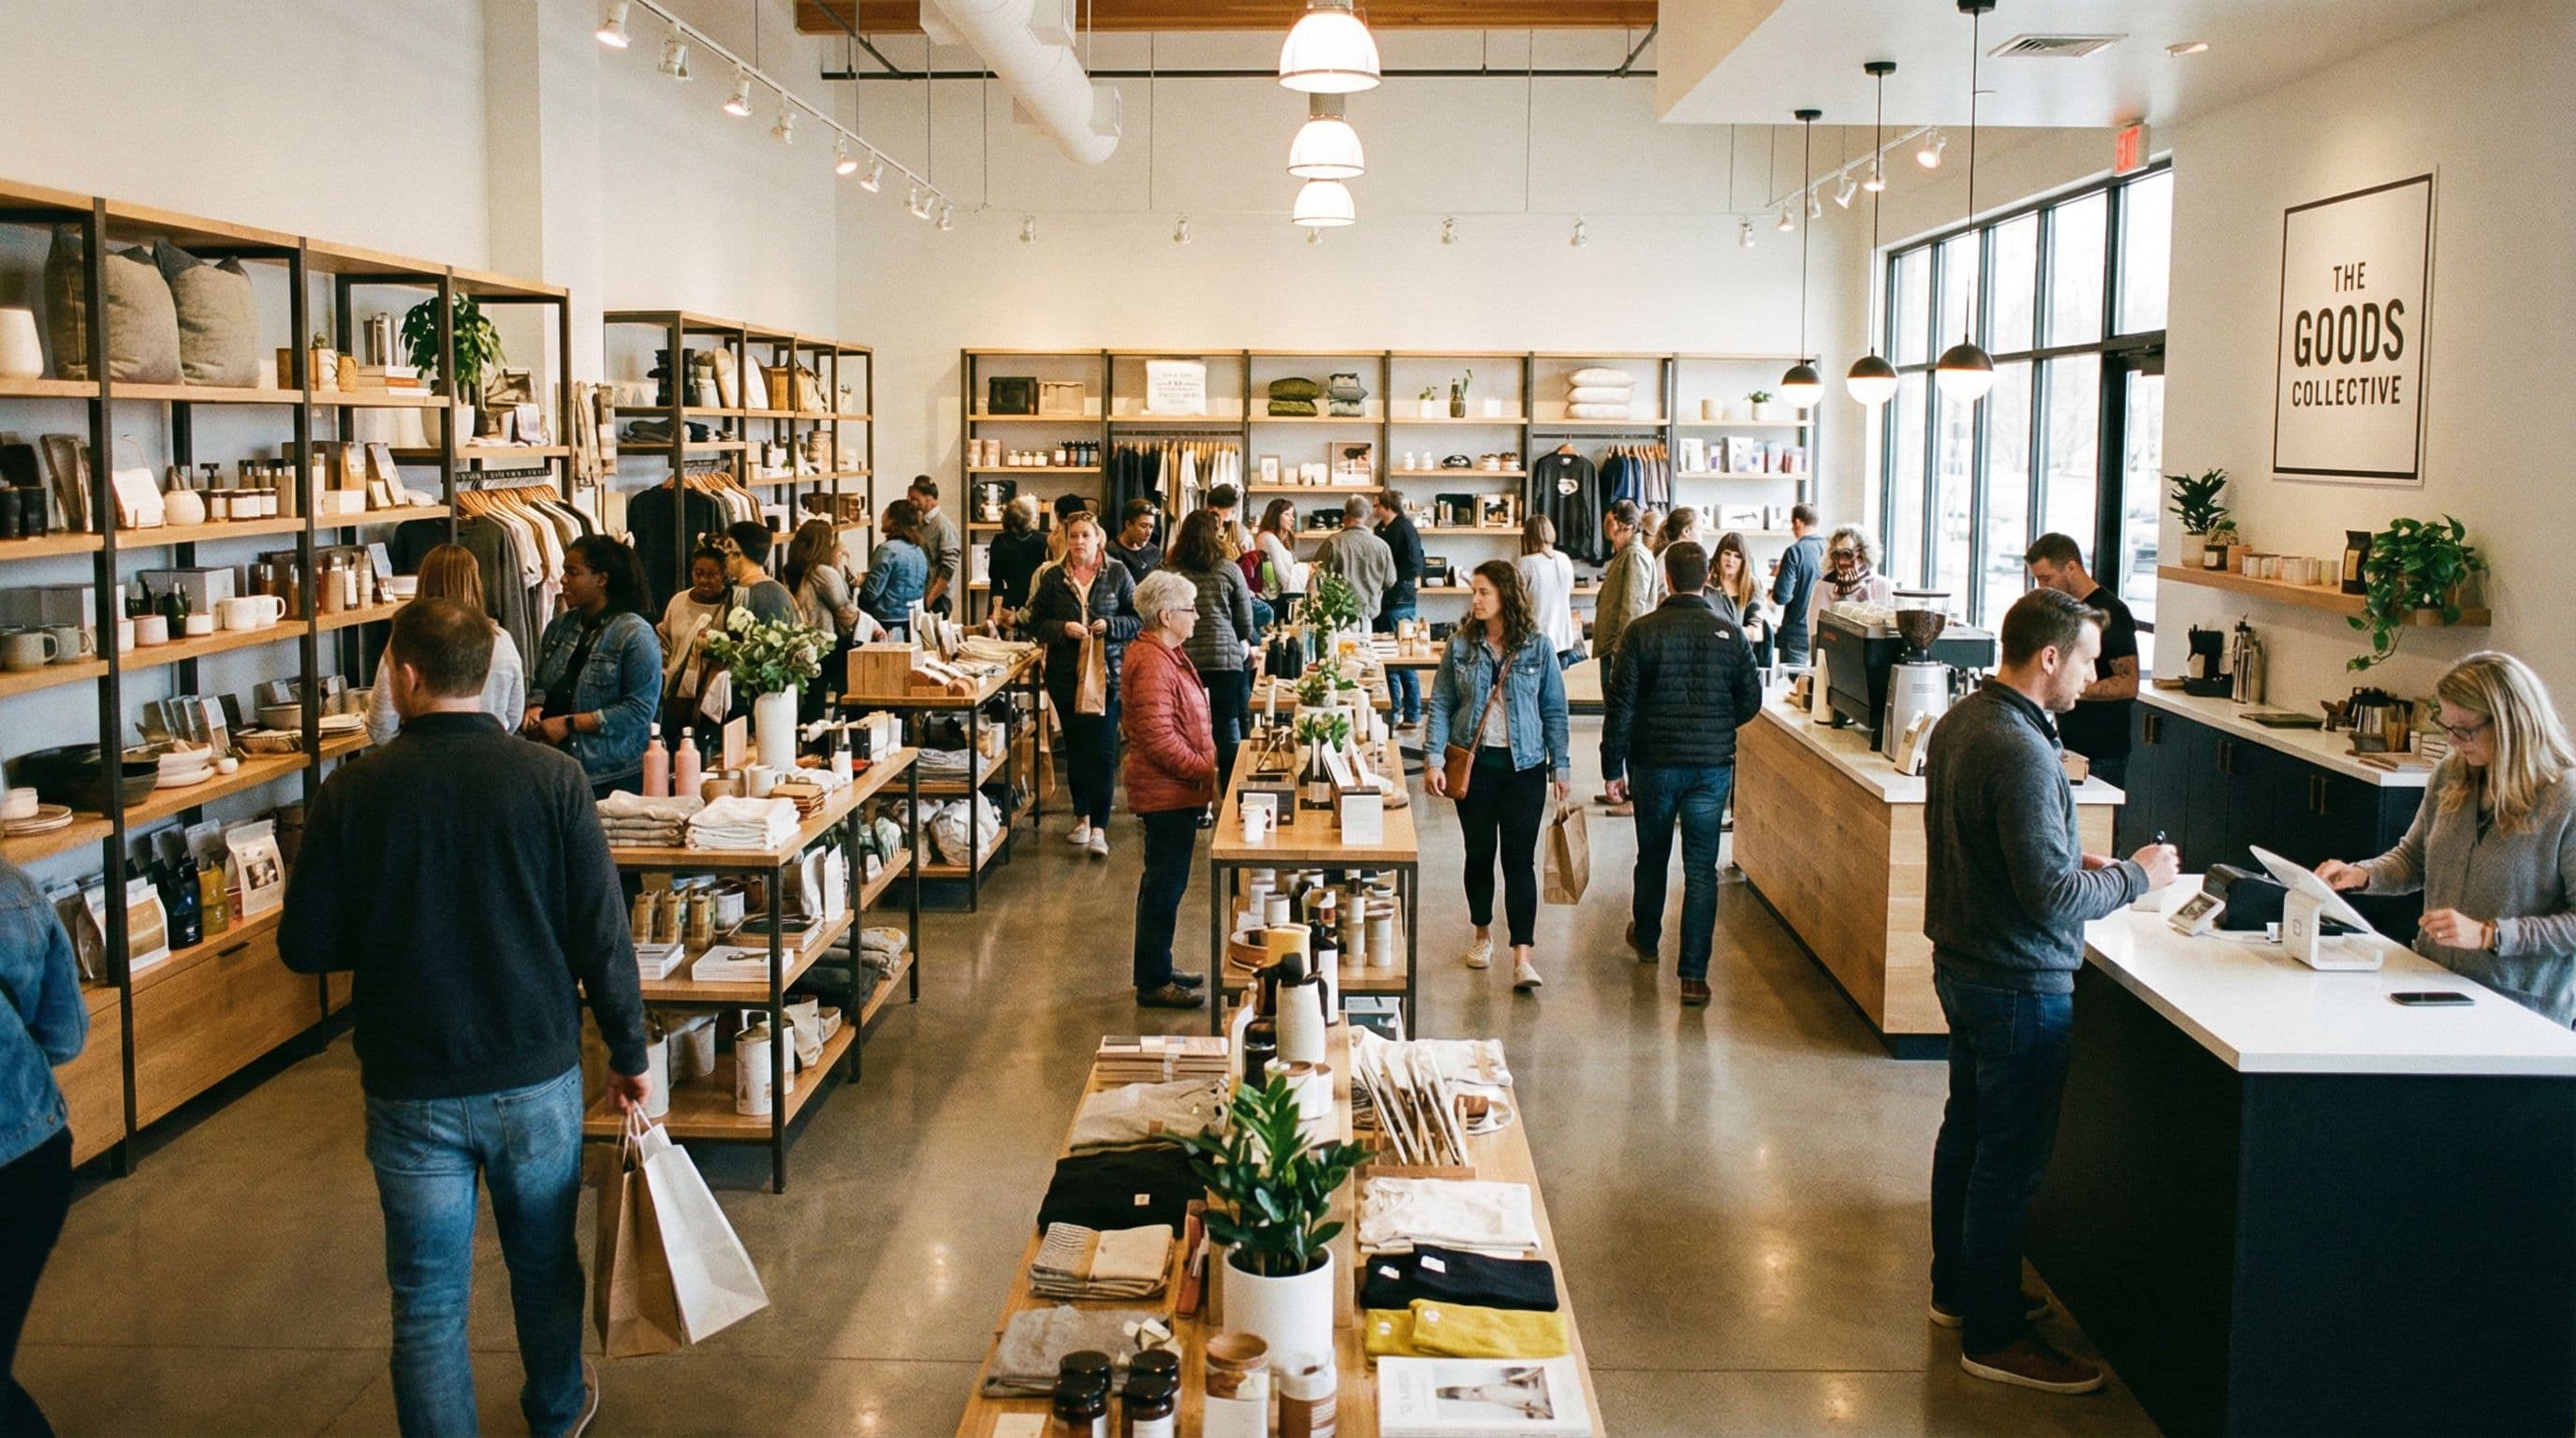
Retail insurance in Minneapolis has to fit a city where storefront traffic, weather swings, and property crime can all affect the same business week. A boutique near the downtown core deals with foot traffic and weather exposure in ways a warehouse-based e-commerce operation simply does not. You are operating in a competitive environment where margins and daily conditions can shift quickly, so your policy needs to account for property damage, theft, and customer injury alongside your inventory and sales interruptions. If you are comparing options, the right approach is to match coverage to your location, traffic patterns, and how you store stock. That holds whether you run a single storefront or several locations that need consistent protection across sites.
Why Retail Businesses Need Insurance in Minneapolis, MN
Your store probably operates in a high-traffic setting where customer injuries and property damage can happen during normal business hours. A wet entryway after severe weather, a crowded seasonal display, or a busy checkout area can all create liability needs that are easy to overlook until a claim appears. Property crime rates here run higher than the national average, which means a single break-in could cost you thousands in lost stock and repairs. Commercial crime insurance may be worth reviewing if you keep high-value stock, handle funds transfer activity, or manage several people with access to cash and records. For most retail locations, commercial property insurance can help address building damage, fire, vandalism, storm damage, and equipment breakdown. If your business depends on daily sales, business interruption coverage can matter when a covered loss slows operations. The goal is to align your policy with your actual sales cycle, staffing model, and physical footprint.
Minnesota requires workers' comp for businesses with employees (exemptions may apply: Sole proprietors; Partners). Non-compliance can result in fines and personal liability for owners. Commercial auto minimums are $30,000/$60,000/$10,000.
Key Risks for Retail Businesses
Each of these risks can lead to claims that cost thousands, or more. Make sure your policy addresses every one:
- Customer slip-and-fall injuries
- Inventory theft or loss
- Product liability claims
- Property damage
- Employee dishonesty
What Drives Retail Insurance Costs in Minneapolis, MN
Cost varies based on store size, inventory value, customer traffic, and the kinds of locations you operate in. A boutique storefront, pop-up shop, or warehouse-based e-commerce operation will not usually share the same risk profile, so your quote will depend on your mix of property and liability coverage. Local conditions also matter, particularly when it comes to water and crime risk. Some areas of the city fall within flood zones, which means a single heavy storm could put your inventory and fixtures at risk of water damage. Higher property crime rates can also push up premiums for property and crime coverage, since insurers price for the realistic chance of theft. Minneapolis has low natural disaster frequency, which may help balance some of those costs by reducing the likelihood of a major weather-related payout. If you want requirements to be easier to compare, it helps to review your building type, security controls, inventory levels, and whether you need bundled coverage through a business owners policy.
Retail businesses typically carry several separately priced policies. The ranges below are typical figures for Minneapolis for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $45 - $140 per month | Industry and risk classification, annual revenue, number of employees |
| Commercial Property Insurance | $65 - $350 per month | Building value and construction type, roof age and condition, fire protection class |
| Business Owners Policy Insurance | $55 - $210 per month | Annual revenue and industry class, building and contents values, square footage and building age |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
| Commercial Crime Insurance | $20 - $80 per month | Employees who handle money or inventory, internal controls and separation of duties, funds and securities on hand |
| Commercial Umbrella Insurance | $45 - $150 per month | Umbrella limit requested, limits carried on the underlying policies, loss history on those underlying policies |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
State Requirements
Insurance Regulations in Minnesota
Key regulatory requirements for businesses operating in MN.
Regulatory Authority
Workers' Compensation InsuranceRequired
Required for employers with 1+ employee.
Exempt categories
- Sole proprietors
- Partners
- Officers of closely held corporations
Commercial Auto Minimum Liability
$30,000/$60,000/$10,000 (bodily injury per person / per accident / property damage)
Source: Minnesota Department of Insurance, U.S. Department of Labor
Climate Risk Profile
Natural Disaster Risk in Minnesota
Understanding climate-related risks helps determine appropriate insurance coverage levels.
Severe Storm
High
Tornado
High
Winter Storm
Very High
Flooding
Moderate
Expected Annual Loss from Natural Hazards
$1.2B
estimated economic loss per year across Minnesota
Source: FEMA National Risk Index
Insurance Tips for Retail Business Owners in Minneapolis, MN
Match general liability insurance to customer traffic patterns, especially if you run a high-traffic storefront or shopping center location.
Review commercial property insurance if you keep seasonal inventory, use specialized fixtures, or operate in a mixed-use space where building damage or storm damage could interrupt sales.
Consider a business owners policy if you want bundled property and liability coverage in one place, but confirm that your inventory and location details are reflected accurately.
If your store handles cash, deposits, or remote payments, ask about commercial crime insurance to address employee theft, forgery, fraud, and funds transfer exposure.
For higher-traffic stores or multi-location retail chains, compare commercial umbrella insurance to see whether excess liability limits fit your customer volume and third-party claims risk.
If you rely on stock movement or online fulfillment, include e-commerce insurance in your review so inventory, equipment, and business interruption risks are considered together.
Get Retail Insurance in Minneapolis, MN
Enter your ZIP code to compare retail insurance rates from top carriers.
Business insurance starting at $25/mo
Retail Business Types in Minneapolis, MN
Find insurance tailored to your specific retail business. Select your business type for coverage recommendations, pricing, and quotes:

Tailors Insurance
Get a tailors insurance quote built for alteration shops, seamstresses, and custom clothing businesses. Coverage can help with customer garment damage, liability coverage, and shop property needs.

Dry Cleaning & Laundry Insurance
Request a dry cleaning and laundry insurance quote built for garment-care businesses. Compare dry cleaner coverage, bailee liability insurance, and more.

Convenience Store Insurance
Get a convenience store insurance quote built for high foot traffic, cash handling, and food sales. Coverage can be tailored to your property, liability, and crime needs.

Liquor Store Insurance
Liquor store insurance helps protect alcohol retailers from property damage, theft, liability, and compliance-related claims. Request a liquor store insurance quote tailored to your location and operations.

Florist Insurance
Get florist insurance built around refrigeration, deliveries, and customer-facing shop risks. Compare coverage options and request a tailored quote for your retail flower shop.

Jewelry Store Insurance
Request a jewelry store insurance quote built for high-value inventory, theft exposure, and specialized valuation needs. Compare coverage options for showcases, back-room stock, and customer pieces.

Gas Station Insurance
Get a gas station insurance quote built around fuel handling, underground tanks, store operations, and location-specific requirements. Compare coverage options for your station, convenience store, and liability exposures.

Smoke Shop Insurance
Smoke shop insurance can help protect tobacco and vape retailers from product, property, and crime-related losses. Coverage can be tailored to your store’s location, inventory, and compliance needs.

Furniture Store Insurance
Get a furniture store insurance quote built for showroom traffic, delivery damage, and stored inventory. Compare coverage options for your store, warehouse, and deliveries.

Thrift Store Insurance
Get coverage built for donated inventory, customer injury, and store property. Request a thrift store insurance quote tailored to your resale shop, consignment shop, or secondhand store.

Pet Store Insurance
Get a pet store insurance quote built for retailers that sell live animals, pet food, and supplies. Compare liability, property, and business interruption options.

Hardware Store Insurance
Hardware stores face injury exposure in aisles, at the counter, and around tools, paint, and chemicals. Get coverage built for retail operations, inventory, and store incidents.

E-Commerce Business Insurance
E-commerce business insurance helps online sellers protect against product liability, cyber theft, and other digital-first risks. Request an ecommerce business insurance quote tailored to your store.

Grocery Store Insurance
Get a grocery store insurance quote designed for daily foot traffic, refrigerated inventory, and customer injury exposure. Coverage can be tailored for supermarkets, specialty food retailers, and multi-location stores.

Cell Phone Repair Insurance
Request a cell phone repair insurance quote built for repair counters, mall kiosks, and multi-location shops. Match coverage to device damage, data liability, and parts defects.

Craft Vendor Insurance
Get a craft vendor insurance quote for craft fairs, markets, and booth setups. Compare coverage for liability, inventory, and event property needs.

Arts & Crafts Store Insurance
Get an arts and crafts store insurance quote built for craft supply shops with flammable inventory, customer traffic, and property exposure. Coverage can be matched to your store layout, stock, and operations.

Bike Shop Insurance
Bike shops need coverage for customer injuries, repair work, inventory theft, and property loss. Get a quote-ready policy built for retail sales, service bays, and storefront risk.

Bookstore Insurance
Get a bookstore insurance quote built around your shop's property, inventory, and premises liability needs, with options that can help protect your storefront, stock, and income after a setback.

Candle Store Insurance
Get a candle store insurance quote built for candle retailers, wax product shops, and multi-location stores. Compare options for product liability, fire coverage, and property protection.

Candy Store Insurance
Get a candy store insurance quote for storefront property, customer foot traffic, and food-related liability exposures. Coverage can be tailored for retail candy shops, kiosks, and confectionery retailers.

Clothing Store Insurance
Get a clothing store insurance quote built for boutiques, apparel stores, and fashion retailers. Compare coverage for inventory, customer injury, and property needs.

Electronics Store Insurance
Request an electronics store insurance quote tailored to high-value inventory, customer claims, cyber risks, and retail property needs. Coverage options can fit a storefront, repair counter, or technology showroom.

Fabric Store Insurance
Get a fabric store insurance quote designed for textile retailers handling inventory, fixtures, and customer visits. Compare liability and property coverage options for your shop.

Luggage Store Insurance
Luggage store insurance can help protect retailers that sell luggage and travel accessories against customer injury claims, inventory losses, and premises damage. Compare quote options built around your storefront, stock, and daily foot traffic.

Medical Supplies Store Insurance
Get a medical supplies store insurance quote built for retail locations that sell patient-dependent products, durable equipment, and inventory customers rely on. Choose coverage that fits your storefront, showroom, and delivery needs.

Pawn Shop Insurance
Get a pawn shop insurance quote built around customer property, cash handling, inventory, and location-specific risk. Compare options for a single shop or multi-location operation.

Retail Store Insurance
Get a retail store insurance quote built around your shop's location, inventory, and customer traffic. Compare coverage options for liability, property, and business interruption.

Toy Store Insurance
A toy store insurance quote helps match your retail risks with the coverage you may need for customer injuries, property damage, and defective products. Compare options for your storefront, inventory, and daily operations.
FAQ
Retail Insurance FAQ in Minneapolis, MN
Coverage can vary, but Minneapolis retail insurance is commonly built around liability coverage, property coverage, and protection for inventory, equipment, and business interruption. Depending on your operations, it may also address customer injury, third-party claims, theft, vandalism, storm damage, and fire risk.
A retail insurance quote usually depends on your store type, location, inventory value, customer traffic, and whether you operate as a boutique storefront, shopping center tenant, or warehouse-based e-commerce operation. Details about security, building type, and bundled coverage also matter.
Requirements vary by lease, lender, and business structure. Many retailers review general liability insurance, commercial property insurance, and, when applicable, workers compensation insurance. Your exact retail insurance requirements in Minneapolis depend on your operations and contracts.
Yes, many retailers look at a business owners policy to combine property coverage and liability coverage. Whether that fits your business depends on your inventory, building setup, and the kinds of claims you want to address.
Commercial crime insurance is often reviewed for employee theft, forgery, fraud, and funds transfer exposure. If your Minneapolis store keeps valuable stock or handles frequent cash activity, this can be an important part of your review.
Start with your store size, inventory levels, equipment, daily customer traffic, and location type. A downtown shop may need different limits than a strip mall unit or multi-location retail chain. It also helps to think through catastrophic claims, excess liability, and whether commercial umbrella insurance should be part of the plan.
General liability and commercial property form the core, and many stores package them through a business owners policy. Add workers compensation once you have employees, commercial crime where staff handle cash or resellable stock, and umbrella limits when a lease or heavy foot traffic calls for more liability capacity.
Yes, the exposures shift even though the products are the same. Inventory concentrates in storage areas, fulfillment drives the workday, and returns and packing change the injury and theft picture, so property values, employee duties, and transit arrangements deserve their own look.