

































Updated July 16, 2026

Recommended Coverage for Wholesalers & Distributors in Knoxville, TN
Wholesalers & Distributors businesses face unique risks that require specific coverage types. Here are the policies most wholesalers & distributors operations need:

General Liability
Essential coverage for every business, protect against third-party bodily injury, property damage, and advertising claims.

Commercial Property
Safeguard your business property, equipment, and inventory against damage and loss.

Commercial Auto
Protect your business vehicles and drivers with comprehensive commercial auto coverage.

Commercial Truck
Comprehensive coverage for trucking operations, from long-haul rigs to local delivery vehicles.

Inland Marine
Protect tools, equipment, and goods in transit or stored at locations away from your primary premises.

Workers Compensation
Help cover your employees' medical expenses and lost wages for work-related injuries and illnesses.
Wholesalers & Distributors Insurance Overview in Knoxville, TN
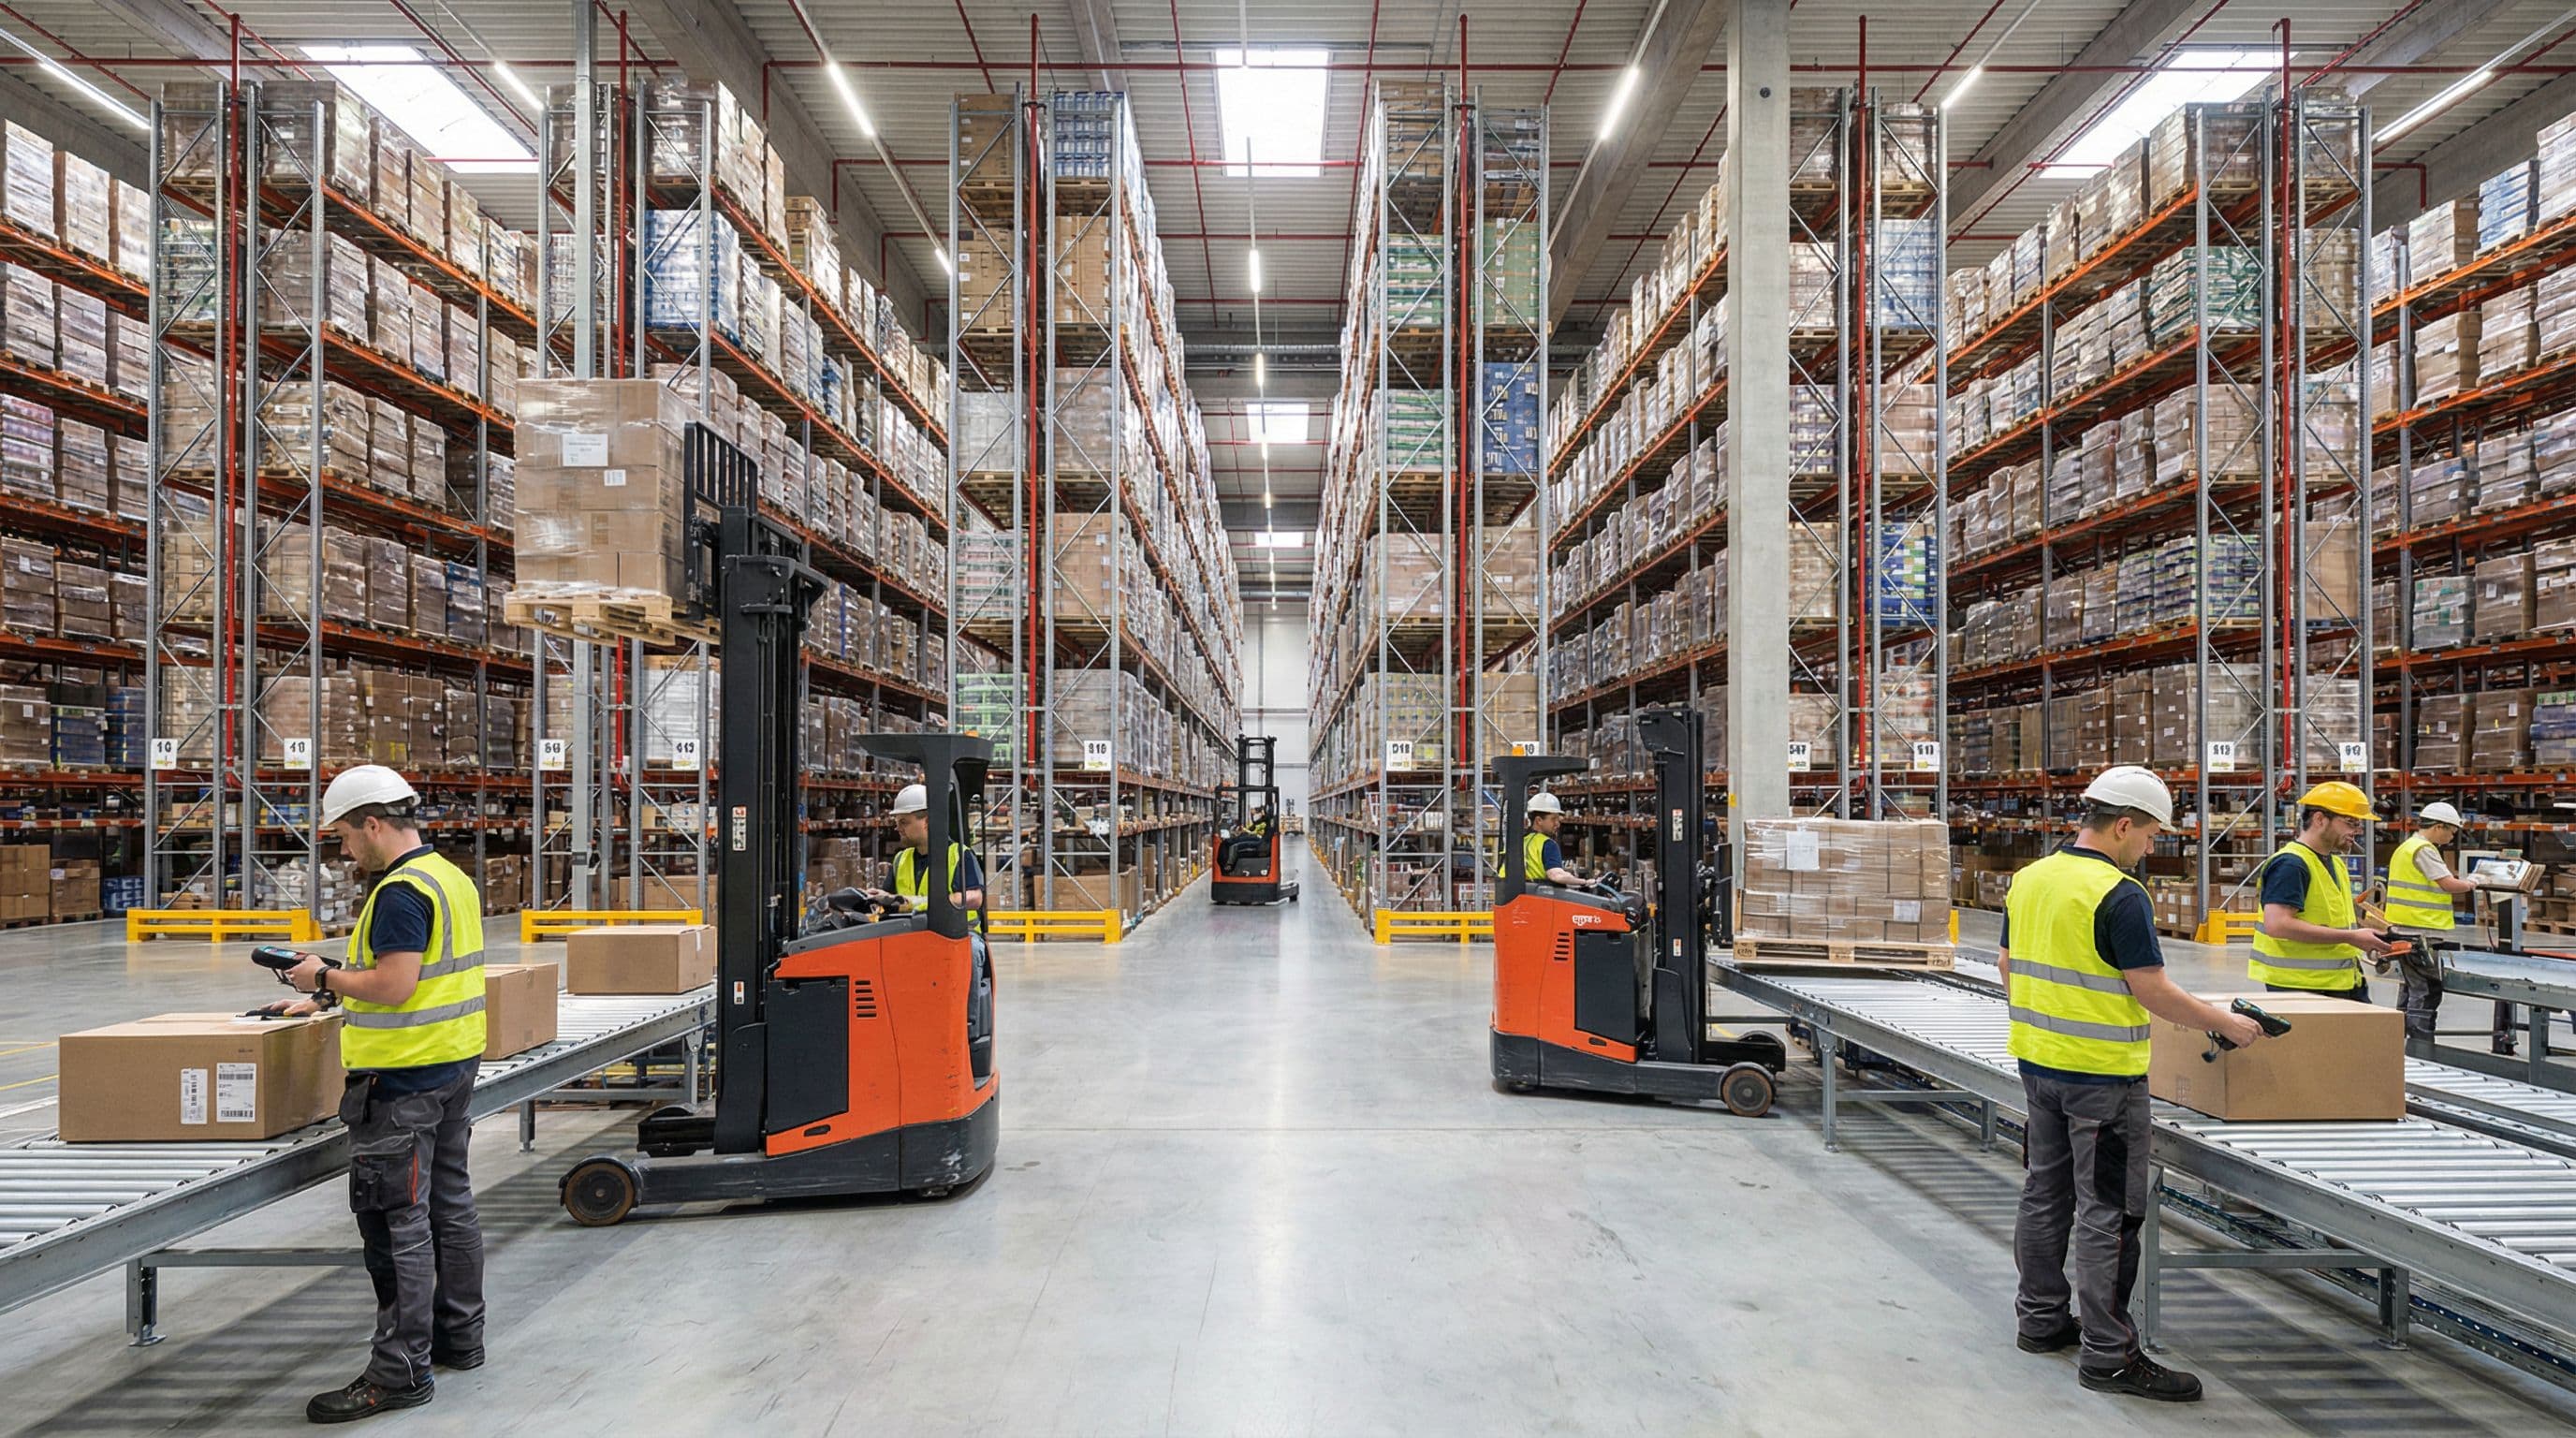
Your racks, forklifts, loading areas, delivery vans, and warehouse space keep orders moving. Protecting those assets starts with understanding how goods are received, stored, picked, and sent back out on local routes. Your policy should match the way your operation actually runs. That means palletized inventory stacked in a warehouse, drivers making scheduled stops across town, and products that may sit briefly on a dock before they are loaded again. If one loss hits the building, a vehicle, or stock in transit, the interruption can spread quickly into missed deliveries and strained customer relationships.
That is why it helps to review your liability, property, vehicle, transit, and workers compensation coverage as one operating picture instead of separate purchases. Knox County has 12,350 business establishments, which translates to enough competition for warehouse space and vendor contracts that you are likely to face documentation requirements before a deal closes. In practical terms, landlords, customers, and vendors often expect organized proof of coverage before space is leased or contracts move forward.
Why Wholesalers & Distributors Businesses Need Insurance in Knoxville, TN
Inventory may be unloaded at your facility, staged for short periods, moved by forklift, loaded into vans or trucks, and delivered to commercial customers on tight schedules. A distributor here may serve retail, contractor, office, or institutional accounts across the county from one warehouse. Drivers often return for second runs or rush replacements later the same day. If your insurance program is built too narrowly, you can end up with a building policy that does not line up well with stock values, or vehicle coverage that is not reviewed alongside loading and unloading activity.
General liability insurance can help with third party injury or property damage claims tied to your premises or operations. Commercial property insurance is where you review the building, business personal property, and stock. Commercial auto or commercial truck insurance should follow the vehicles you actually use, while inland marine insurance applies when goods regularly move between locations or travel with drivers before delivery is complete. Workers compensation insurance is also part of the picture when warehouse staff lift, stage, and load inventory throughout the day.
Tennessee requires workers' comp for businesses with 5+ employees (exemptions may apply: Sole proprietors; Partners). Non-compliance can result in fines and personal liability for owners. Commercial auto minimums are $25,000/$50,000/$25,000.
Key Risks for Wholesalers & Distributors Businesses
Each of these risks can lead to claims that cost thousands, or more. Make sure your policy addresses every one:
- Inventory damage or spoilage
- Cargo theft during transit
- Warehouse fire or natural disaster
- Fleet vehicle accidents
- Product liability claims
What Drives Wholesalers & Distributors Insurance Costs in Knoxville, TN
A quote for your operation usually turns on details like what you store, how much inventory is on hand, and how often vehicles are on the road. Carriers often look at whether stock changes seasonally, who loads vehicles, and whether your drivers use vans, box trucks, or heavier commercial units. The more accurately those details are described, the easier it is to compare terms that fit your actual workflow.
A warehouse with higher stock concentrations, frequent dock activity, or limited room for separated storage can be rated differently from a smaller operation with lower values on site. Auto and truck pricing can also shift with route radius, driver records, vehicle type, and where units are parked after hours.
Workers compensation insurance is commonly shaped by payroll, job duties, and claims history. That matters most if employees split time between office work, warehouse handling, and delivery support. When you request quotes, bring current vehicle schedules, estimated inventory peaks, payroll by role, and any certificate requirements you already receive from customers or property managers.
Wholesalers & Distributors businesses typically carry several separately priced policies. The ranges below are typical figures for Knoxville for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $85 - $390 per month | Industry and risk classification, annual revenue, number of employees |
| Commercial Property Insurance | $190 - $950 per month | Building value and construction type, roof age and condition, fire protection class |
| Commercial Auto Insurance | $200 - $625 per month | Fleet size and vehicle types, driver records and experience, coverage limits and deductibles |
| Commercial Truck Insurance | $280 - $925 per month | Radius of operation, commodities hauled and cargo value, number and value of power units |
| Inland Marine Insurance | $55 - $290 per month | Total insured value of the scheduled property, type and age of the equipment, where it is stored and how far it travels |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
State Requirements
Insurance Regulations in Tennessee
Key regulatory requirements for businesses operating in TN.
Regulatory Authority
Workers' Compensation InsuranceRequired
Required for employers with 5+ employees.
Exempt categories
- Sole proprietors
- Partners
- Members of LLCs
- Farm laborers
Commercial Auto Minimum Liability
$25,000/$50,000/$25,000 (bodily injury per person / per accident / property damage)
Source: Tennessee Department of Insurance, U.S. Department of Labor
Climate Risk Profile
Natural Disaster Risk in Tennessee
Understanding climate-related risks helps determine appropriate insurance coverage levels.
Tornado
Very High
Flooding
High
Severe Storm
High
Earthquake
Moderate
Expected Annual Loss from Natural Hazards
$1.8B
estimated economic loss per year across Tennessee
Source: FEMA National Risk Index
Insurance Tips for Wholesalers & Distributors Business Owners in Knoxville, TN
Separate warehouse stock values from office contents and mobile equipment so your commercial property insurance reflects what would actually be expensive to replace after a loss.
Review inland marine insurance if products leave your building before final delivery, especially when goods stay on a truck, at a temporary stop, or between customer locations.
Match commercial auto or commercial truck insurance to the vehicles you really use, including box trucks, cargo vans, and any units parked at the warehouse overnight.
Break payroll out by job function before quoting workers compensation insurance, because warehouse handling, driving support, and clerical work are not viewed the same way.
Ask for certificates and additional insured language early if your customers, landlords, or vendors require them, so policy setup does not delay a new account or lease.
Document loading practices, driver routes, and where losses could happen between dock and delivery, then use that workflow to review liability, property, and transit coverage together.
Get Wholesalers & Distributors Insurance in Knoxville, TN
Enter your ZIP code to compare wholesalers & distributors insurance rates from top carriers.
Business insurance starting at $25/mo
Wholesalers & Distributors Business Types in Knoxville, TN
Find insurance tailored to your specific wholesalers & distributors business. Select your business type for coverage recommendations, pricing, and quotes:

Freight Broker Insurance
Get a freight broker insurance quote built for brokerage and logistics operations that need protection when carrier policies do not fully pay a claim. Coverage can be tailored around contingent cargo, E&O, cyber, and crime needs.

Trucking Company Insurance
Get a trucking company insurance quote built around your routes, vehicles, and cargo. Compare coverage for fleets and owner-operators, including commercial auto, cargo, and liability.

Courier & Delivery Service Insurance
Get coverage built for courier operations that face vehicle accidents, package loss, and commercial auto requirements. Compare options for single vehicles, fleets, and local delivery routes.

Warehouse Insurance
Get a warehouse insurance quote built around inventory value, equipment exposure, and premises risks. Coverage can be tailored for warehouses and fulfillment centers.

Import & Export Business Insurance
Import and export business insurance can help wholesalers and distributors with cargo loss, goods in transit, and liability gaps across the supply chain. Get a quote tailored to your routes, shipment types, and trade operations.
FAQ
Wholesalers & Distributors Insurance FAQ in Knoxville, TN
Knoxville wholesalers often pair inland marine insurance with commercial property insurance because stock is not exposed only inside the warehouse. If goods are staged, loaded, and carried on local routes before delivery is complete, transit exposure should be reviewed with the rest of the account.
Gathering vehicle schedules, driver lists, payroll by job role, estimated peak inventory values, warehouse square footage, and any lease or customer insurance requirements can speed up quoting. That gives the quote a better chance of matching how your operation actually stores and moves goods.
Knoxville distributors often do, because commercial auto insurance and commercial truck insurance are reviewed based on the type of vehicle, how it is used, and who drives it. If your fleet mixes cargo vans and larger units, list each one clearly before comparing quotes.
Knoxville warehouse leases often drive insurance details such as proof of coverage, liability limits, and who must be shown on certificates. Knox County has 12,350 business establishments, so landlords can afford to be selective and organized documentation often becomes a practical entry requirement rather than a formality.
Knoxville warehouse operators should usually start by reviewing commercial property insurance, general liability insurance, and inland marine insurance together. Daily forklift use and dock activity can affect building exposures, third party property damage claims, and goods moving through the same operation.
Knoxville businesses can usually structure one coordinated insurance program that reviews property, vehicle, and transit exposures together, even though coverage may sit in more than one policy. That approach helps you compare gaps between warehouse storage, road use, and goods moving to customers.
The Tennessee Department of Commerce and Insurance regulates business insurance in the state, which gives you a reference point for carrier oversight. From there, focus your quote review on limits, exclusions, and operational fit so the policy matches how your warehouse and delivery operation actually works.
Six policies cover the standard footprint: general liability, commercial property, commercial auto, commercial truck, inland marine, and workers compensation. Whether you mainly store stock, run deliveries, use heavier vehicles, or move goods through several locations decides which of them carries the load.
Sources
- 1.S. Census Bureau, County Business Patterns, Knox County(In Knox County, there are 12350 business establishments, so many wholesalers and distributors work in a market where landlords, customers, and vendors often expect organized proof of coverage before space is leased or contracts move forward.)