

































Updated July 16, 2026

Recommended Coverage for Retail in Sterling Heights, MI
Retail businesses face unique risks that require specific coverage types. Here are the policies most retail operations need:

General Liability
Essential coverage for every business, protect against third-party bodily injury, property damage, and advertising claims.

Commercial Property
Safeguard your business property, equipment, and inventory against damage and loss.

Business Owners Policy
Bundle property and liability coverage into one convenient, cost-effective policy for small businesses.

Workers Compensation
Help cover your employees' medical expenses and lost wages for work-related injuries and illnesses.

Commercial Crime
Protect your business from financial losses caused by employee theft, fraud, and other criminal acts.

Commercial Umbrella
Extend your liability limits beyond your primary policies for extra protection against catastrophic claims.
Retail Insurance Overview in Sterling Heights, MI
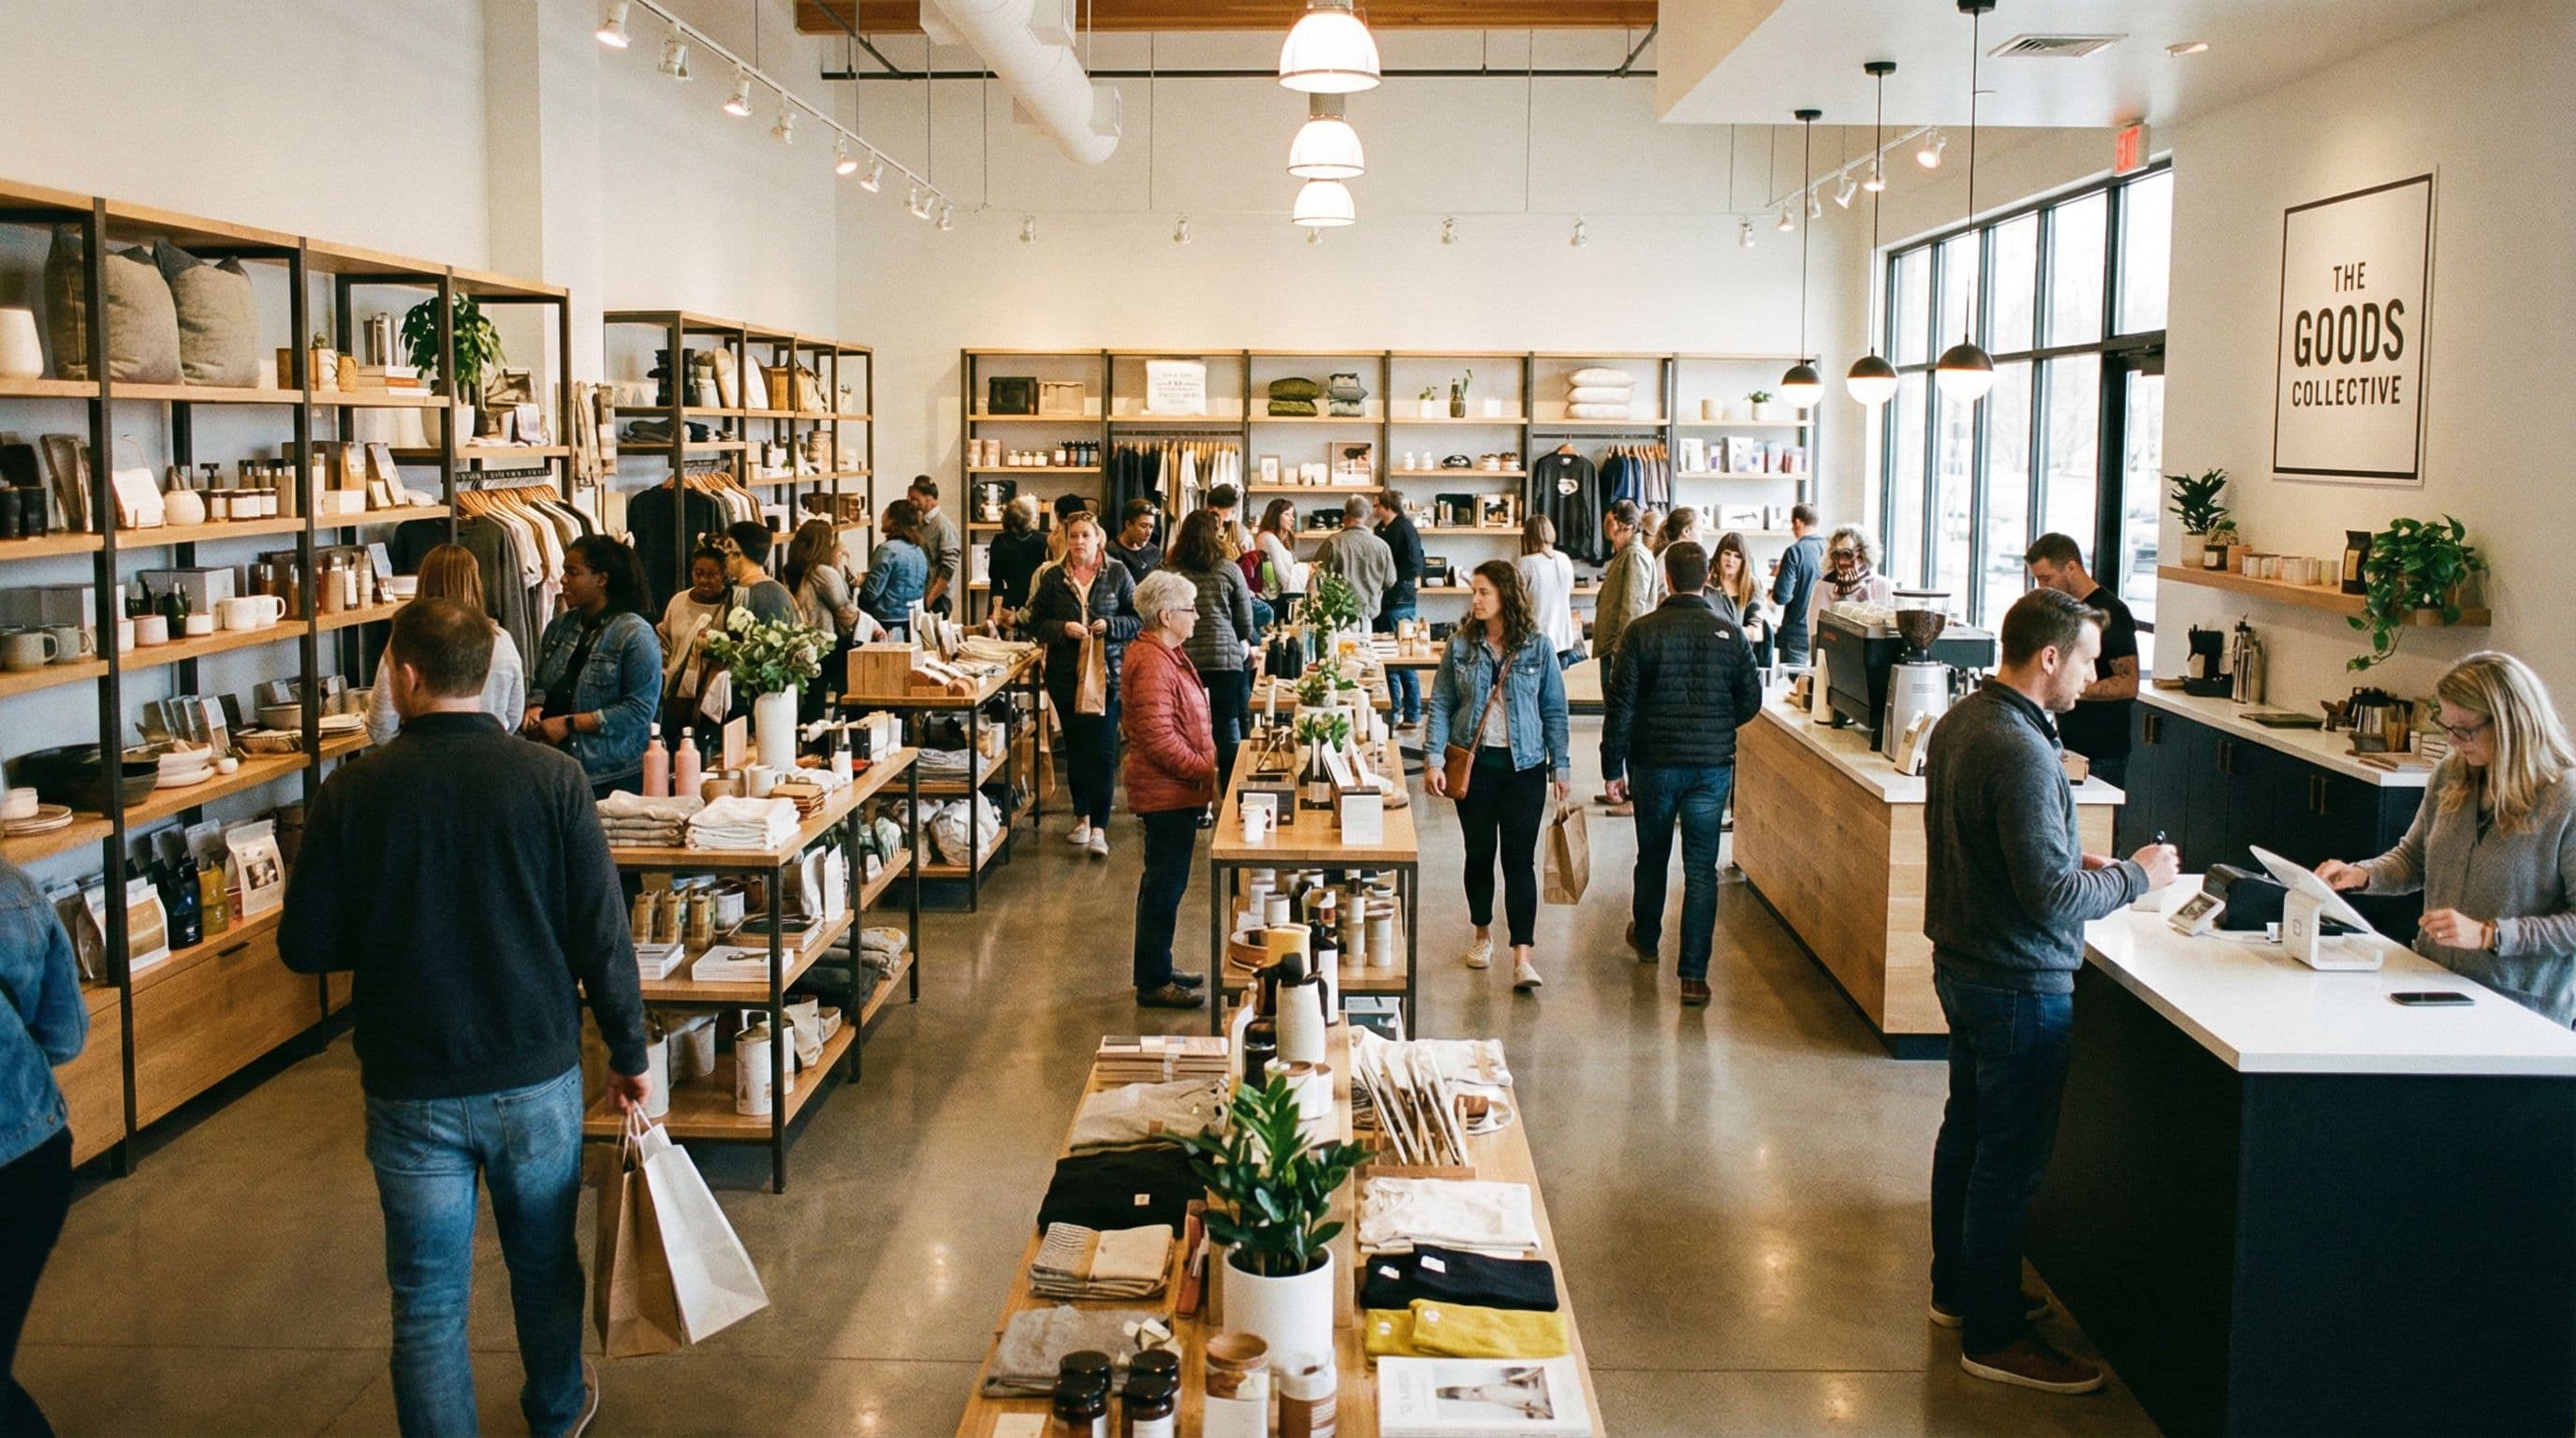
Retail insurance in Sterling Heights should reflect how this market actually operates. Whether you run a strip mall storefront, a mall kiosk, or a warehouse-based e-commerce operation, your exposures shift with each format. Retail accounts for 4% of local industry, which translates to a steady mix of in-person shoppers and online orders flowing through area stores. That means customer slip-and-fall injuries, property damage, inventory theft, and third-party claims can show up in more than one way. Sterling Heights also brings local planning factors into the conversation. The city has a crime index of 76, meaning property crime runs high enough to warrant theft provisions beyond what a lower-risk area would demand. About 11% of the city sits in a flood zone, so a separate water damage endorsement may be worth adding since standard policies often exclude it. Low natural disaster frequency is a plus, but top risks still include weather events, property crime, and vehicle accidents. Your policy should grow out of what actually happens around your checkout counter, stockroom, and delivery or pickup operations.
Why Retail Businesses Need Insurance in Sterling Heights, MI
Retail businesses in Sterling Heights deal with a mix of foot traffic, inventory movement, and property exposure that can quickly create costly claims. A wet entryway, a crowded aisle, or a severe storm can each interrupt sales and trigger legal defense or settlement costs. For stores in shopping centers, strip mall units, and main street storefronts, the location itself can shape how much property and liability coverage make sense. The local business mix matters too, since healthcare, manufacturing, and professional services bring workers, families, and commuters through your doors all day. That can mean busier parking lots, more deliveries, and more wear on fixtures, equipment, and inventory. A warehouse-based e-commerce operation may need a different policy mix than a boutique storefront or mall kiosk, especially if stock is stored on-site or moved frequently. Many owners start by reviewing general liability, commercial property, and a business owners policy. If employee theft or fraud is part of your risk picture, commercial crime coverage can also be worth reviewing.
Michigan requires workers' comp for businesses with employees (exemptions may apply: Sole proprietors; Partners). Non-compliance can result in fines and personal liability for owners. Commercial auto minimums are $50,000/$100,000/$10,000.
Key Risks for Retail Businesses
Each of these risks can lead to claims that cost thousands, or more. Make sure your policy addresses every one:
- Customer slip-and-fall injuries
- Inventory theft or loss
- Product liability claims
- Property damage
- Employee dishonesty
What Drives Retail Insurance Costs in Sterling Heights, MI
Retail insurance cost in Sterling Heights varies based on your store type, inventory level, building value, and customer traffic. Higher inventory values, more equipment, and broader coverage limits can all affect the premium. Local conditions also matter. The city's crime index of 76 signals moderate property crime exposure, and carriers may price that into your quote if your storefront lacks security upgrades. The 11% flood-zone percentage and exposure to severe weather can also influence how carriers price property damage, storm damage, and business interruption risk, since a flood endorsement could be the difference between a manageable claim and a total loss. If your operation includes valuable stock, seasonal merchandise, or customer-facing fixtures, your quote may shift based on those details. Bundling property and liability through a business owners policy can simplify planning, though the final cost depends on your actual operations and the limits you choose.
Retail businesses typically carry several separately priced policies. The ranges below are typical figures for Sterling Heights for each line, except workers compensation, which is rated per $100 of payroll; a quote prices each one against your own operations.
| Coverage | Typical range | What moves your price |
|---|---|---|
| General Liability Insurance | $45 - $160 per month | Industry and risk classification, annual revenue, number of employees |
| Commercial Property Insurance | $45 - $240 per month | Building value and construction type, roof age and condition, fire protection class |
| Business Owners Policy Insurance | $50 - $210 per month | Annual revenue and industry class, building and contents values, square footage and building age |
| Workers Compensation Insurance | $0.75 - $2.74 per $100 of payroll | Employee classification codes, total annual payroll, experience modification rate |
| Commercial Crime Insurance | $15 - $65 per month | Employees who handle money or inventory, internal controls and separation of duties, funds and securities on hand |
| Commercial Umbrella Insurance | $40 - $130 per month | Umbrella limit requested, limits carried on the underlying policies, loss history on those underlying policies |
Prices shown are general estimates, not guaranteed rates or quotes. Your actual premium will depend on the insurer, coverage selected, business details, location, claims history, and other underwriting factors. Learn about our pricing methodology.
State Requirements
Insurance Regulations in Michigan
Key regulatory requirements for businesses operating in MI.
Regulatory Authority
Workers' Compensation InsuranceRequired
Required for employers with 1+ employee.
Exempt categories
- Sole proprietors
- Partners
- Corporate officers
- Members of LLCs
Commercial Auto Minimum Liability
$50,000/$100,000/$10,000 (bodily injury per person / per accident / property damage)
Source: Michigan Department of Insurance, U.S. Department of Labor
Climate Risk Profile
Natural Disaster Risk in Michigan
Understanding climate-related risks helps determine appropriate insurance coverage levels.
Severe Storm
High
Winter Storm
High
Flooding
Moderate
Tornado
Moderate
Expected Annual Loss from Natural Hazards
$1.4B
estimated economic loss per year across Michigan
Source: FEMA National Risk Index
Insurance Tips for Retail Business Owners in Sterling Heights, MI
Match general liability coverage to your customer traffic, since high-volume locations tend to see more slip-and-fall and customer injury claims.
Review commercial property coverage so your limits reflect the actual value of the inventory and equipment you keep on-site.
If you run a warehouse-based e-commerce operation or fulfill orders from the back room, compare business owners policy options that combine property and liability in one package.
Consider commercial crime coverage if your store handles cash, gift cards, or frequent stock movement, since employee theft and fraud are common retail concerns to review.
Ask whether commercial umbrella coverage can add excess liability protection if your customer traffic is high or your contracts require higher coverage limits.
Build your policy around local exposures such as weather events, property crime, and business interruption so your limits fit the way your location actually operates.
Get Retail Insurance in Sterling Heights, MI
Enter your ZIP code to compare retail insurance rates from top carriers.
Business insurance starting at $25/mo
Retail Business Types in Sterling Heights, MI
Find insurance tailored to your specific retail business. Select your business type for coverage recommendations, pricing, and quotes:

Tailors Insurance
Get a tailors insurance quote built for alteration shops, seamstresses, and custom clothing businesses. Coverage can help with customer garment damage, liability coverage, and shop property needs.

Dry Cleaning & Laundry Insurance
Request a dry cleaning and laundry insurance quote built for garment-care businesses. Compare dry cleaner coverage, bailee liability insurance, and more.

Convenience Store Insurance
Get a convenience store insurance quote built for high foot traffic, cash handling, and food sales. Coverage can be tailored to your property, liability, and crime needs.

Liquor Store Insurance
Liquor store insurance helps protect alcohol retailers from property damage, theft, liability, and compliance-related claims. Request a liquor store insurance quote tailored to your location and operations.

Florist Insurance
Get florist insurance built around refrigeration, deliveries, and customer-facing shop risks. Compare coverage options and request a tailored quote for your retail flower shop.

Jewelry Store Insurance
Request a jewelry store insurance quote built for high-value inventory, theft exposure, and specialized valuation needs. Compare coverage options for showcases, back-room stock, and customer pieces.

Gas Station Insurance
Get a gas station insurance quote built around fuel handling, underground tanks, store operations, and location-specific requirements. Compare coverage options for your station, convenience store, and liability exposures.

Smoke Shop Insurance
Smoke shop insurance can help protect tobacco and vape retailers from product, property, and crime-related losses. Coverage can be tailored to your store’s location, inventory, and compliance needs.

Furniture Store Insurance
Get a furniture store insurance quote built for showroom traffic, delivery damage, and stored inventory. Compare coverage options for your store, warehouse, and deliveries.

Thrift Store Insurance
Get coverage built for donated inventory, customer injury, and store property. Request a thrift store insurance quote tailored to your resale shop, consignment shop, or secondhand store.

Pet Store Insurance
Get a pet store insurance quote built for retailers that sell live animals, pet food, and supplies. Compare liability, property, and business interruption options.

Hardware Store Insurance
Hardware stores face injury exposure in aisles, at the counter, and around tools, paint, and chemicals. Get coverage built for retail operations, inventory, and store incidents.

E-Commerce Business Insurance
E-commerce business insurance helps online sellers protect against product liability, cyber theft, and other digital-first risks. Request an ecommerce business insurance quote tailored to your store.

Grocery Store Insurance
Get a grocery store insurance quote designed for daily foot traffic, refrigerated inventory, and customer injury exposure. Coverage can be tailored for supermarkets, specialty food retailers, and multi-location stores.

Cell Phone Repair Insurance
Request a cell phone repair insurance quote built for repair counters, mall kiosks, and multi-location shops. Match coverage to device damage, data liability, and parts defects.

Craft Vendor Insurance
Get a craft vendor insurance quote for craft fairs, markets, and booth setups. Compare coverage for liability, inventory, and event property needs.

Arts & Crafts Store Insurance
Get an arts and crafts store insurance quote built for craft supply shops with flammable inventory, customer traffic, and property exposure. Coverage can be matched to your store layout, stock, and operations.

Bike Shop Insurance
Bike shops need coverage for customer injuries, repair work, inventory theft, and property loss. Get a quote-ready policy built for retail sales, service bays, and storefront risk.

Bookstore Insurance
Get a bookstore insurance quote built around your shop's property, inventory, and premises liability needs, with options that can help protect your storefront, stock, and income after a setback.

Candle Store Insurance
Get a candle store insurance quote built for candle retailers, wax product shops, and multi-location stores. Compare options for product liability, fire coverage, and property protection.

Candy Store Insurance
Get a candy store insurance quote for storefront property, customer foot traffic, and food-related liability exposures. Coverage can be tailored for retail candy shops, kiosks, and confectionery retailers.

Clothing Store Insurance
Get a clothing store insurance quote built for boutiques, apparel stores, and fashion retailers. Compare coverage for inventory, customer injury, and property needs.

Electronics Store Insurance
Request an electronics store insurance quote tailored to high-value inventory, customer claims, cyber risks, and retail property needs. Coverage options can fit a storefront, repair counter, or technology showroom.

Fabric Store Insurance
Get a fabric store insurance quote designed for textile retailers handling inventory, fixtures, and customer visits. Compare liability and property coverage options for your shop.

Luggage Store Insurance
Luggage store insurance can help protect retailers that sell luggage and travel accessories against customer injury claims, inventory losses, and premises damage. Compare quote options built around your storefront, stock, and daily foot traffic.

Medical Supplies Store Insurance
Get a medical supplies store insurance quote built for retail locations that sell patient-dependent products, durable equipment, and inventory customers rely on. Choose coverage that fits your storefront, showroom, and delivery needs.

Pawn Shop Insurance
Get a pawn shop insurance quote built around customer property, cash handling, inventory, and location-specific risk. Compare options for a single shop or multi-location operation.

Retail Store Insurance
Get a retail store insurance quote built around your shop's location, inventory, and customer traffic. Compare coverage options for liability, property, and business interruption.

Toy Store Insurance
A toy store insurance quote helps match your retail risks with the coverage you may need for customer injuries, property damage, and defective products. Compare options for your storefront, inventory, and daily operations.
FAQ
Retail Insurance FAQ in Sterling Heights, MI
Many retailers review protection for bodily injury, property damage, legal defense, and building damage tied to covered events. Commercial property coverage may also address inventory, equipment, and fixtures.
Yes, the risk profile can differ from a traditional store. Customer flow, storage space, and property exposure all shift with the format, which can change what your policy should include.
Insurers may look at your location type, inventory value, building features, and exposure to weather and property crime. A store in a shopping center or mixed-use retail space may be rated differently than a warehouse-based e-commerce operation.
A business owners policy can combine property and liability coverage in one package. Whether that fits your operation depends on your store size, inventory, and the limits you need.
If your store handles cash, merchandise, or frequent inventory movement, commercial crime coverage may be worth comparing. It can help address employee theft and fraud exposures that a standard policy might not include.
General liability and commercial property form the core, and many stores package them through a business owners policy. Add workers compensation once you have employees, commercial crime where staff handle cash or resellable stock, and umbrella limits when a lease or heavy foot traffic calls for more liability capacity.
Yes, the exposures shift even though the products are the same. Inventory concentrates in storage areas, fulfillment drives the workday, and returns and packing change the injury and theft picture, so property values, employee duties, and transit arrangements deserve their own look.
A shopping center's program centers on common areas, maintenance responsibility, vendor access, and lease requirements across many tenants. A single tenant focuses on its own premises, inventory, tenant improvements, and whatever insurance wording the landlord requires.